Facebook
 X
 Pinterest
 Copy Link
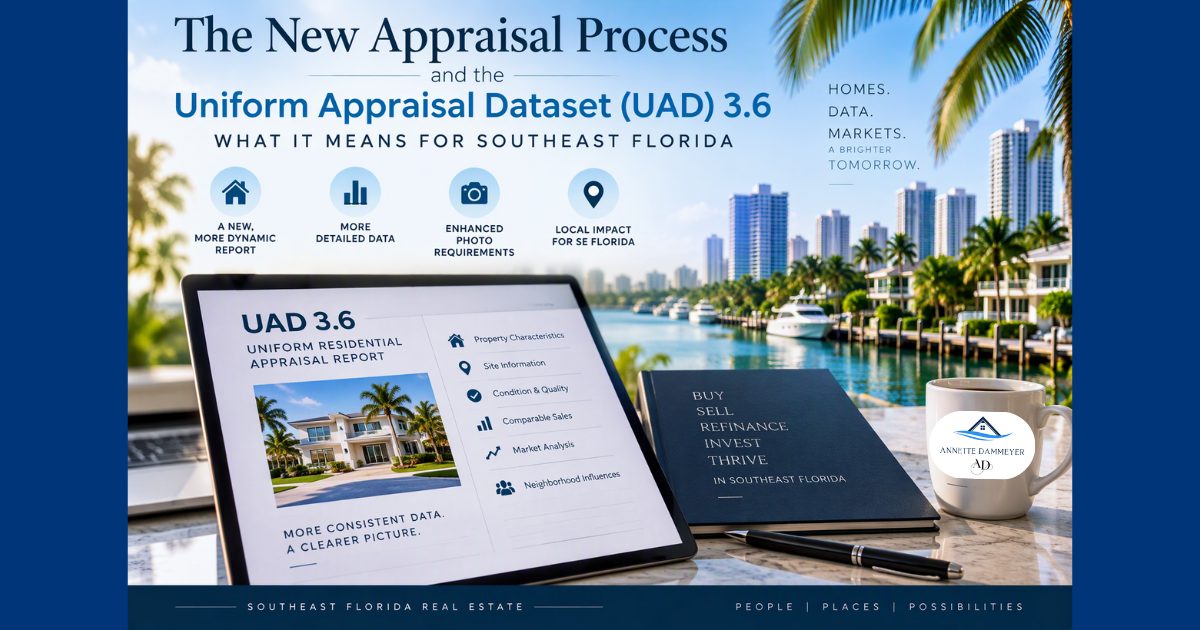
Understanding the New Appraisal Process: UAD 3.6 and the Redesigned Appraisal Report
If you’re buying, selling, refinancing, or investing in real estate, a major change is underway in the mortgage and appraisal industry. Fannie Mae and Freddie Mac have introduced the new Uniform Appraisal Dataset (UAD) 3.6 and a completely redesigned appraisal reporting system that modernizes how residential property valuations are completed and delivered. This change affects appraisers, lenders, mortgage brokers, Realtors®, buyers, and sellers across the country, including here in Southeast Florida.
What Is UAD 3.6?
The Uniform Appraisal Dataset (UAD) is the standardized format appraisers use when preparing appraisal reports for loans sold to Fannie Mae and Freddie Mac. The goal is to ensure consistency, improve data quality, and make appraisal information easier to analyze electronically.
The previous version, known as UAD 2.6, relied heavily on traditional static forms and narrative comments. Under the new UAD 3.6 standard, appraisal data is more structured, detailed, and consistent across all residential property types. The updated framework aligns with the mortgage industry’s MISMO® 3.6 data standards and introduces a more data-driven approach to reporting.
Why Was the Appraisal Process Changed?
The appraisal forms most of the industry has used for decades were designed long before today’s digital lending environment.
Fannie Mae and Freddie Mac identified several challenges with the older system:
- Important information often ended up buried in narrative comments.
- Different appraisers could report similar properties differently.
- Static forms were not flexible enough for today’s diverse housing inventory.
- Lenders and investors needed more consistent data for risk assessment and quality control.
The redesigned system addresses these issues by creating a more uniform, transparent, and technology-friendly reporting process.
What’s Different About the New Appraisal Report?
One Dynamic Report Replaces Multiple Forms
Historically, appraisers selected from various forms depending on the property type, such as:
- Form 1004 for single-family homes
- Form 1073 for condominiums
- Other specialized forms for exterior-only or hybrid appraisals
Under UAD 3.6, these legacy forms are replaced by a single dynamic Uniform Residential Appraisal Report (URAR) that adapts based on the property being appraised.
More Detailed Property Data
The new format collects substantially more structured information, including:
- Property characteristics
- Site information
- Construction quality
- Condition ratings
- Market trends
- Comparable sales analysis
- Neighborhood influences
Instead of relying on lengthy narrative explanations, appraisers complete required data fields designed to improve consistency across reports.
Enhanced Photo and Image Requirements
The redesign places greater emphasis on photographic documentation and visual evidence, helping lenders and reviewers better understand the property’s condition and marketability.
When Does UAD 3.6 Take Effect?
The transition has been occurring in phases, with the industry moving toward mandatory adoption. Fannie Mae and Freddie Mac established a UAD 3.6 mandate beginning November 2, 2026, with limited policy exceptions available for certain lenders completing their transition.
How UAD 3.6 Impacts Southeast Florida
For homeowners, buyers, and sellers in Broward, Palm Beach, and Miami-Dade Counties, these changes can be particularly significant because Southeast Florida contains many unique property types and market influences.
Waterfront Properties Will Receive More Granular Analysis
South Florida’s luxury market includes:
- Deep-water homes
- Intracoastal properties
- Oceanfront residences
- Gated waterfront communities
- Properties with private dockage
Under UAD 3.6, appraisers have expanded data collection tools that allow them to better document unique characteristics such as:
- Water frontage
- Dock facilities
- Boating access
- View premiums
- Property-specific site influences
This could result in more transparent reporting for luxury waterfront homes in communities such as Coral Ridge, Las Olas Isles, Rio Vista, Harbor Beach, Lighthouse Point, and Boca Raton waterfront neighborhoods.
Condominiums May See More Detailed Reporting
Condominium valuation has become increasingly important throughout Southeast Florida following new structural integrity and reserve requirements enacted after the Surfside tragedy.
The enhanced reporting framework allows appraisers to capture more standardized information about:
- Condominium projects
- Building characteristics
- Unit features
- Market trends
- Comparable sales
While the new appraisal process does not replace lender condo reviews, it provides more consistent data that can assist in evaluating condominium properties throughout cities like Fort Lauderdale, Hollywood, Miami, Sunny Isles Beach, Boca Raton, and West Palm Beach.
Flood Risk and Environmental Factors Become More Important
Southeast Florida buyers increasingly ask about:
- Flood zones
- Flood insurance requirements
- Sea level concerns
- Drainage issues
- Water intrusion history
Although appraisers do not perform environmental inspections, UAD 3.6’s enhanced data structure creates more opportunities to document site characteristics and neighborhood influences that affect marketability and value.
As flood risk continues to influence buyer behavior and insurance costs, lenders and investors are placing greater emphasis on reliable property data.
Greater Consistency in Rapidly Changing Markets
South Florida has experienced dramatic price appreciation, inventory fluctuations, rising insurance costs, and changing buyer preferences over the last several years.
The redesigned appraisal report aims to:
- Reduce ambiguity
- Improve data consistency
- Strengthen comparable sale analysis
- Improve review efficiency
This may help appraisers and lenders better navigate dynamic markets like Fort Lauderdale, Delray Beach, Boca Raton, Palm Beach Gardens, Hollywood, and Miami.
What Buyers and Sellers Should Expect
For Sellers
The new system means property features and improvements will be documented more systematically.
Sellers should:
- Maintain records of renovations and permits.
- Provide documentation of major upgrades.
- Keep receipts for significant improvements.
- Ensure appraisers have access to all property features.
This can help appraisers accurately capture value-enhancing characteristics.
For Buyers
Expect appraisal reports to become more comprehensive and data driven.
The process may improve transparency regarding:
- Property condition
- Market comparisons
- Location influences
- Value conclusions
For Real Estate Agents
Agents will want to provide appraisers with:
- Accurate sales data
- Improvement lists
- Neighborhood insights
- Information on unique property features
The more complete the information available, the easier it becomes for appraisers to accurately represent a property’s market position.
Bottom Line
The introduction of UAD 3.6 and the redesigned Uniform Residential Appraisal Report (URAR) represents the most significant appraisal modernization effort in decades. By replacing outdated forms with a dynamic, data-driven reporting system, Fannie Mae and Freddie Mac aim to improve consistency, transparency, and appraisal quality across the mortgage industry.
For Southeast Florida homeowners, buyers, and sellers, the changes are especially relevant due to the region’s unique mix of waterfront properties, luxury homes, condominiums, flood-related considerations, and rapidly evolving market conditions. While the appraisal process may look different behind the scenes, the ultimate goal remains the same: providing a credible and accurate opinion of value that reflects today’s marketplace.
As a local real estate professional, I believe staying informed is one of the best ways to make confident real estate decisions. The new UAD 3.6 appraisal process is designed to bring greater transparency, consistency, and accuracy to property valuations, and understanding these changes can help buyers, sellers, and homeowners better navigate today’s market.
Reach out anytime for trusted guidance, local market insight, and personalized real estate advice.
CONTACT ANNETTE
Let’s start working together!
Annette Dammeyer, REALTOR®, ABR®, AHWD®
Coldwell Banker Realty
901 E Las Olas Blvd STE 101, Fort Lauderdale, FL 33301
808.747.3686
SL 3535792