
 Facebook
 X
 Pinterest
 Copy Link
The Truth About Home Equity
Home Equity in Southeast Florida:
Myths, Realities, and Smart Ways to Use It (Without Risking Your Future)
If you’re a homeowner in Southeast Florida, chances are you’ve heard the phrase “You’re sitting on a lot of equity.”
With home values rising across Fort Lauderdale, Broward County, and throughout Southeast Florida, many homeowners are equity‑rich—but still unsure what that really means.
As a real estate agent who’s helped hundreds of homeowners navigate buying, selling, and long-term planning, I want to clear up the biggest myths about home equity, explain the real opportunities, and—equally important—talk honestly about the risks.
This is not hype. It’s real-world guidance.
What Is Home Equity? (Quick, Clear Answer)
Home equity is the difference between what your home is worth today and what you still owe on your mortgage.
Example:
- Home value: $600,000
- Mortgage balance: $350,000
- Home equity: $250,000
Equity is not cash in your pocket—but it can become a powerful financial tool if used wisely.
Common Myths About Home Equity
Myth #1: “Home Equity Is Free Money”
Reality: Equity is borrowed money if you tap into it.
Whether through a Home Equity Line of Credit (HELOC), cash‑out refinance, or reverse mortgage, you’re increasing debt or reducing ownership.
✔ Smart use: Strategic investing, home improvements, life planning
✘ Risky use: Lifestyle spending, guessing investments, short-term fixes
Myth #2: “I Should Use My Equity While Rates Are Low—No Matter What”
Reality: Your reason matters more than the interest rate.
Rates go up and down. Poor decisions last far longer.
Before tapping equity, ask:
- Will this improve my financial position in 5–10 years?
- Does this increase risk if the market shifts?
- Could I still afford payments during retirement or hardship?
Myth #3: “My Home Equity Will Always Grow”
Reality: Markets change.
South Florida real estate has been strong, but:
- Values can flatten or decline
- Insurance costs and property taxes can rise
- Over-leveraging reduces flexibility
Equity is safest when treated as a buffer, not a guarantee.
Smart Ways South Florida Homeowners Use Home Equity
When used intentionally, equity can be a powerful tool.
✅ Home Improvements That Increase Value
Certain upgrades—kitchens, bathrooms, impact windows, roof replacements—can:
- Increase resale value
- Improve insurability
- Lower energy or insurance costs
💡 Tip: Not all renovations add value. Always look at local resale trends.
✅ Consolidating High-Interest Debt (Carefully)
Replacing high-interest credit card debt with lower-interest home equity can help—only if spending habits change.
Otherwise, homeowners often fall back into credit card debt and carry more mortgage debt.
✅ Funding Strategic Life Transitions
Common smart uses I see locally:
- Downsizing prep before retirement
- Helping with a child’s education (with clear boundaries)
- Bridge financing before selling and buying
✅ Real Estate Investment (With Professional Advice)
Some Southeast Florida homeowners use equity to:
- Buy rental properties
- Invest in multi-generational housing
- Create passive income
This only works with:
- Conservative numbers
- Professional tax and financial guidance
- Realistic vacancy and expense planning
The Real Risks of Using Home Equity
This is the part most blogs skip—but I won’t.
⚠ Over-Leveraging Your Home
Your home is your largest financial safety net.
Tapping too much equity can:
- Reduce options during job loss or illness
- Make selling harder during market shifts
- Impact retirement security
⚠ Adjustable Interest Rates
Many HELOCs have variable rates. Payments can rise quickly.
If payments increase:
- Would your budget still work?
- Would retirement plans be affected?
⚠ Using Equity to Support Unsustainable Spending
Equity should solve long-term problems—not fund short-term habits.
If equity is covering lifestyle gaps, it’s time for a financial reset—not more borrowing.
Frequently Asked Questions
Is it a good idea to use home equity in South Florida?
It depends on your goals, risk tolerance, and long-term plans. Strategic uses can help build wealth, but misuse can create serious financial vulnerability.
How much home equity should I leave untouched?
Many financial professionals suggest keeping at least 30–40% equity as a cushion, especially heading into retirement or uncertain markets.
Should I talk to a real estate agent before using equity?
Yes. A local agent can:
- Assess realistic home value
- Explain resale impact
- Coordinate with financial and lending professionals
My Professional Advice as a Southeast Florida Real Estate Agent
Home equity should support stability, flexibility, and future goals, not stress.
Before you tap into it, you should clearly understand:
- Your home’s true market value
- Long-term payment impact
- Exit strategies if circumstances change
Every homeowner’s situation is different—especially here in Southeast Florida where insurance, taxes, and market cycles matter.
Your home isn’t just an asset.
It’s your security, your future, and often your legacy.
Used wisely, home equity can help you build wealth.
Used carelessly, it can quietly take it away.
If you ever want a no-pressure, local perspective on your home’s value or long-term options, I’m always happy to help my community make informed decisions.
Because smart real estate decisions aren’t just about today—they’re about protecting tomorrow.
CONTACT ANNETTE
Let’s start working together!
Annette Dammeyer, REALTOR®, ABR®, AHWD®
Coldwell Banker Realty
901 E Las Olas Blvd STE 101, Fort Lauderdale, FL 33301
808.747.3686
SL 3535792
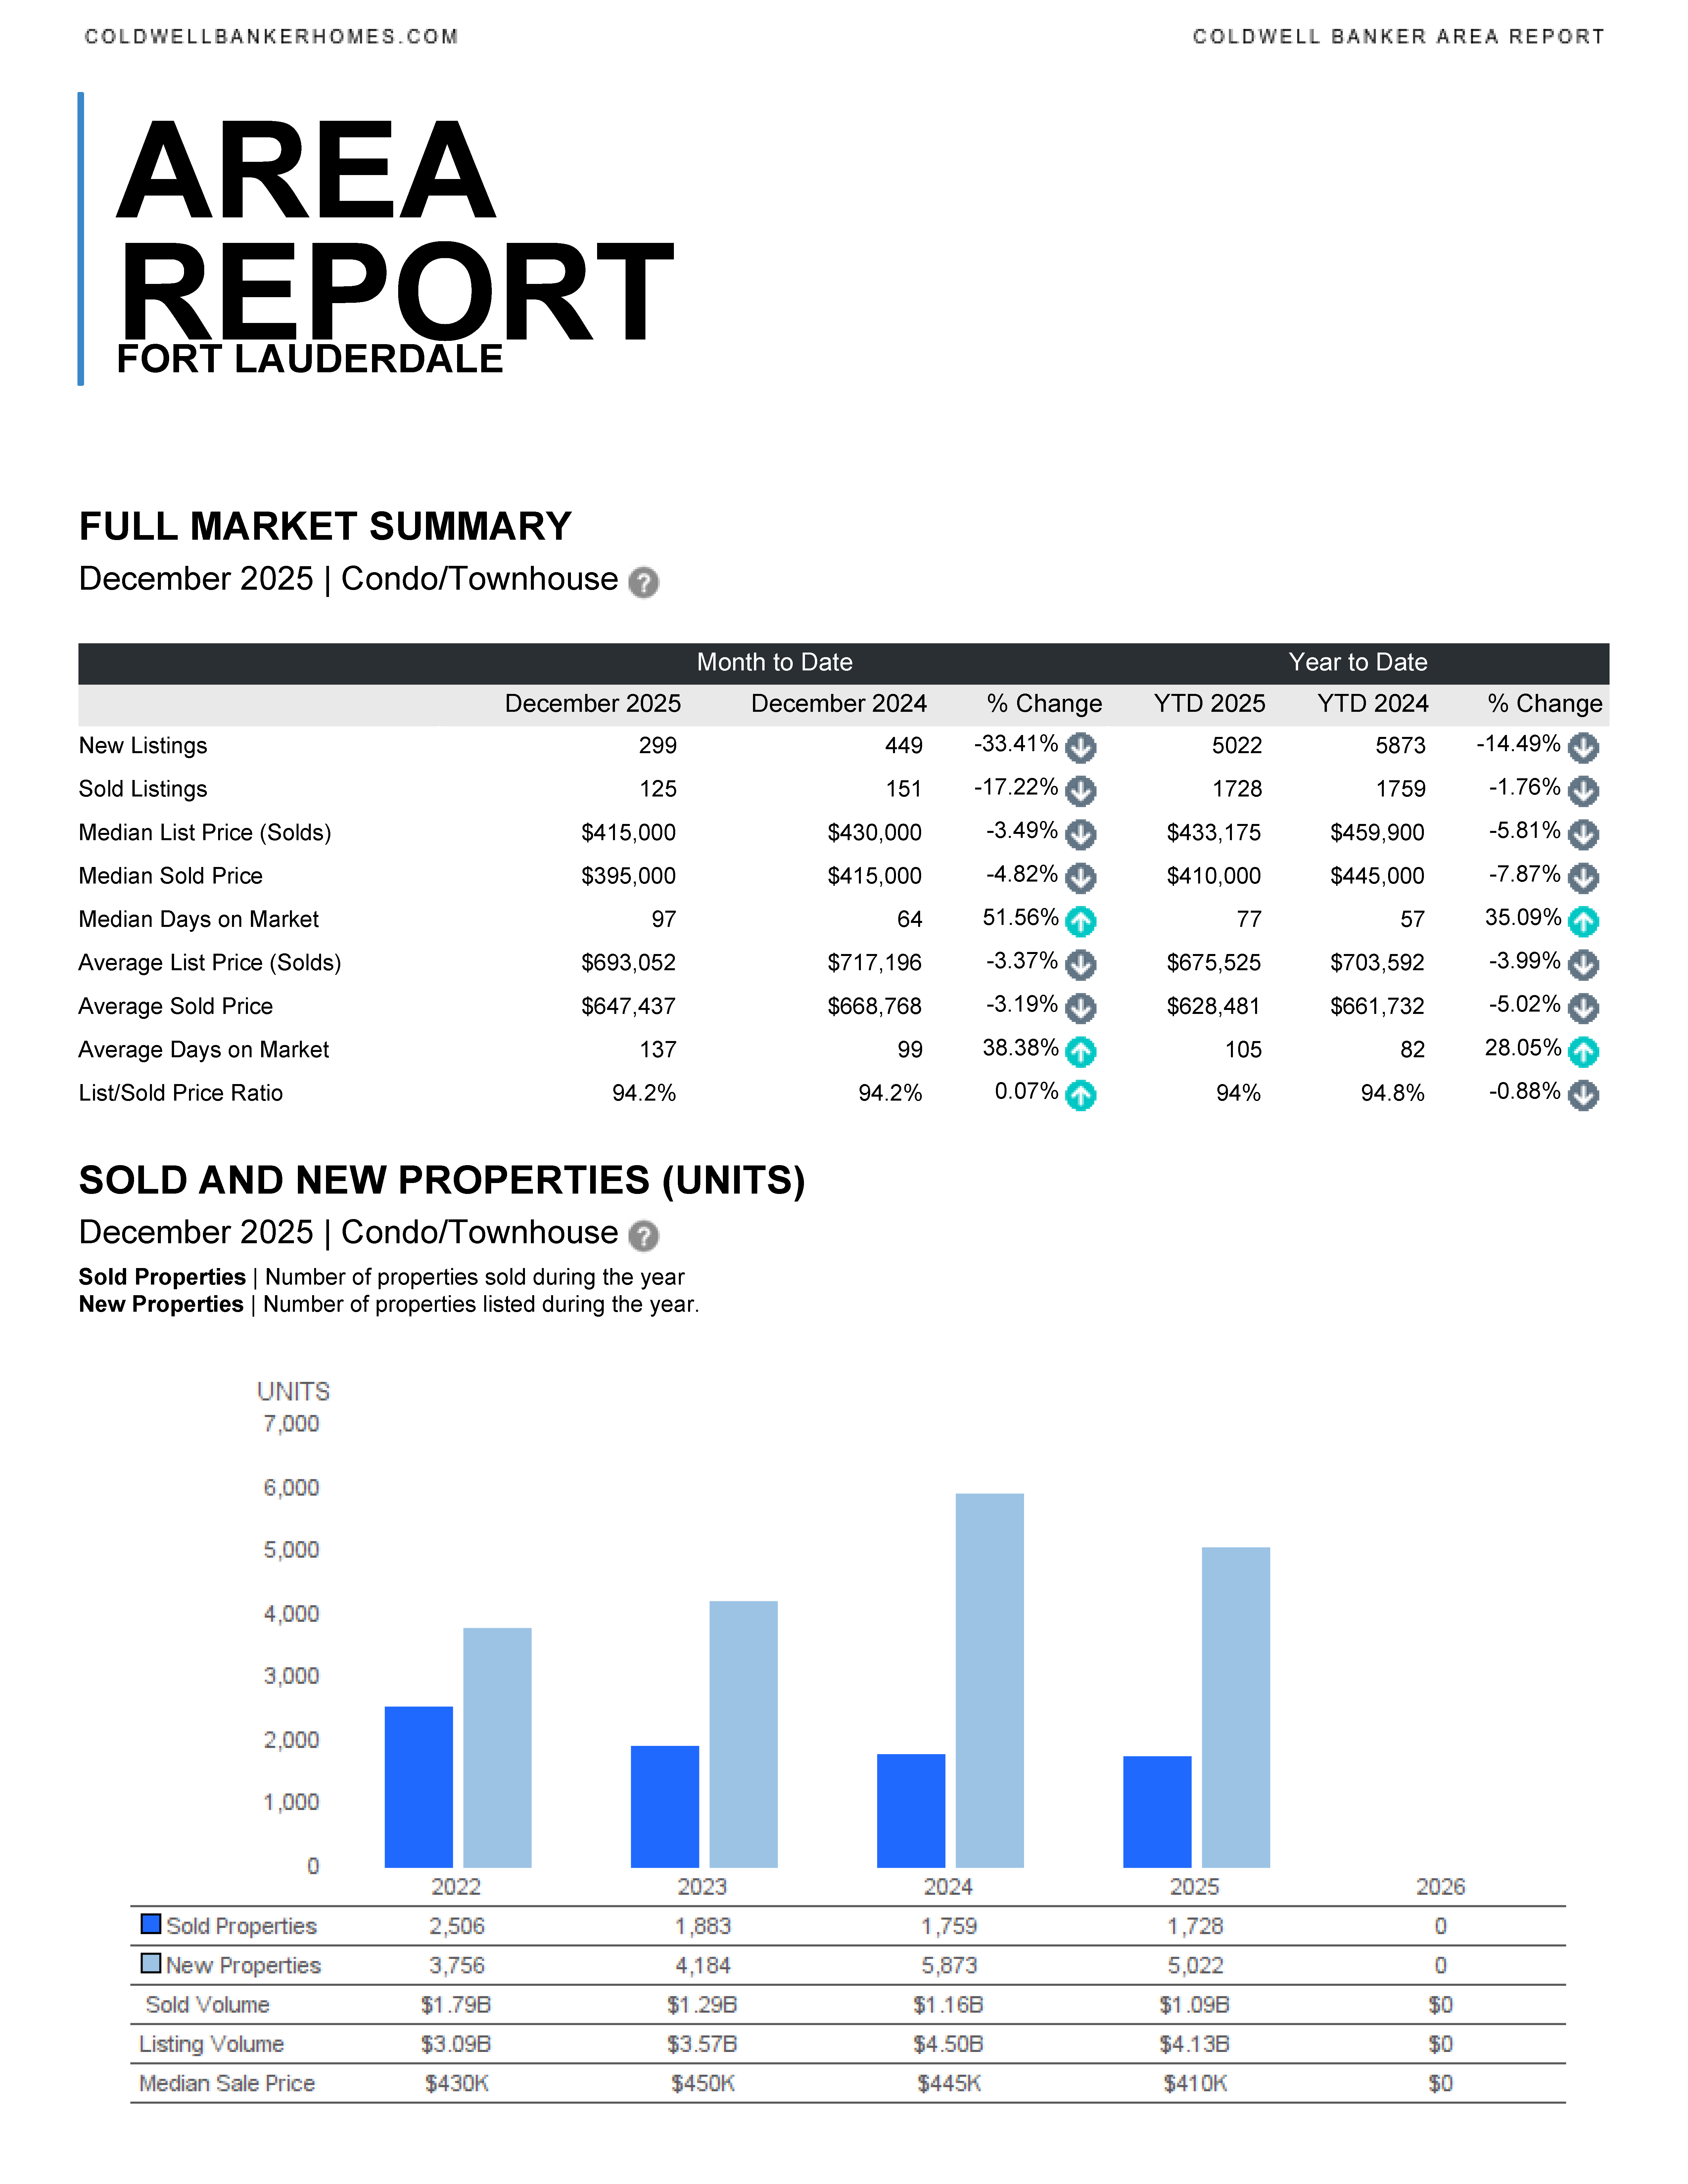
Fort Lauderdale December 2025 Area Report
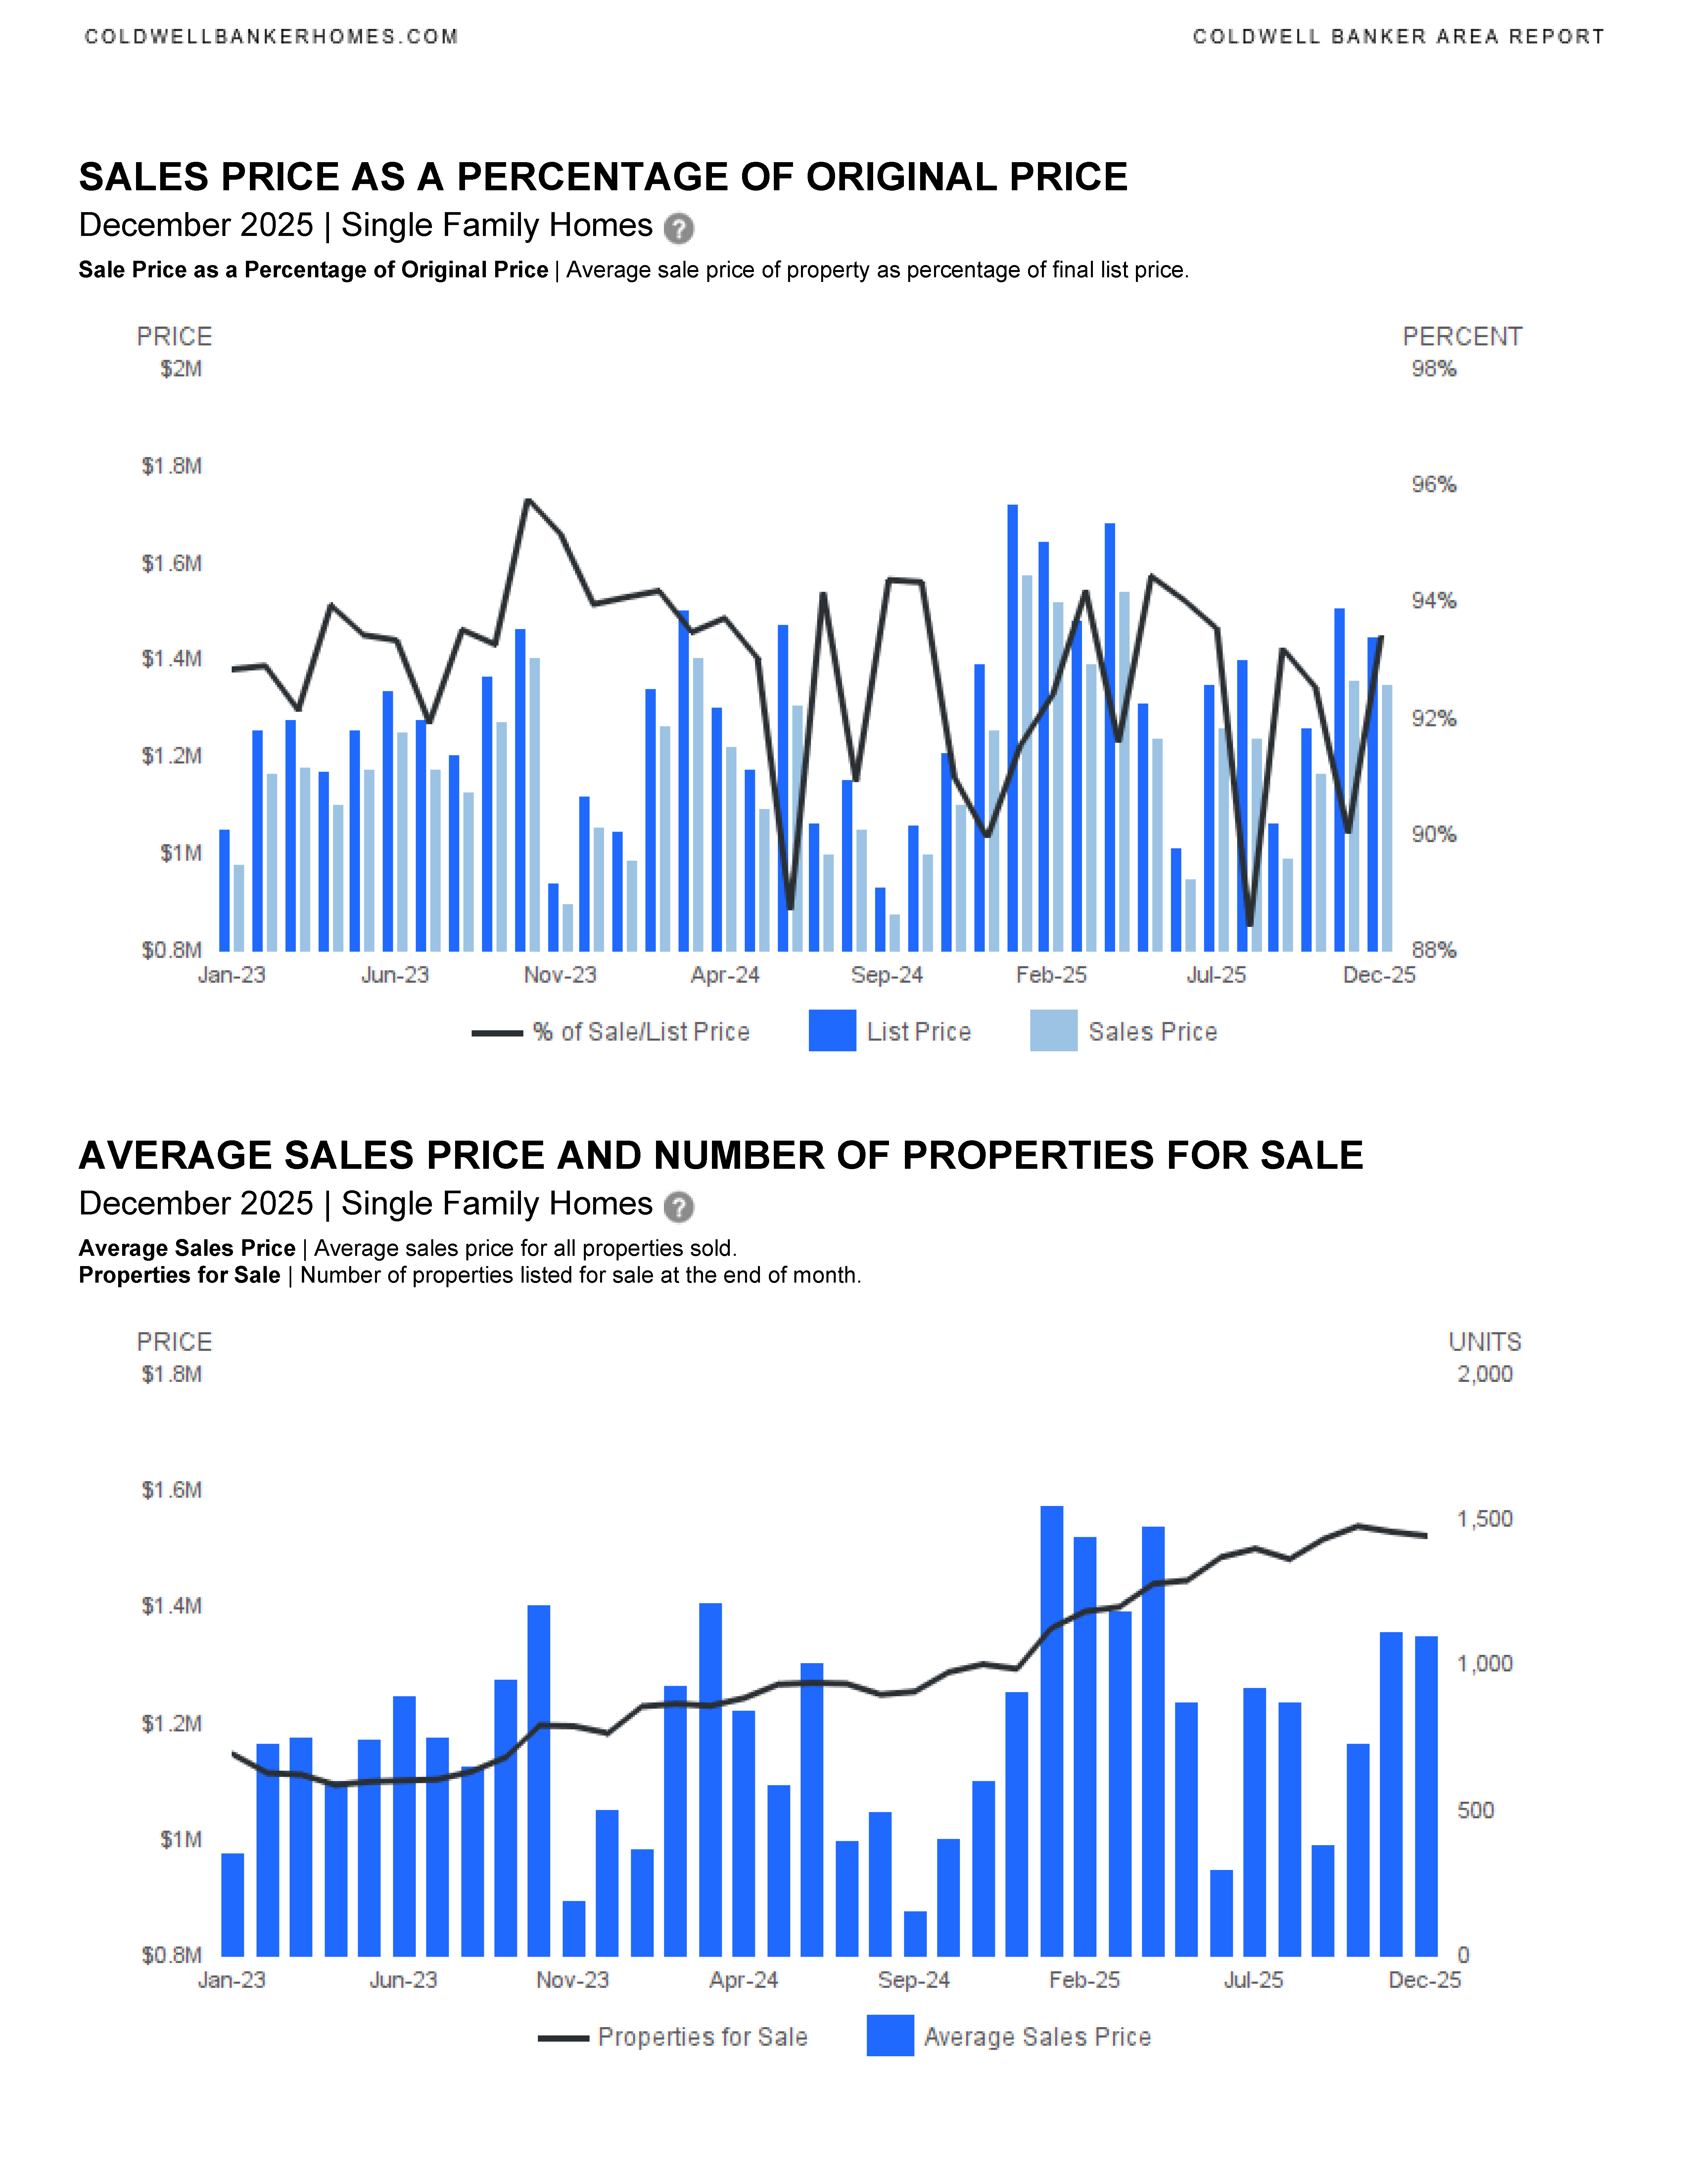
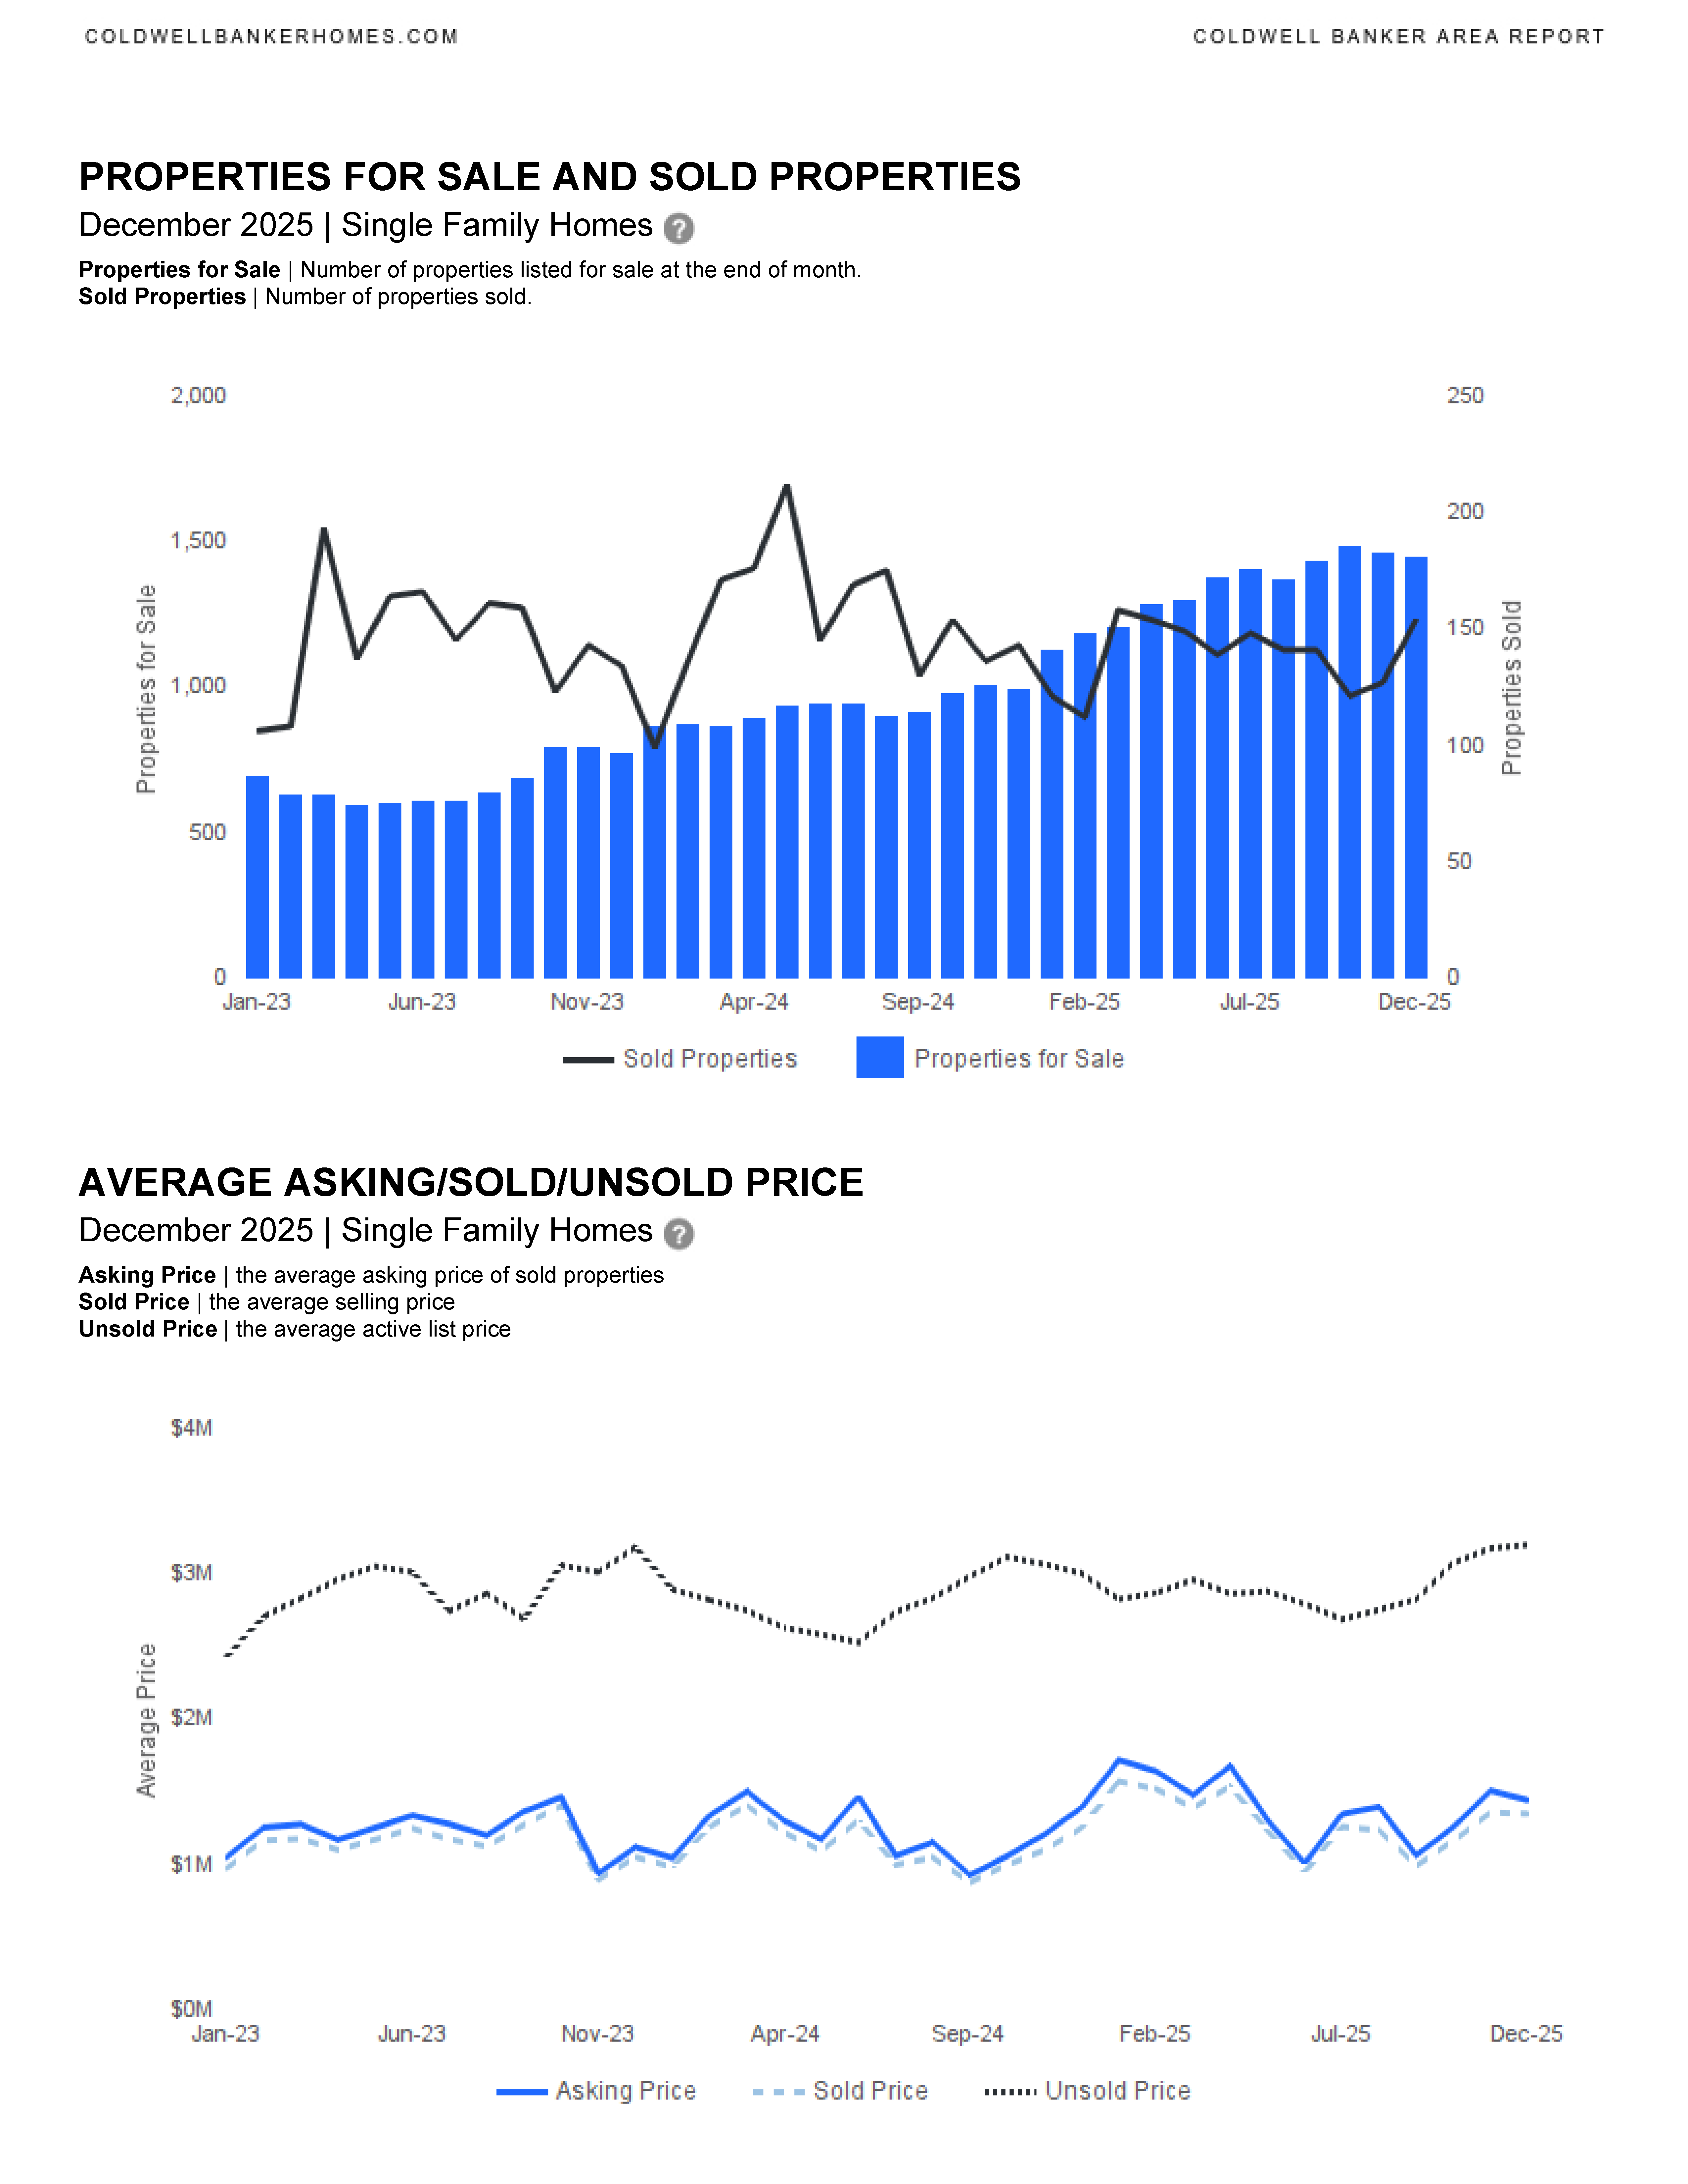
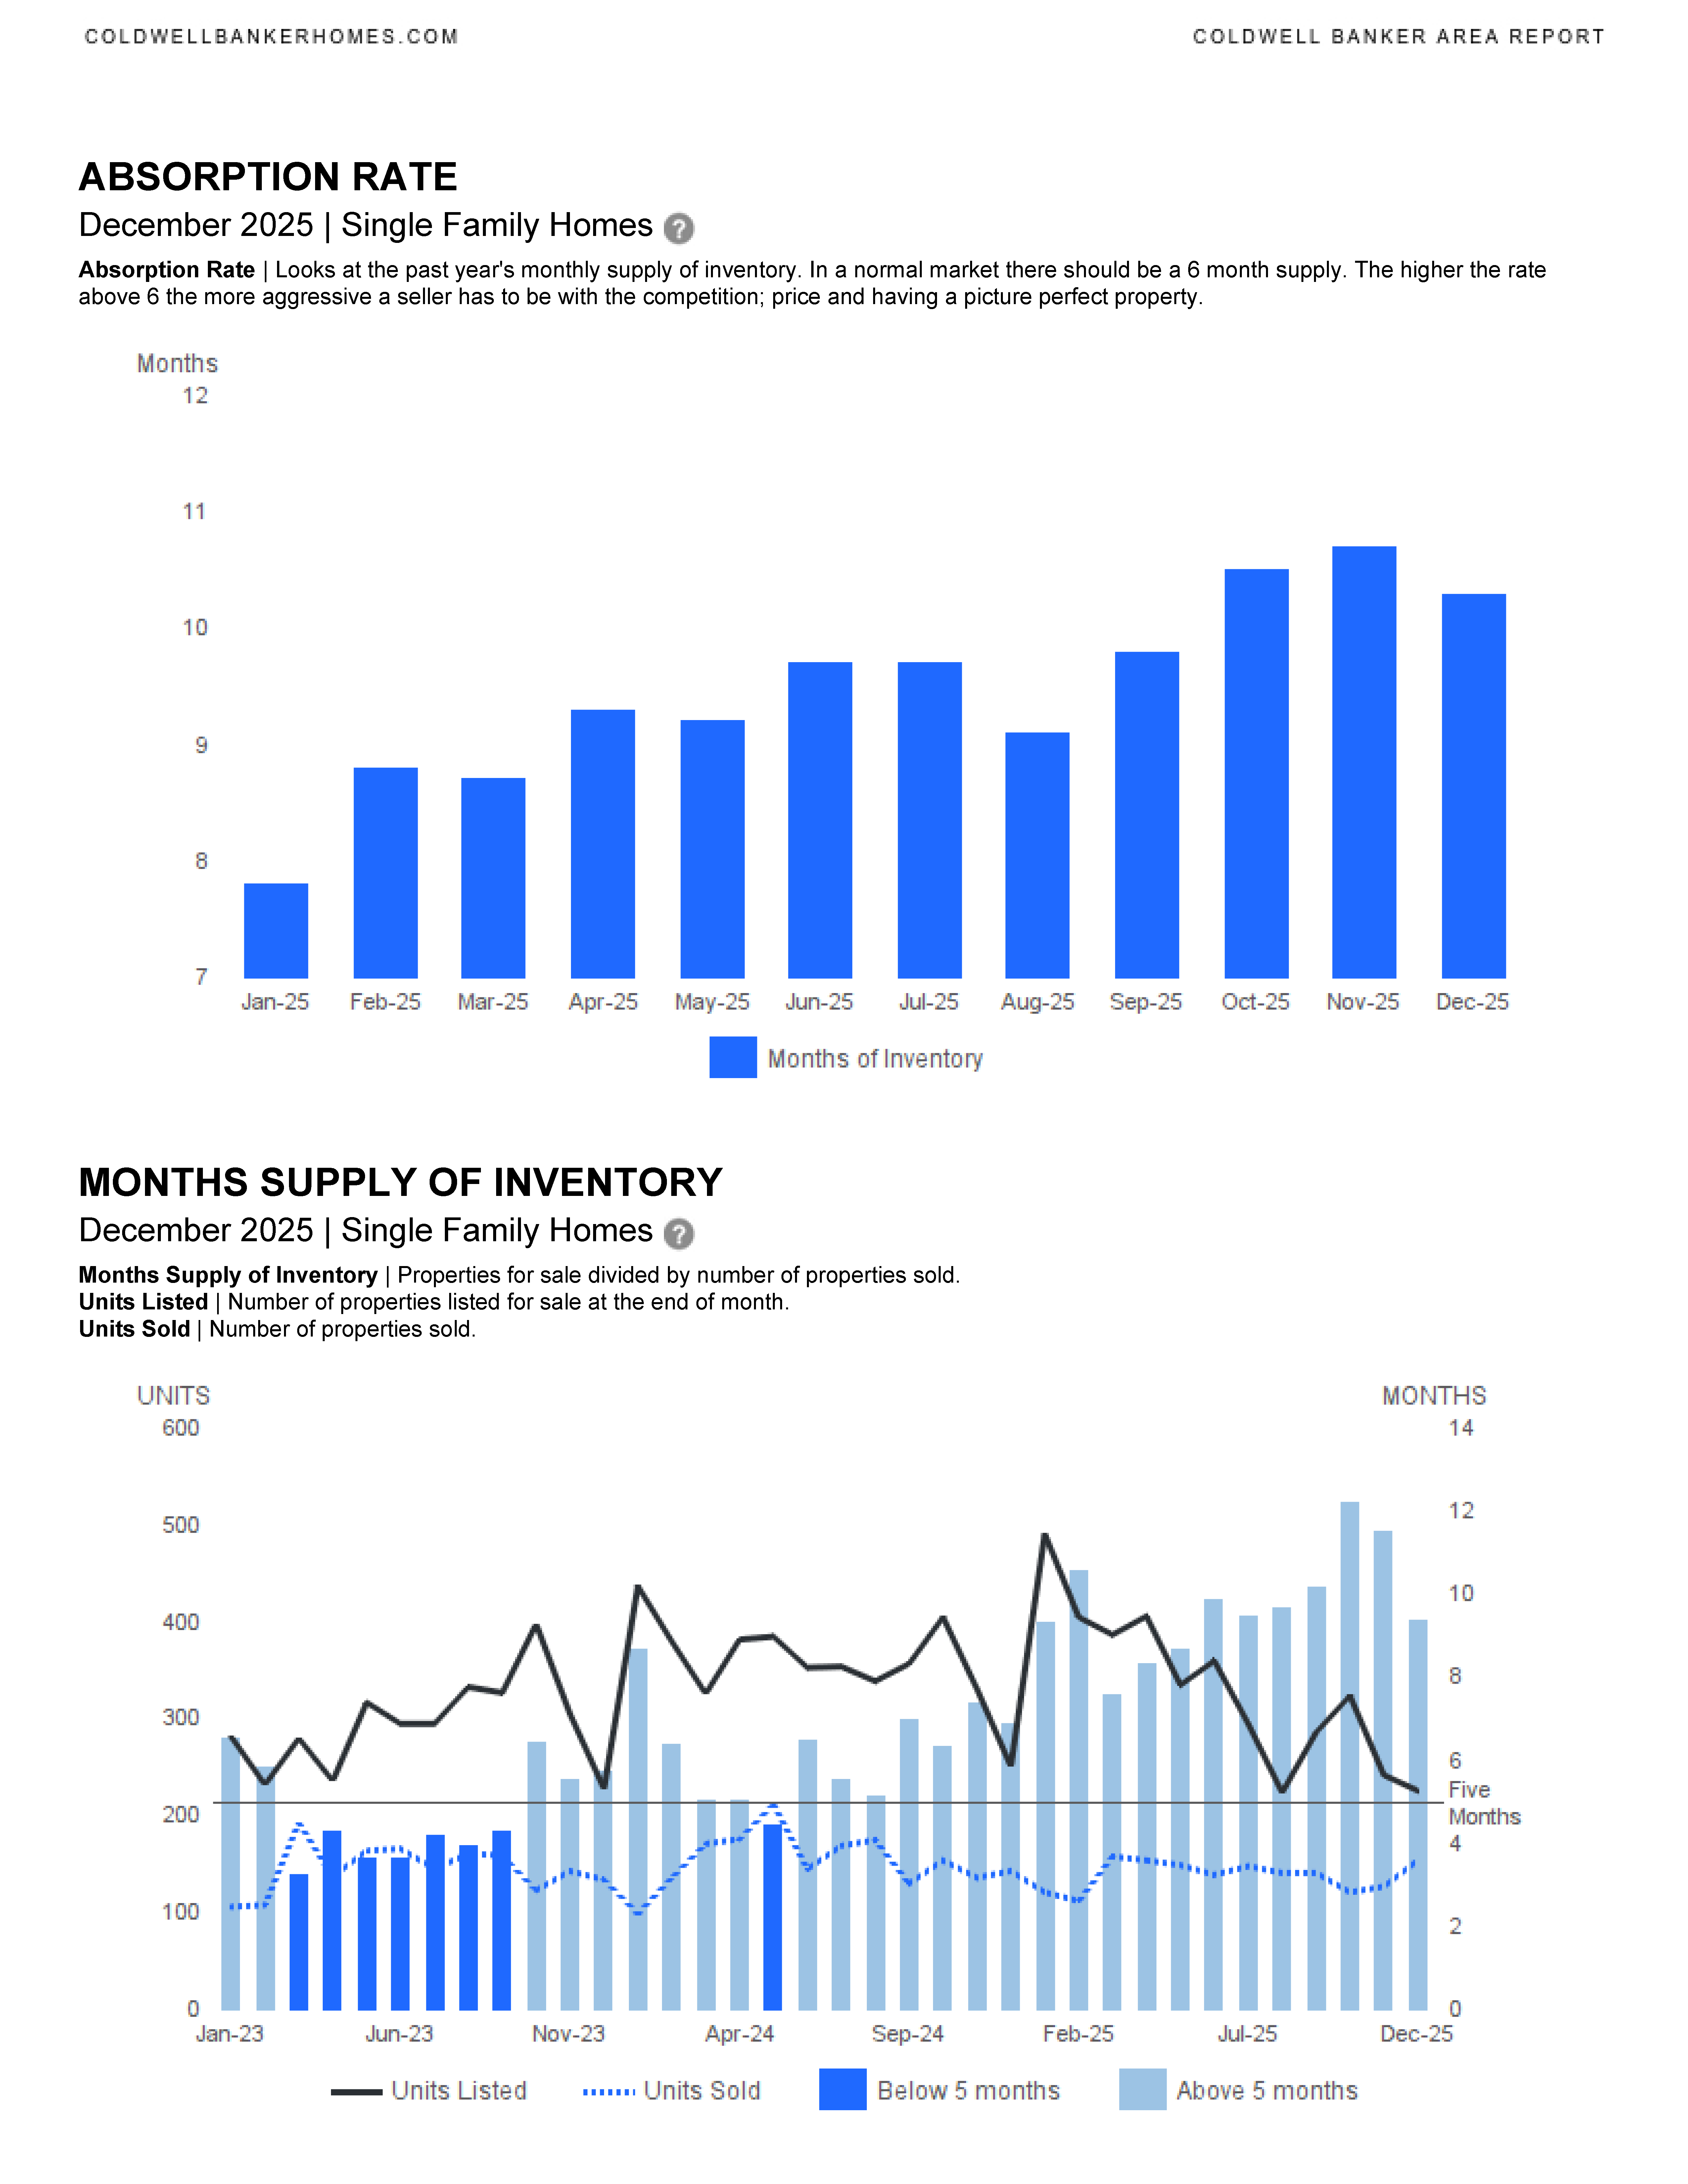
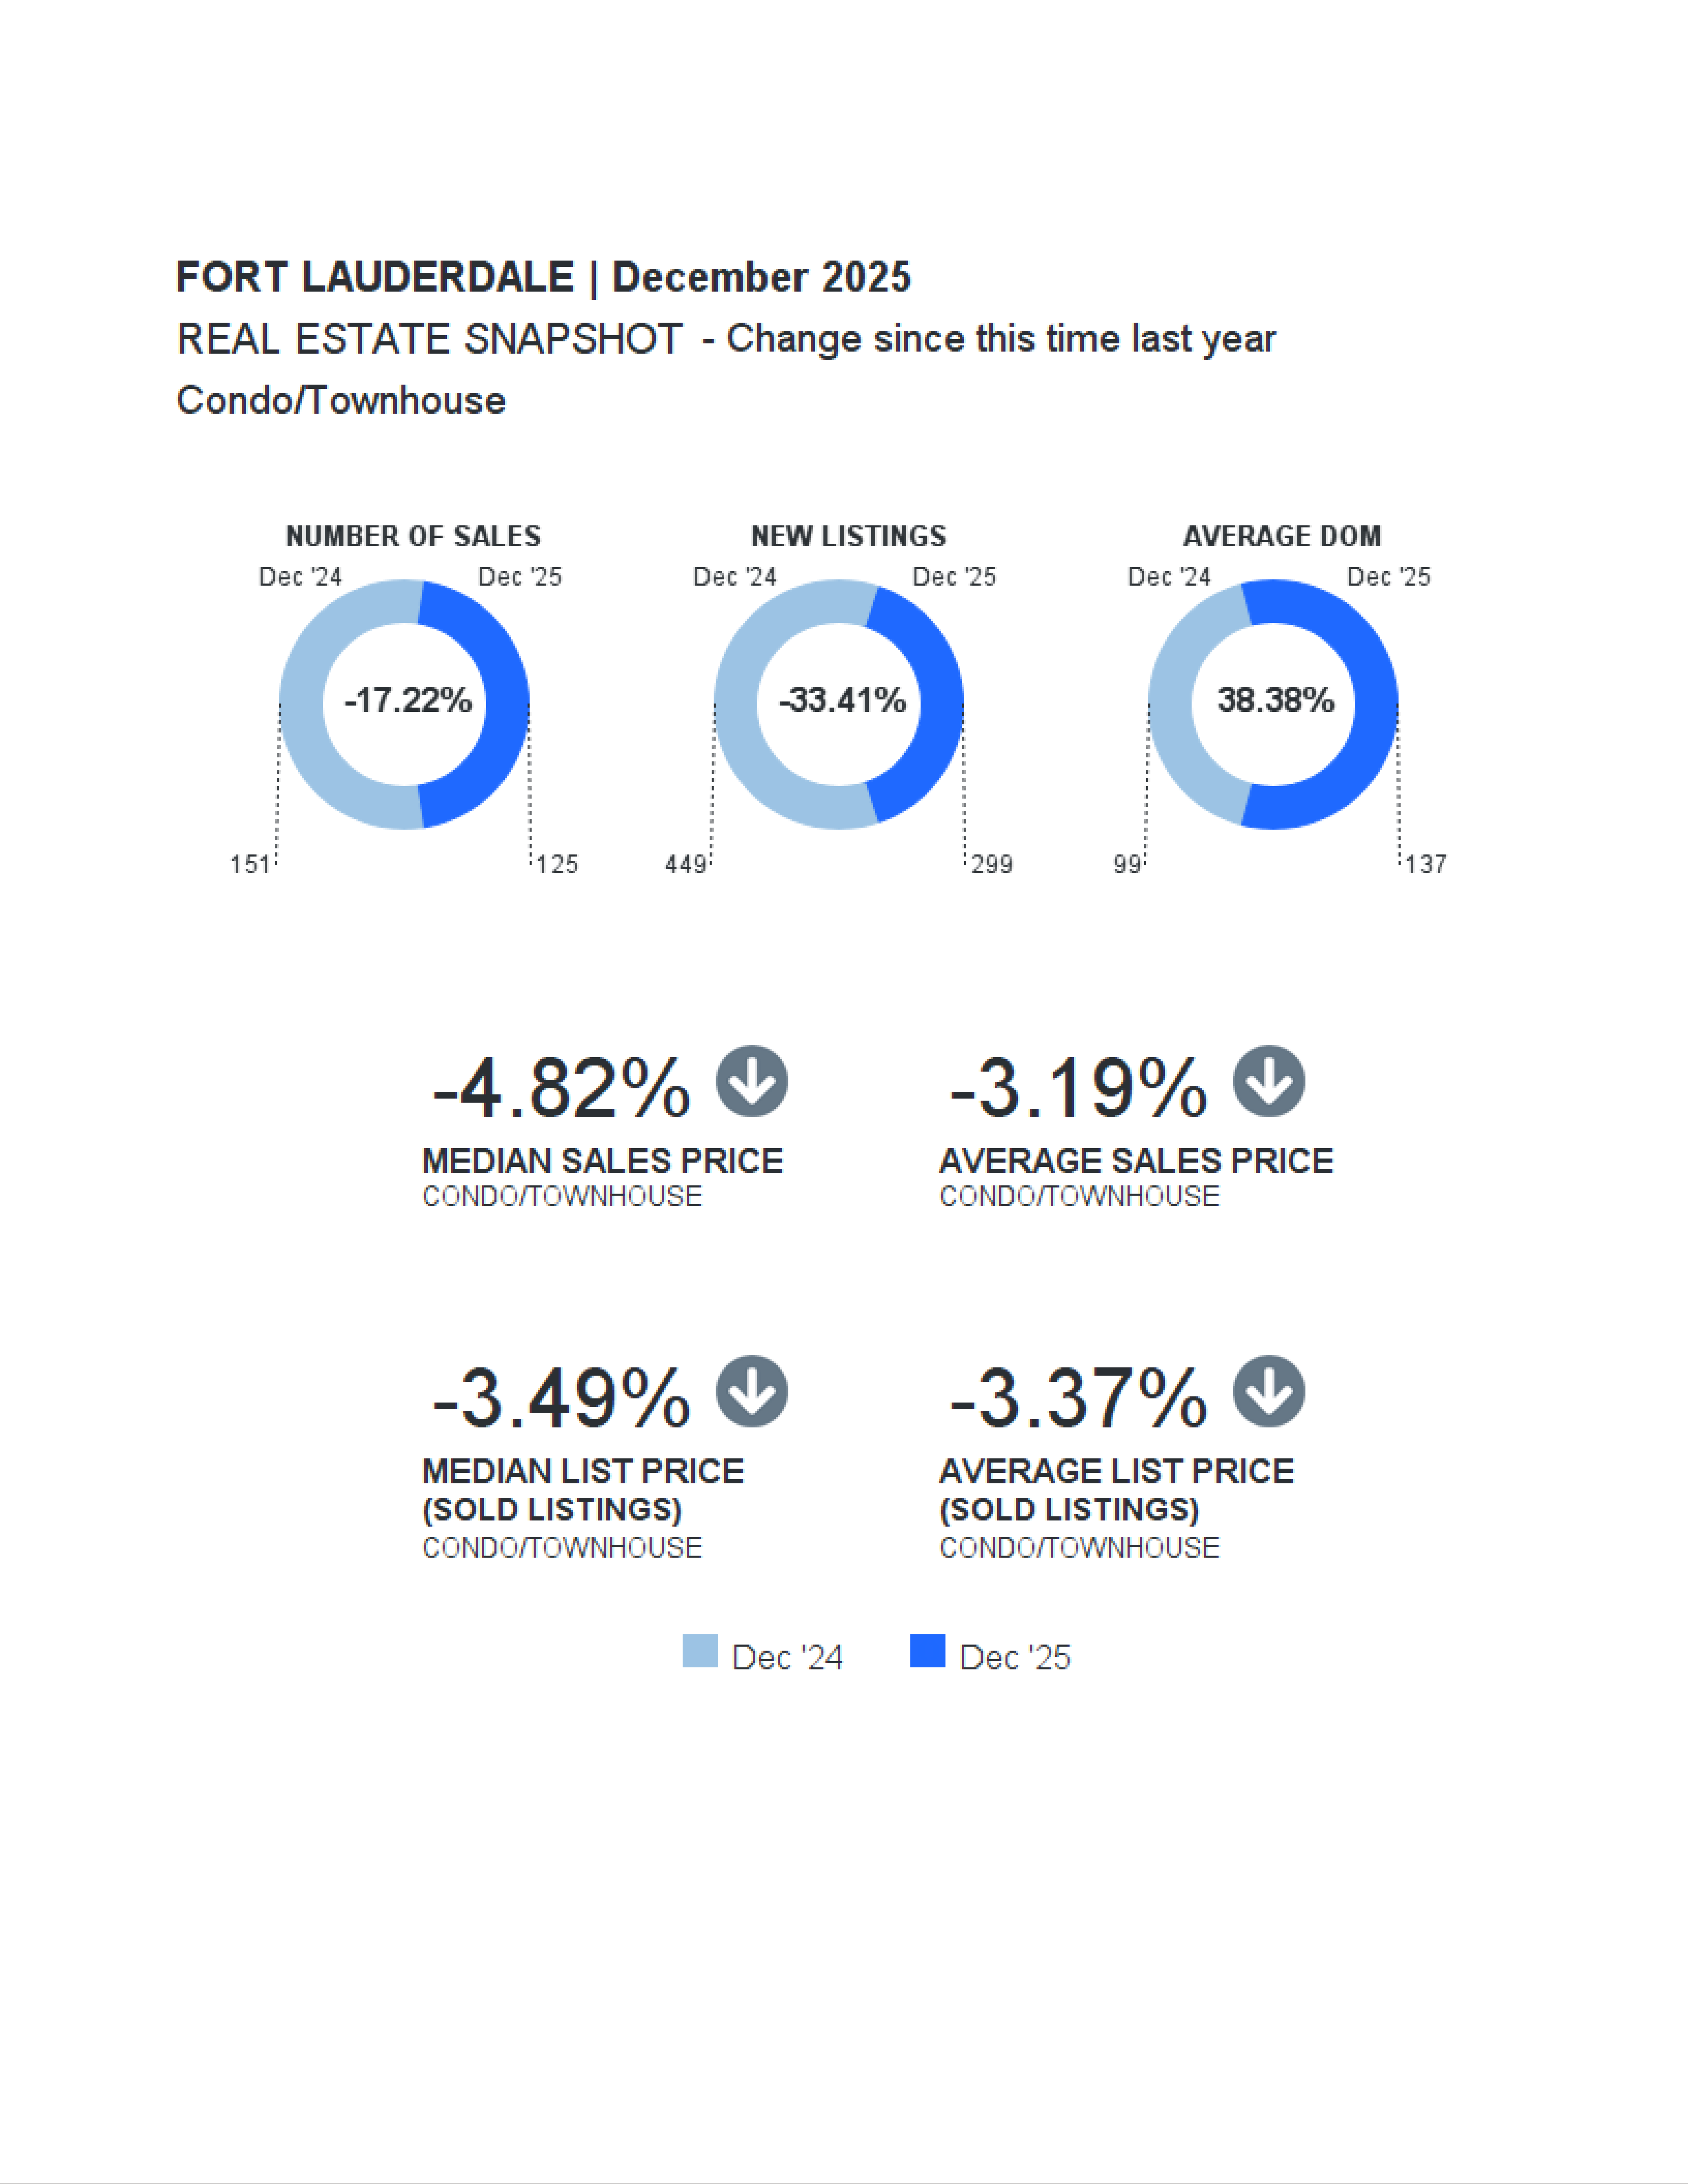
Fort Lauderdale December 2025 real estate statistics have been published.
Fort Lauderdale Area Reports
Single Family Homes
Condominium & Townhouses
Fort Lauderdale Real Estate Market Summary – December 2025
December 2025 | Single‑Family Homes & Condos/Townhomes
Overall Market Conditions
- The Fort Lauderdale market shows slower activity, higher prices, and longer selling times, especially for single‑family homes.
- Inventory remains elevated, meaning buyers have more choices and sellers face more competition.
Single‑Family Homes
Key Trends
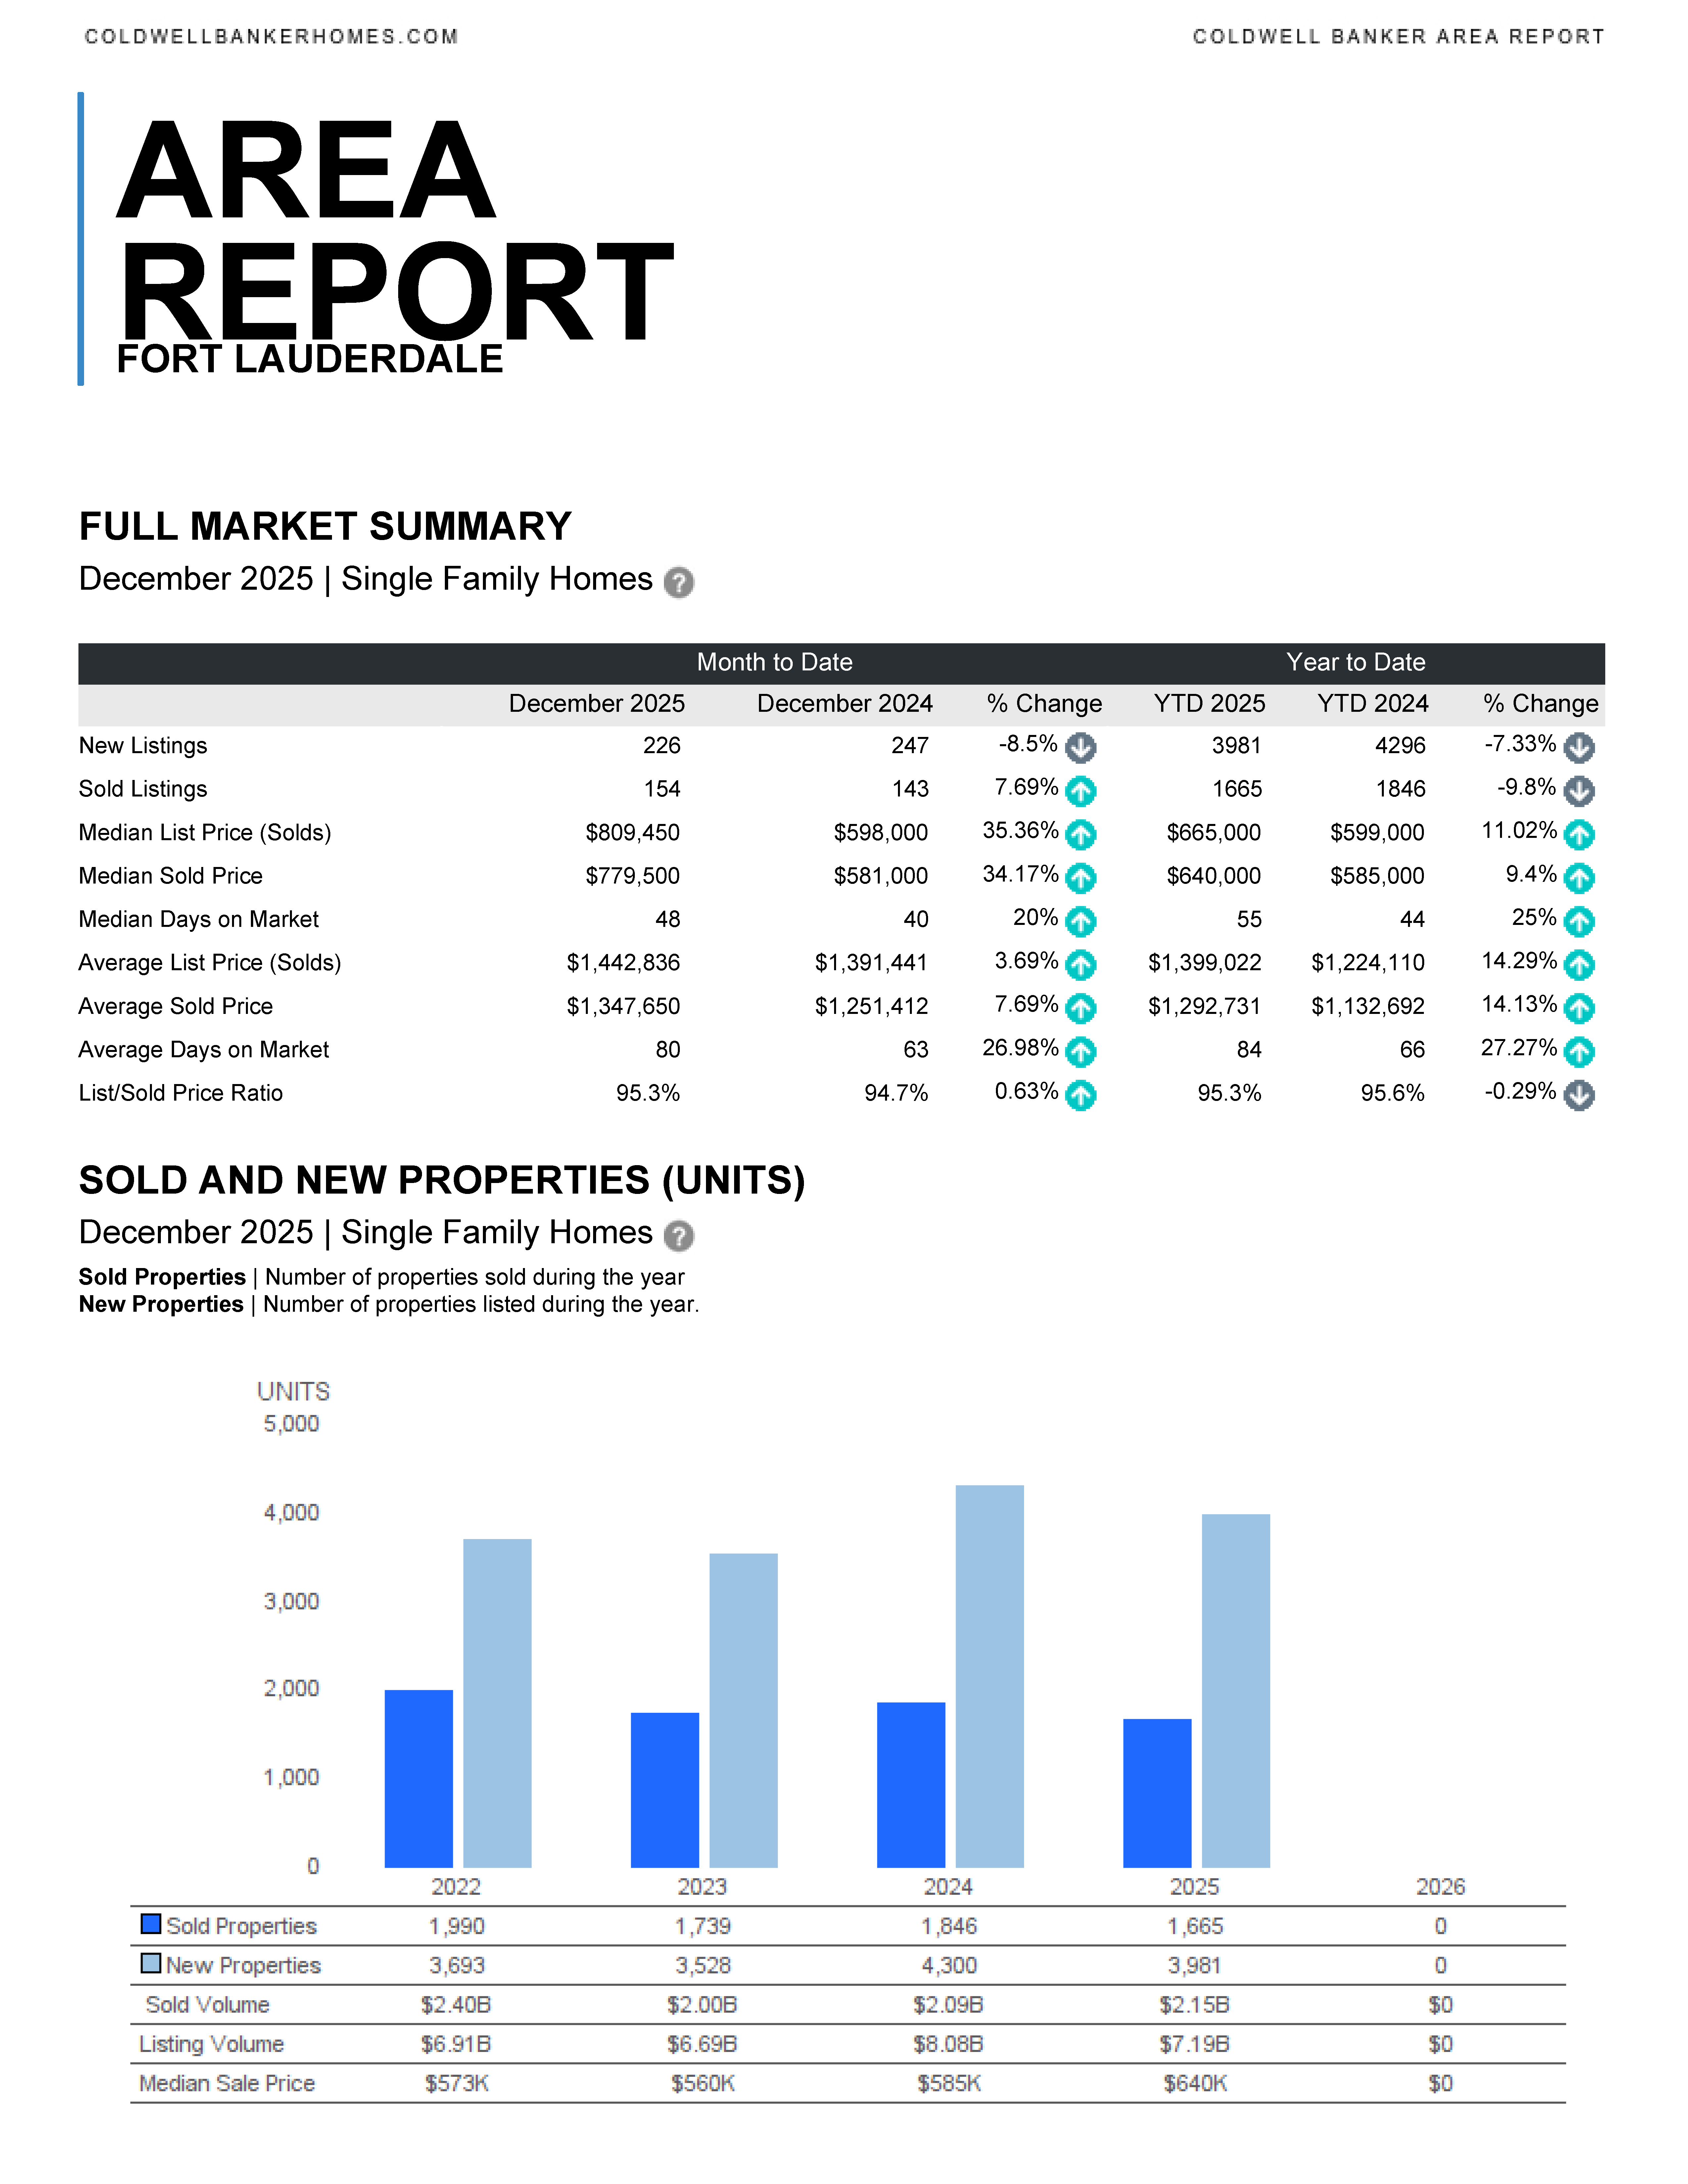
- Prices are up sharply year‑over‑year
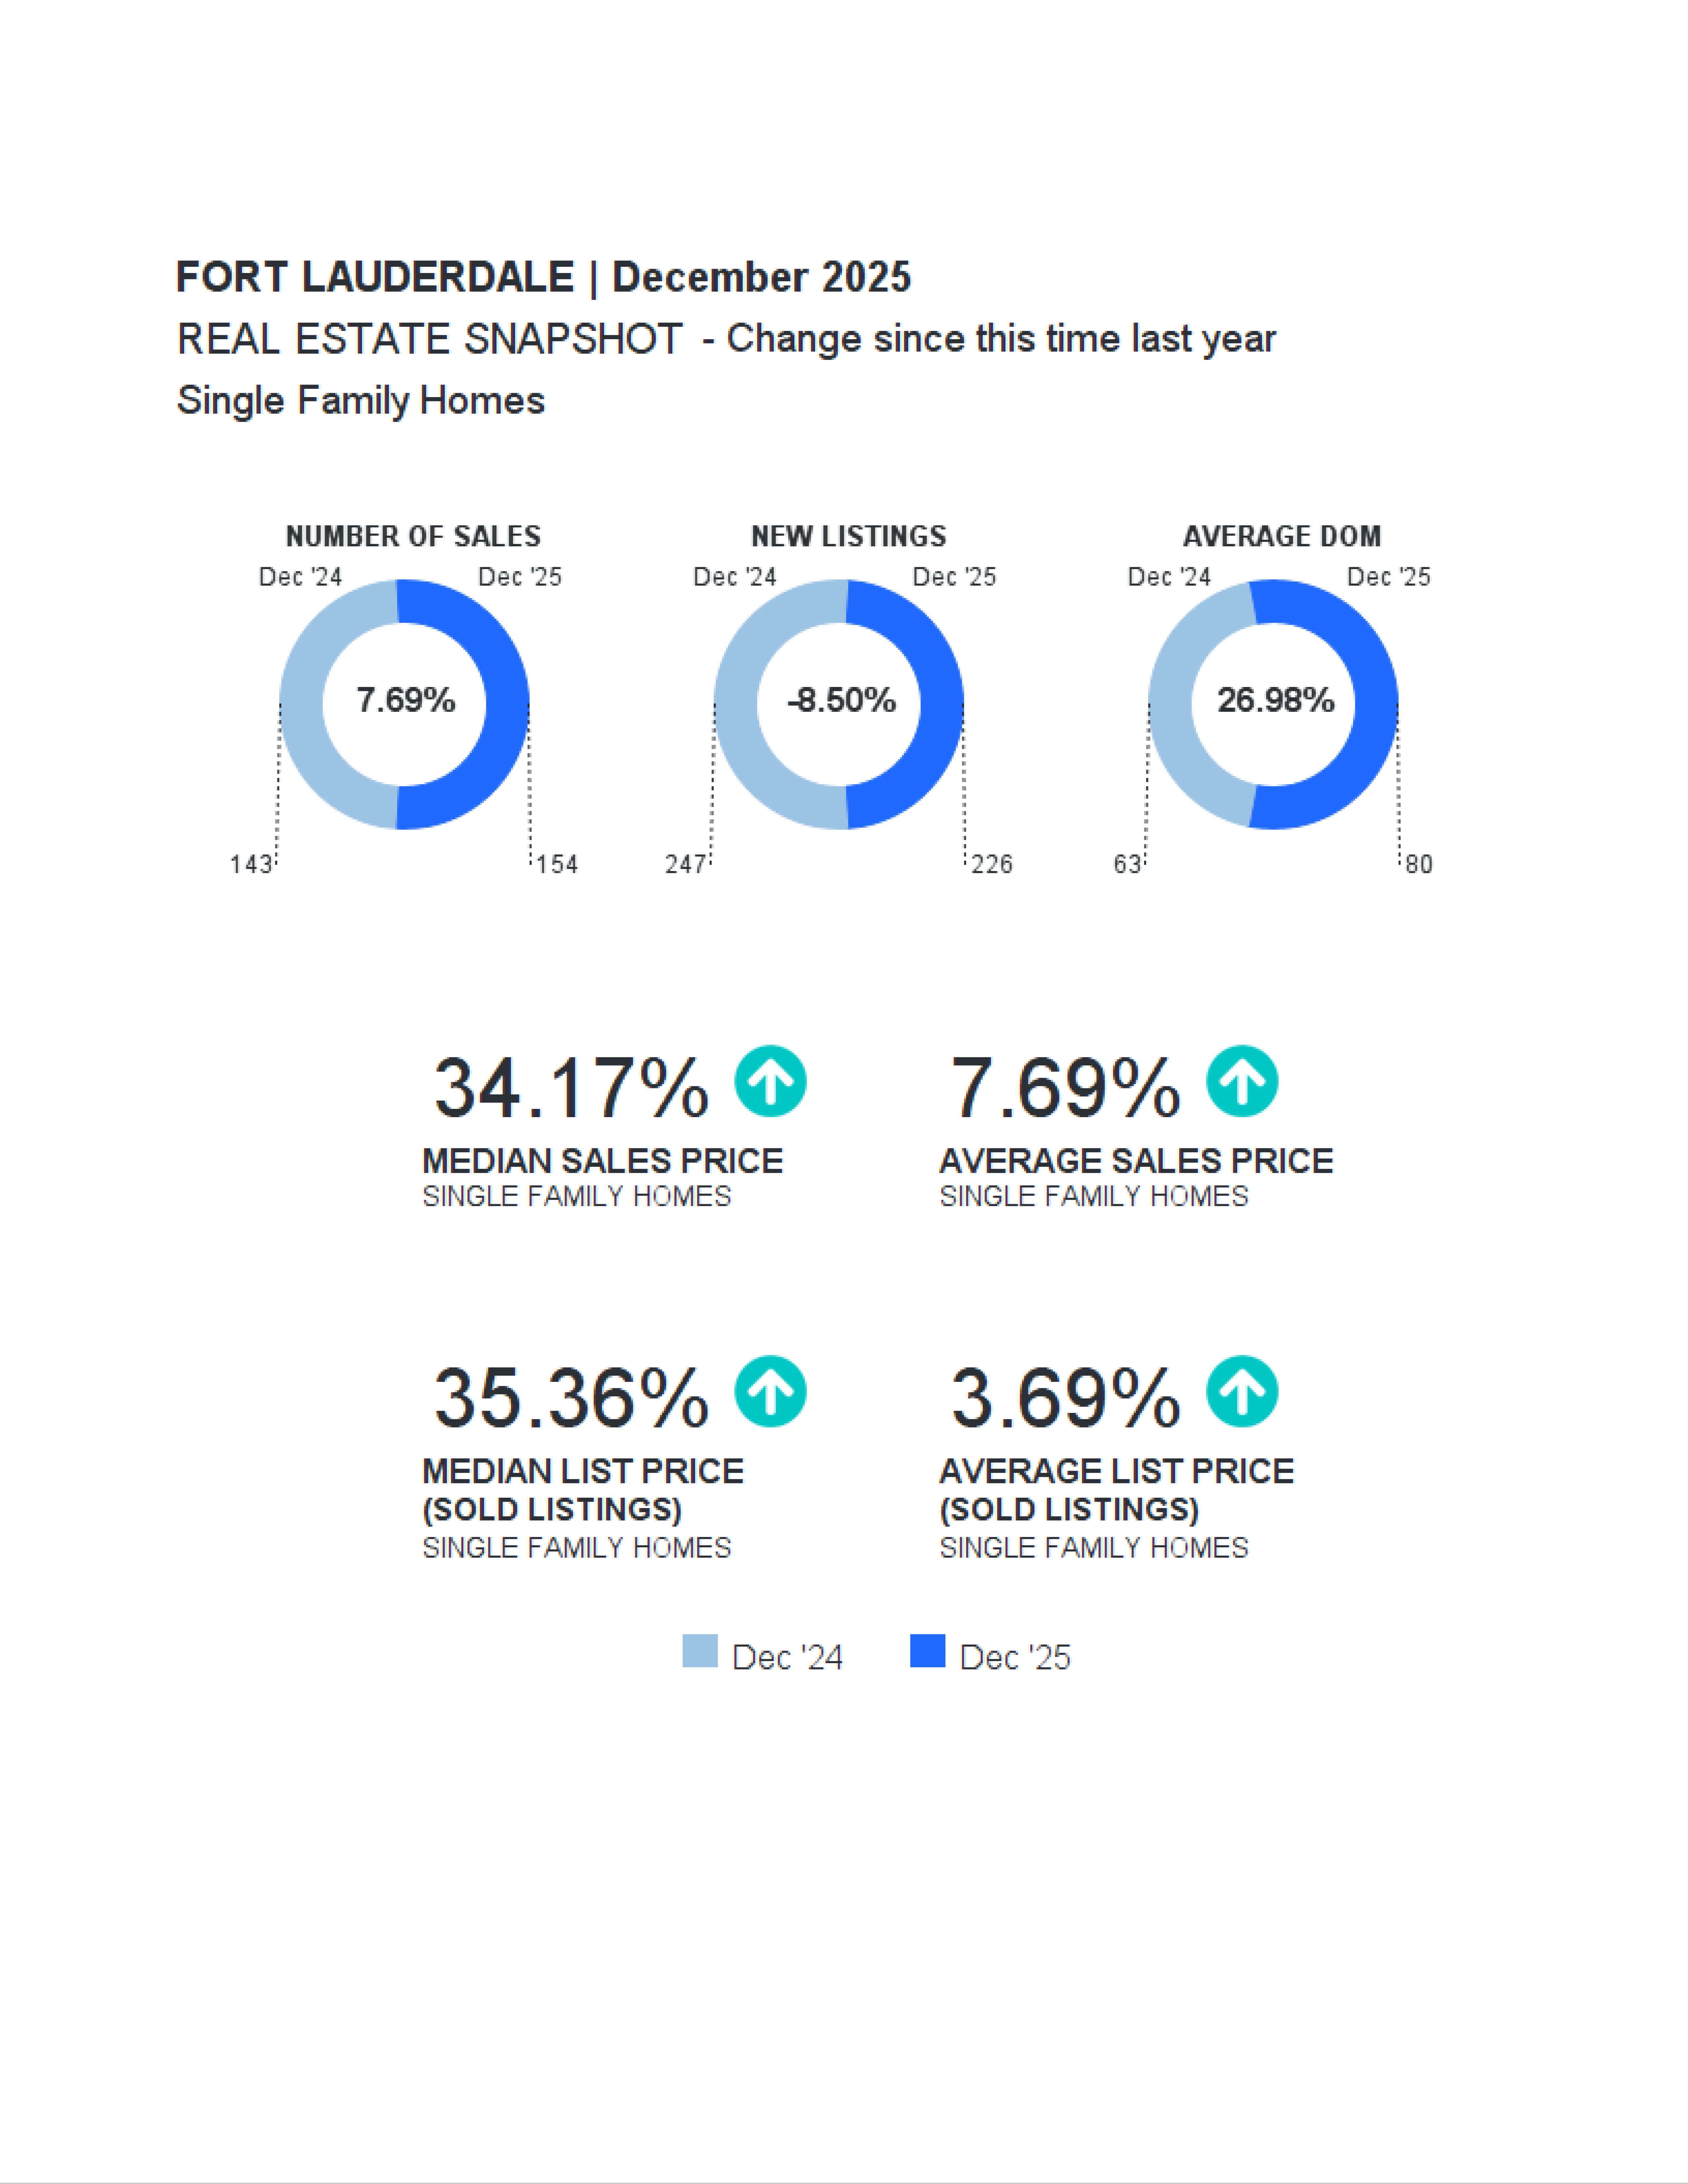
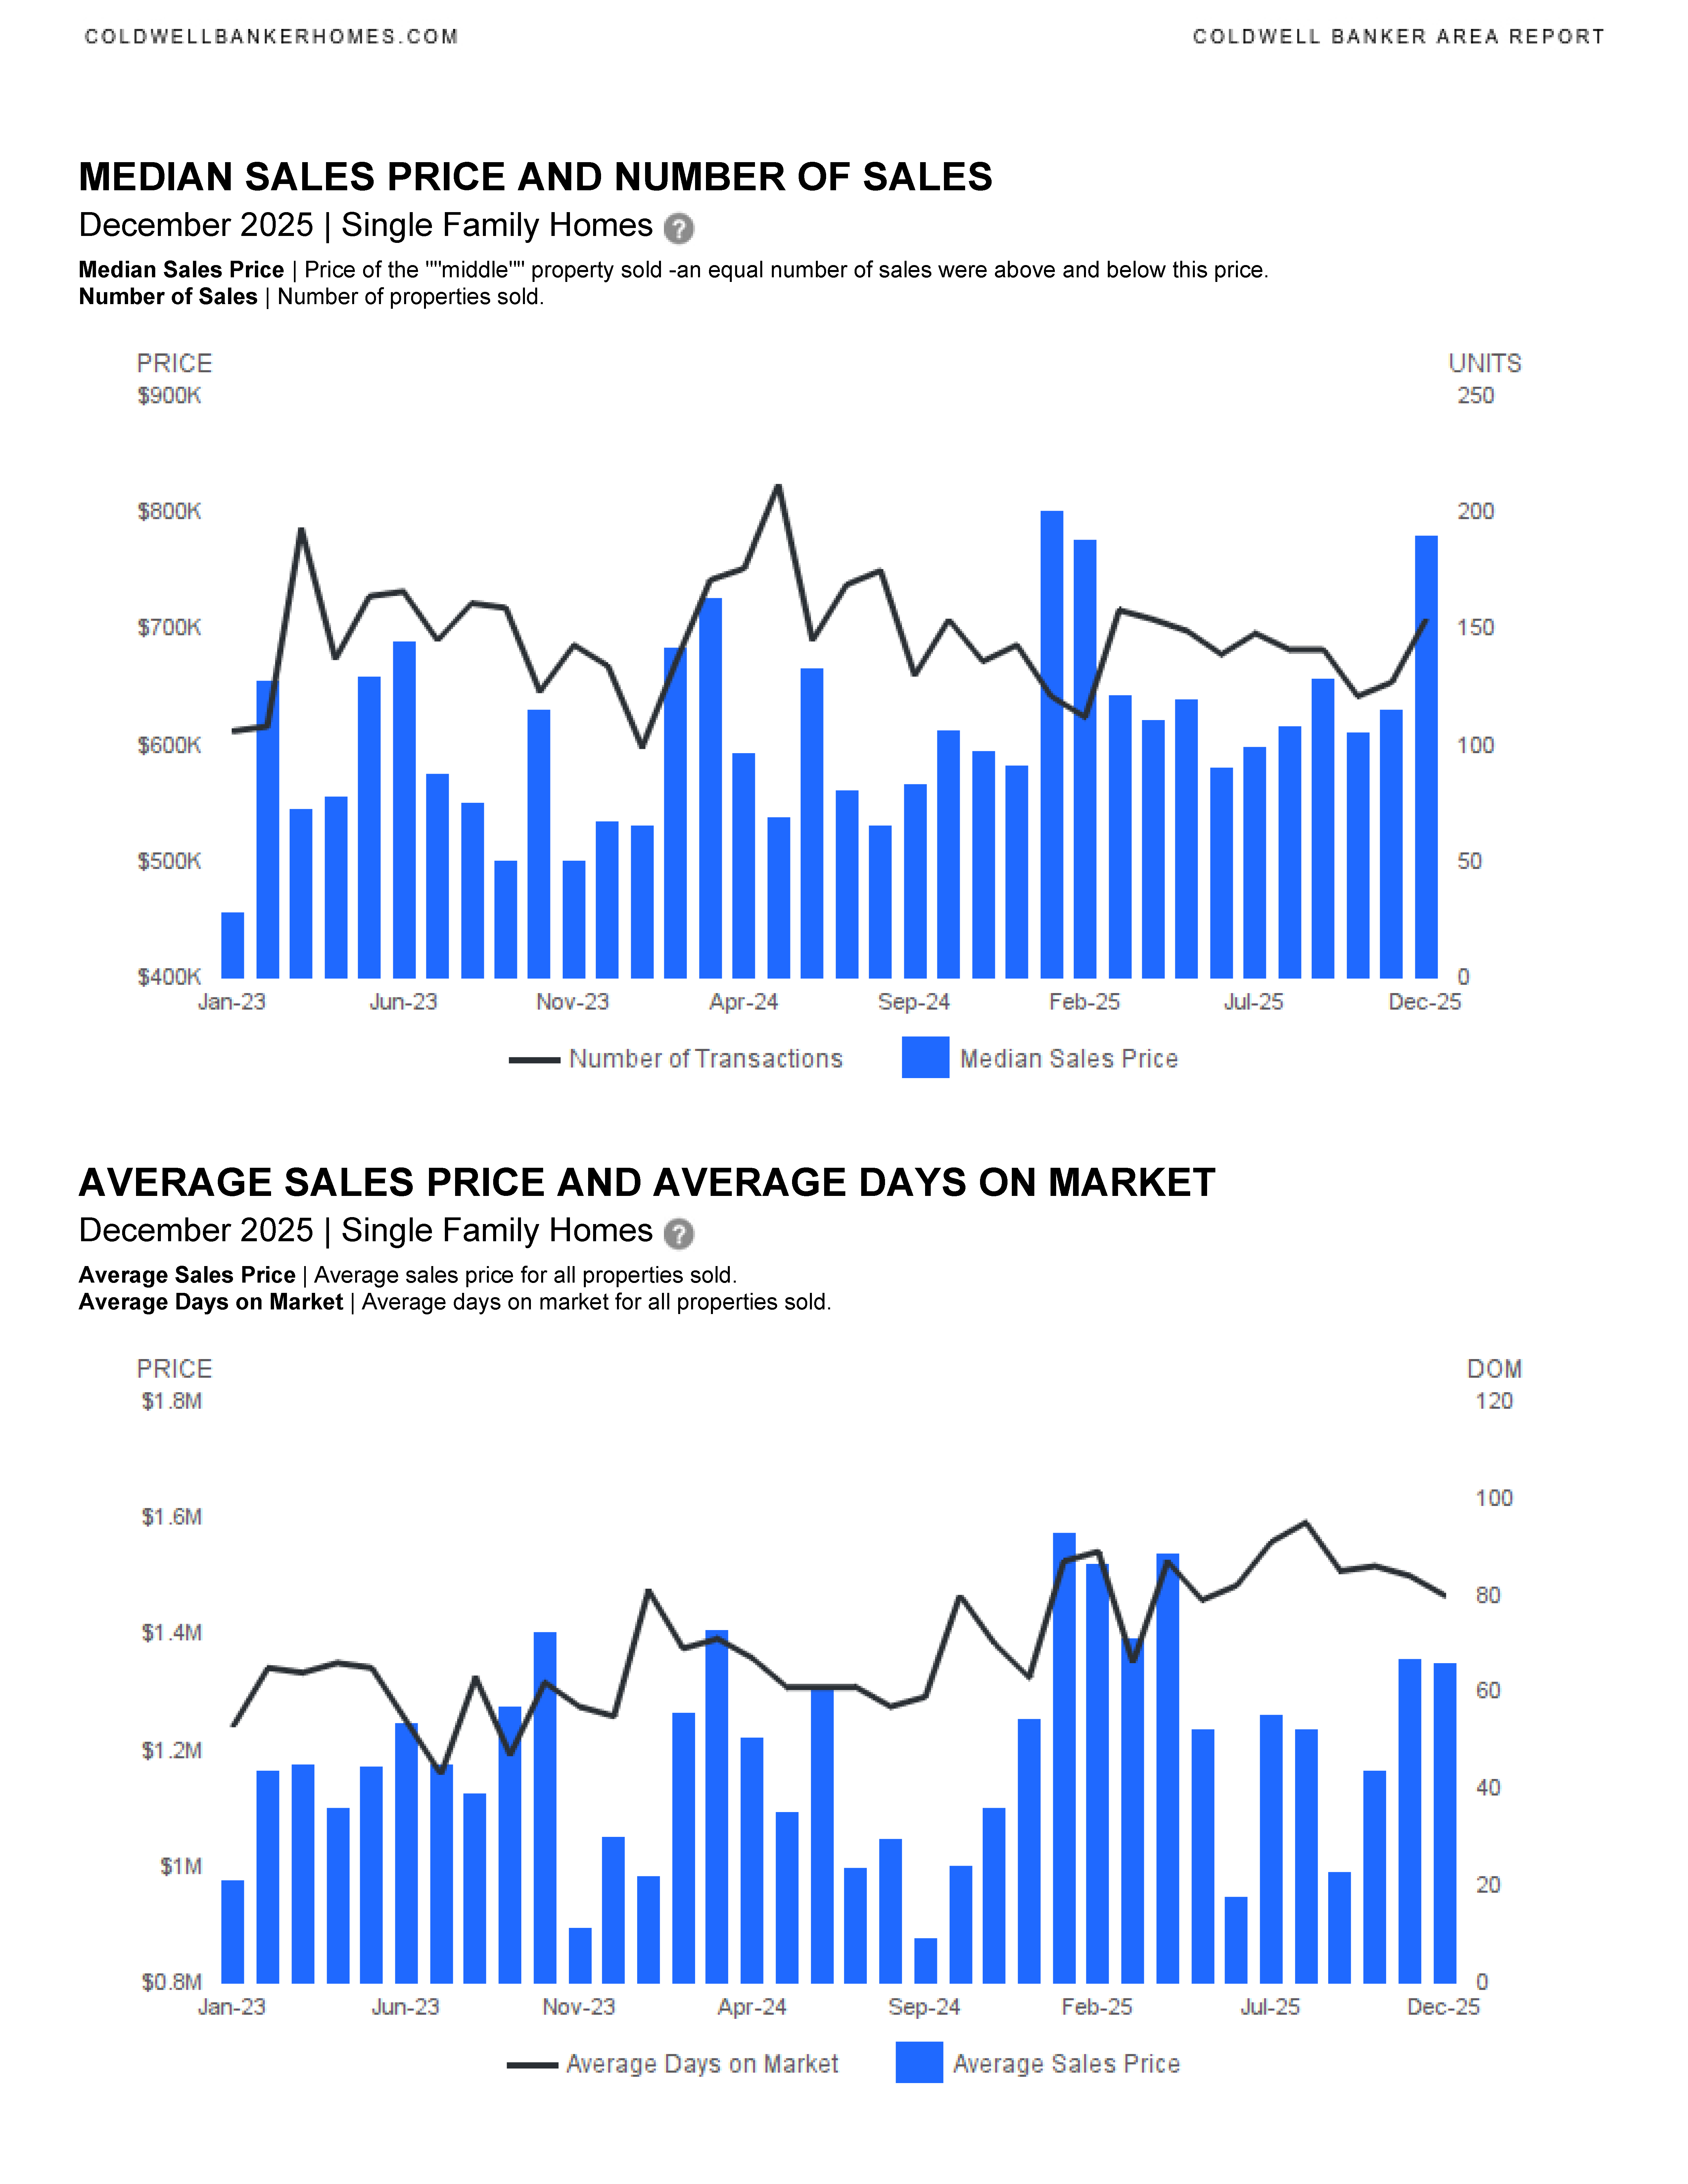
- Median Sold Price: $779,500 (+34% vs. Dec 2024)
- Year‑to‑Date Median Sold Price: $640,000 (+9.4%)
- Fewer homes are selling
- December sales: 154 homes (+7.7% vs. last year)
- Year‑to‑date sales: down nearly 10%
- Homes are taking longer to sell
- Median Days on Market: 48 days (up from 40)
- Average Days on Market (YTD): 84 days
- Sellers are close to asking price
- List‑to‑Sold Price Ratio: 95.3%
What It Means
- Strong pricing favors sellers, but longer market times mean homes must be priced competitively and show well.
- Buyers benefit from more negotiating power than in prior years.
Condo & Townhome Market
Key Trends
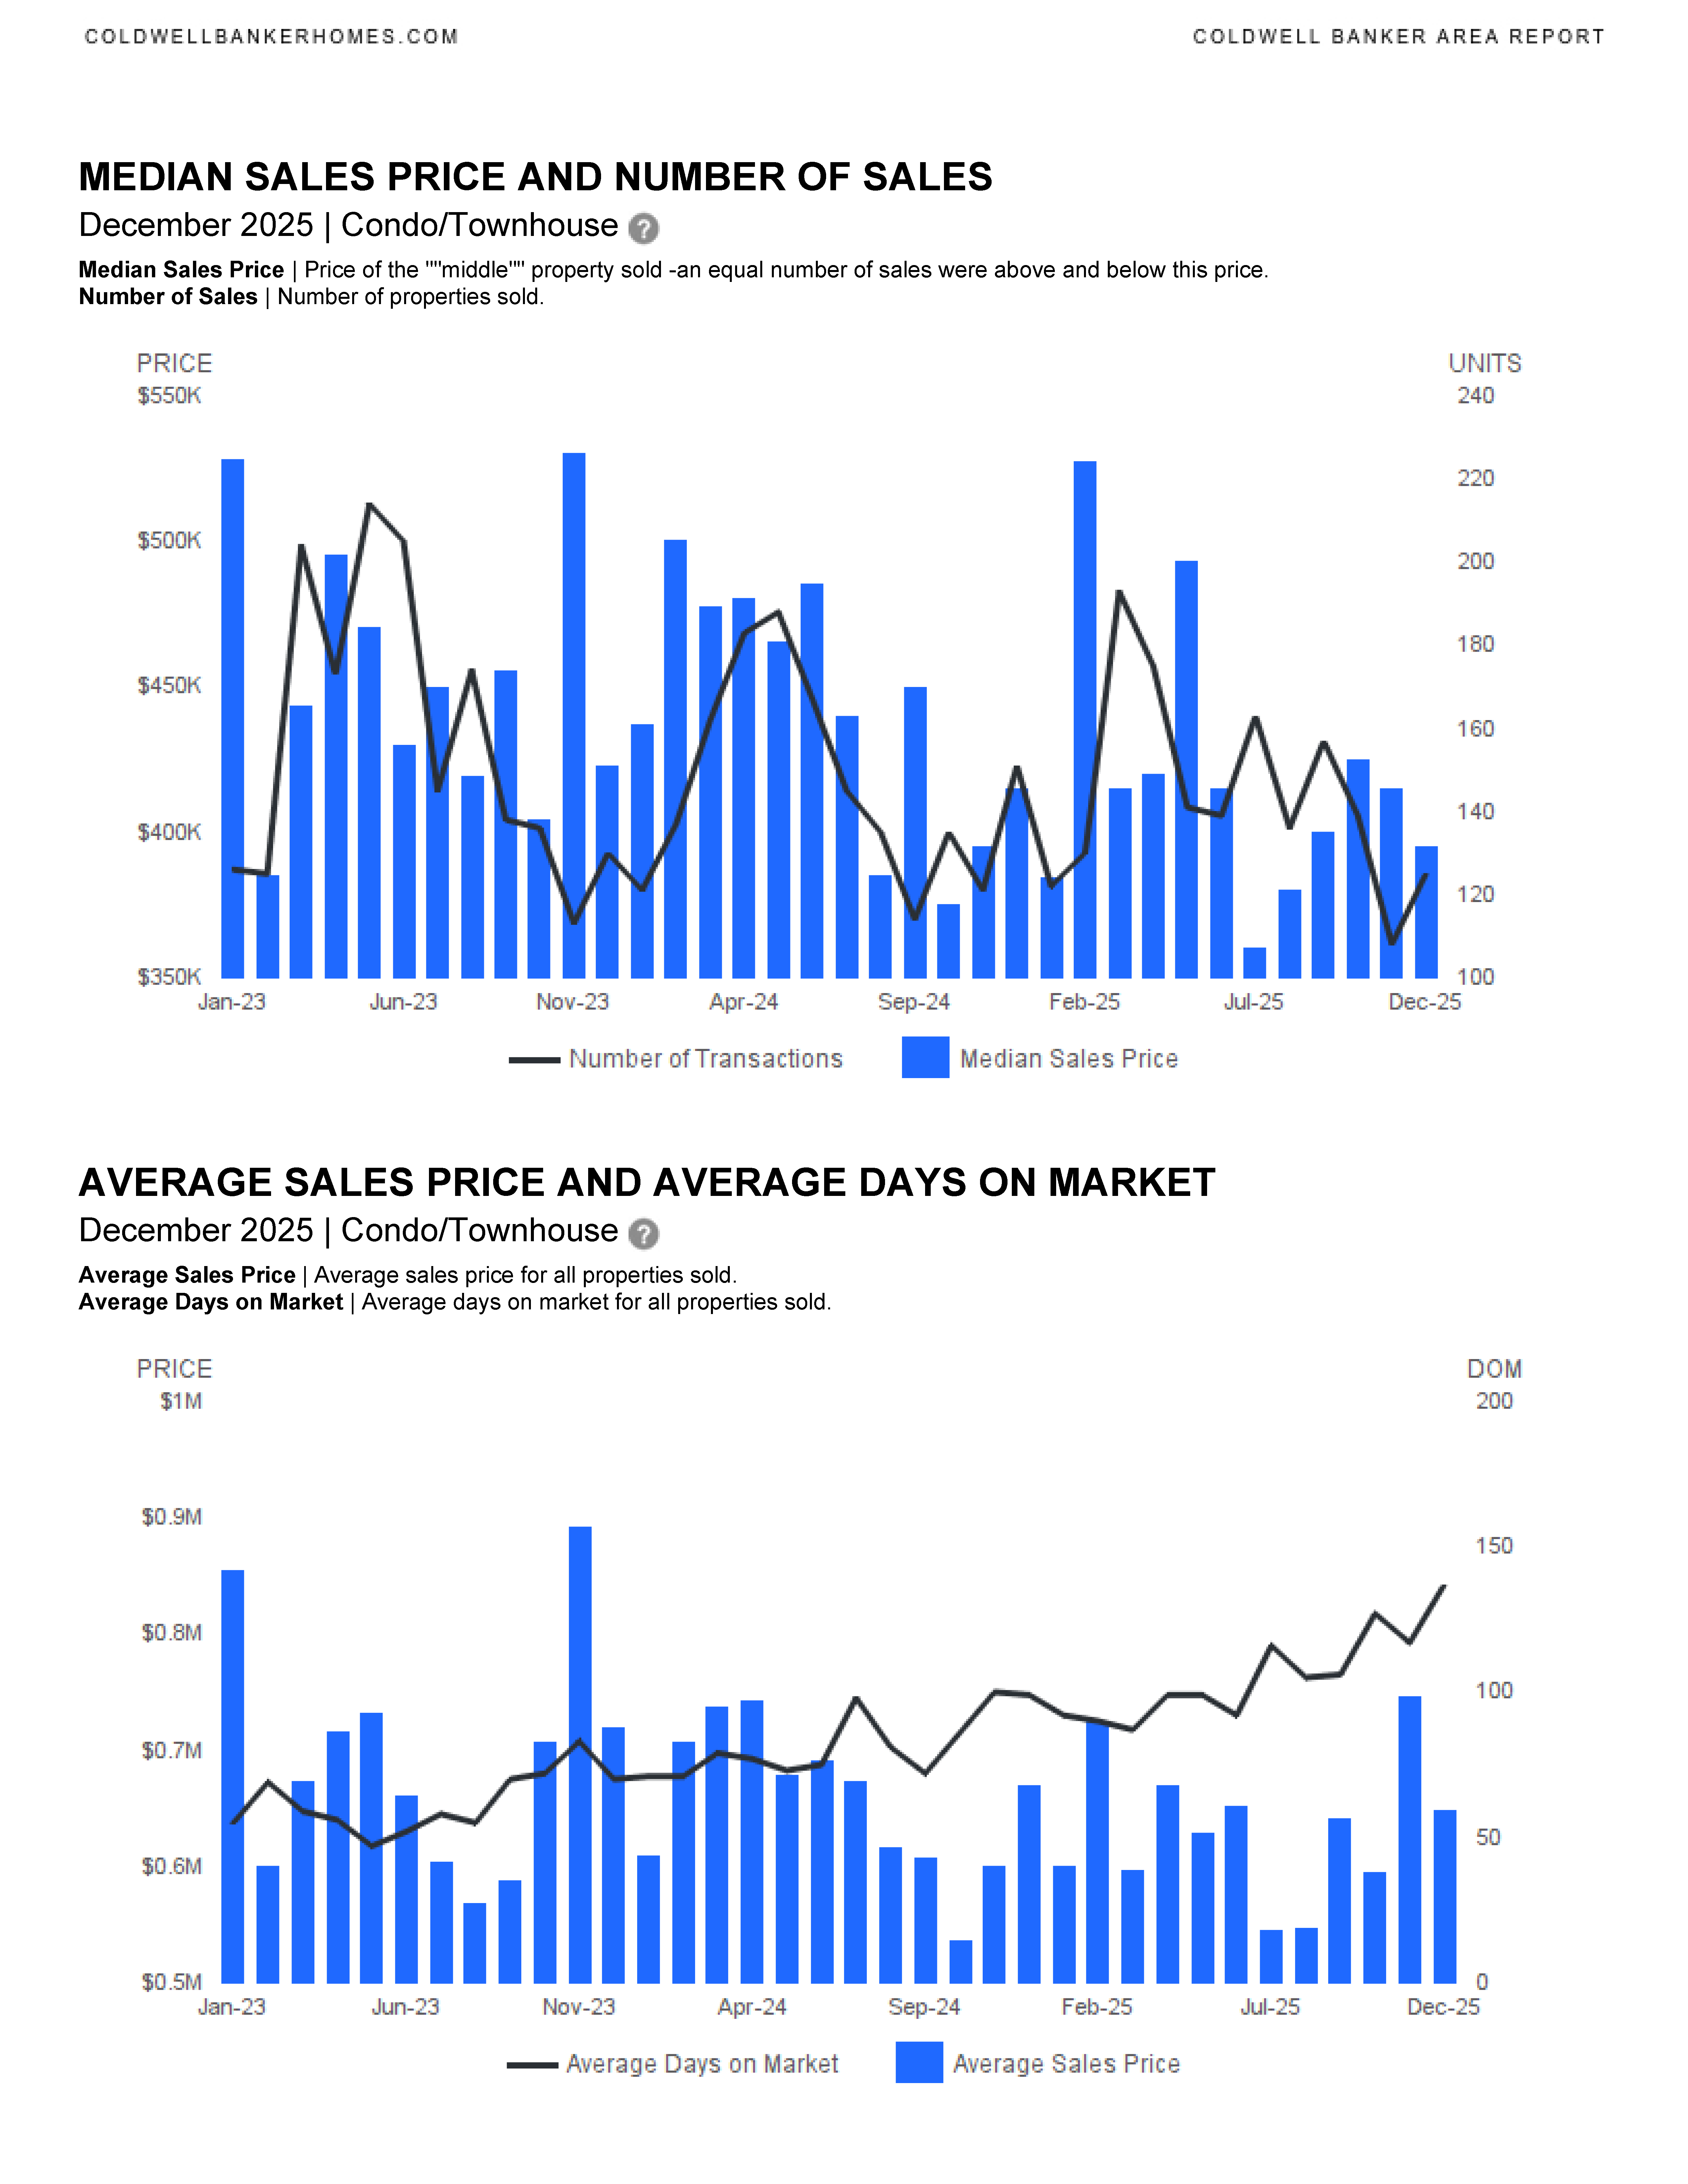
- Prices are declining
- Median Sold Price: $395,000 (–4.8% YoY)
- YTD Median Sold Price: $410,000 (–7.9%)
- Sales activity has slowed
- December sales: down 17%
- Year‑to‑date sales: slightly lower than 2024
- Significantly longer selling times
- Median Days on Market: 97 days (up from 64)
- Average Days on Market: 137 days
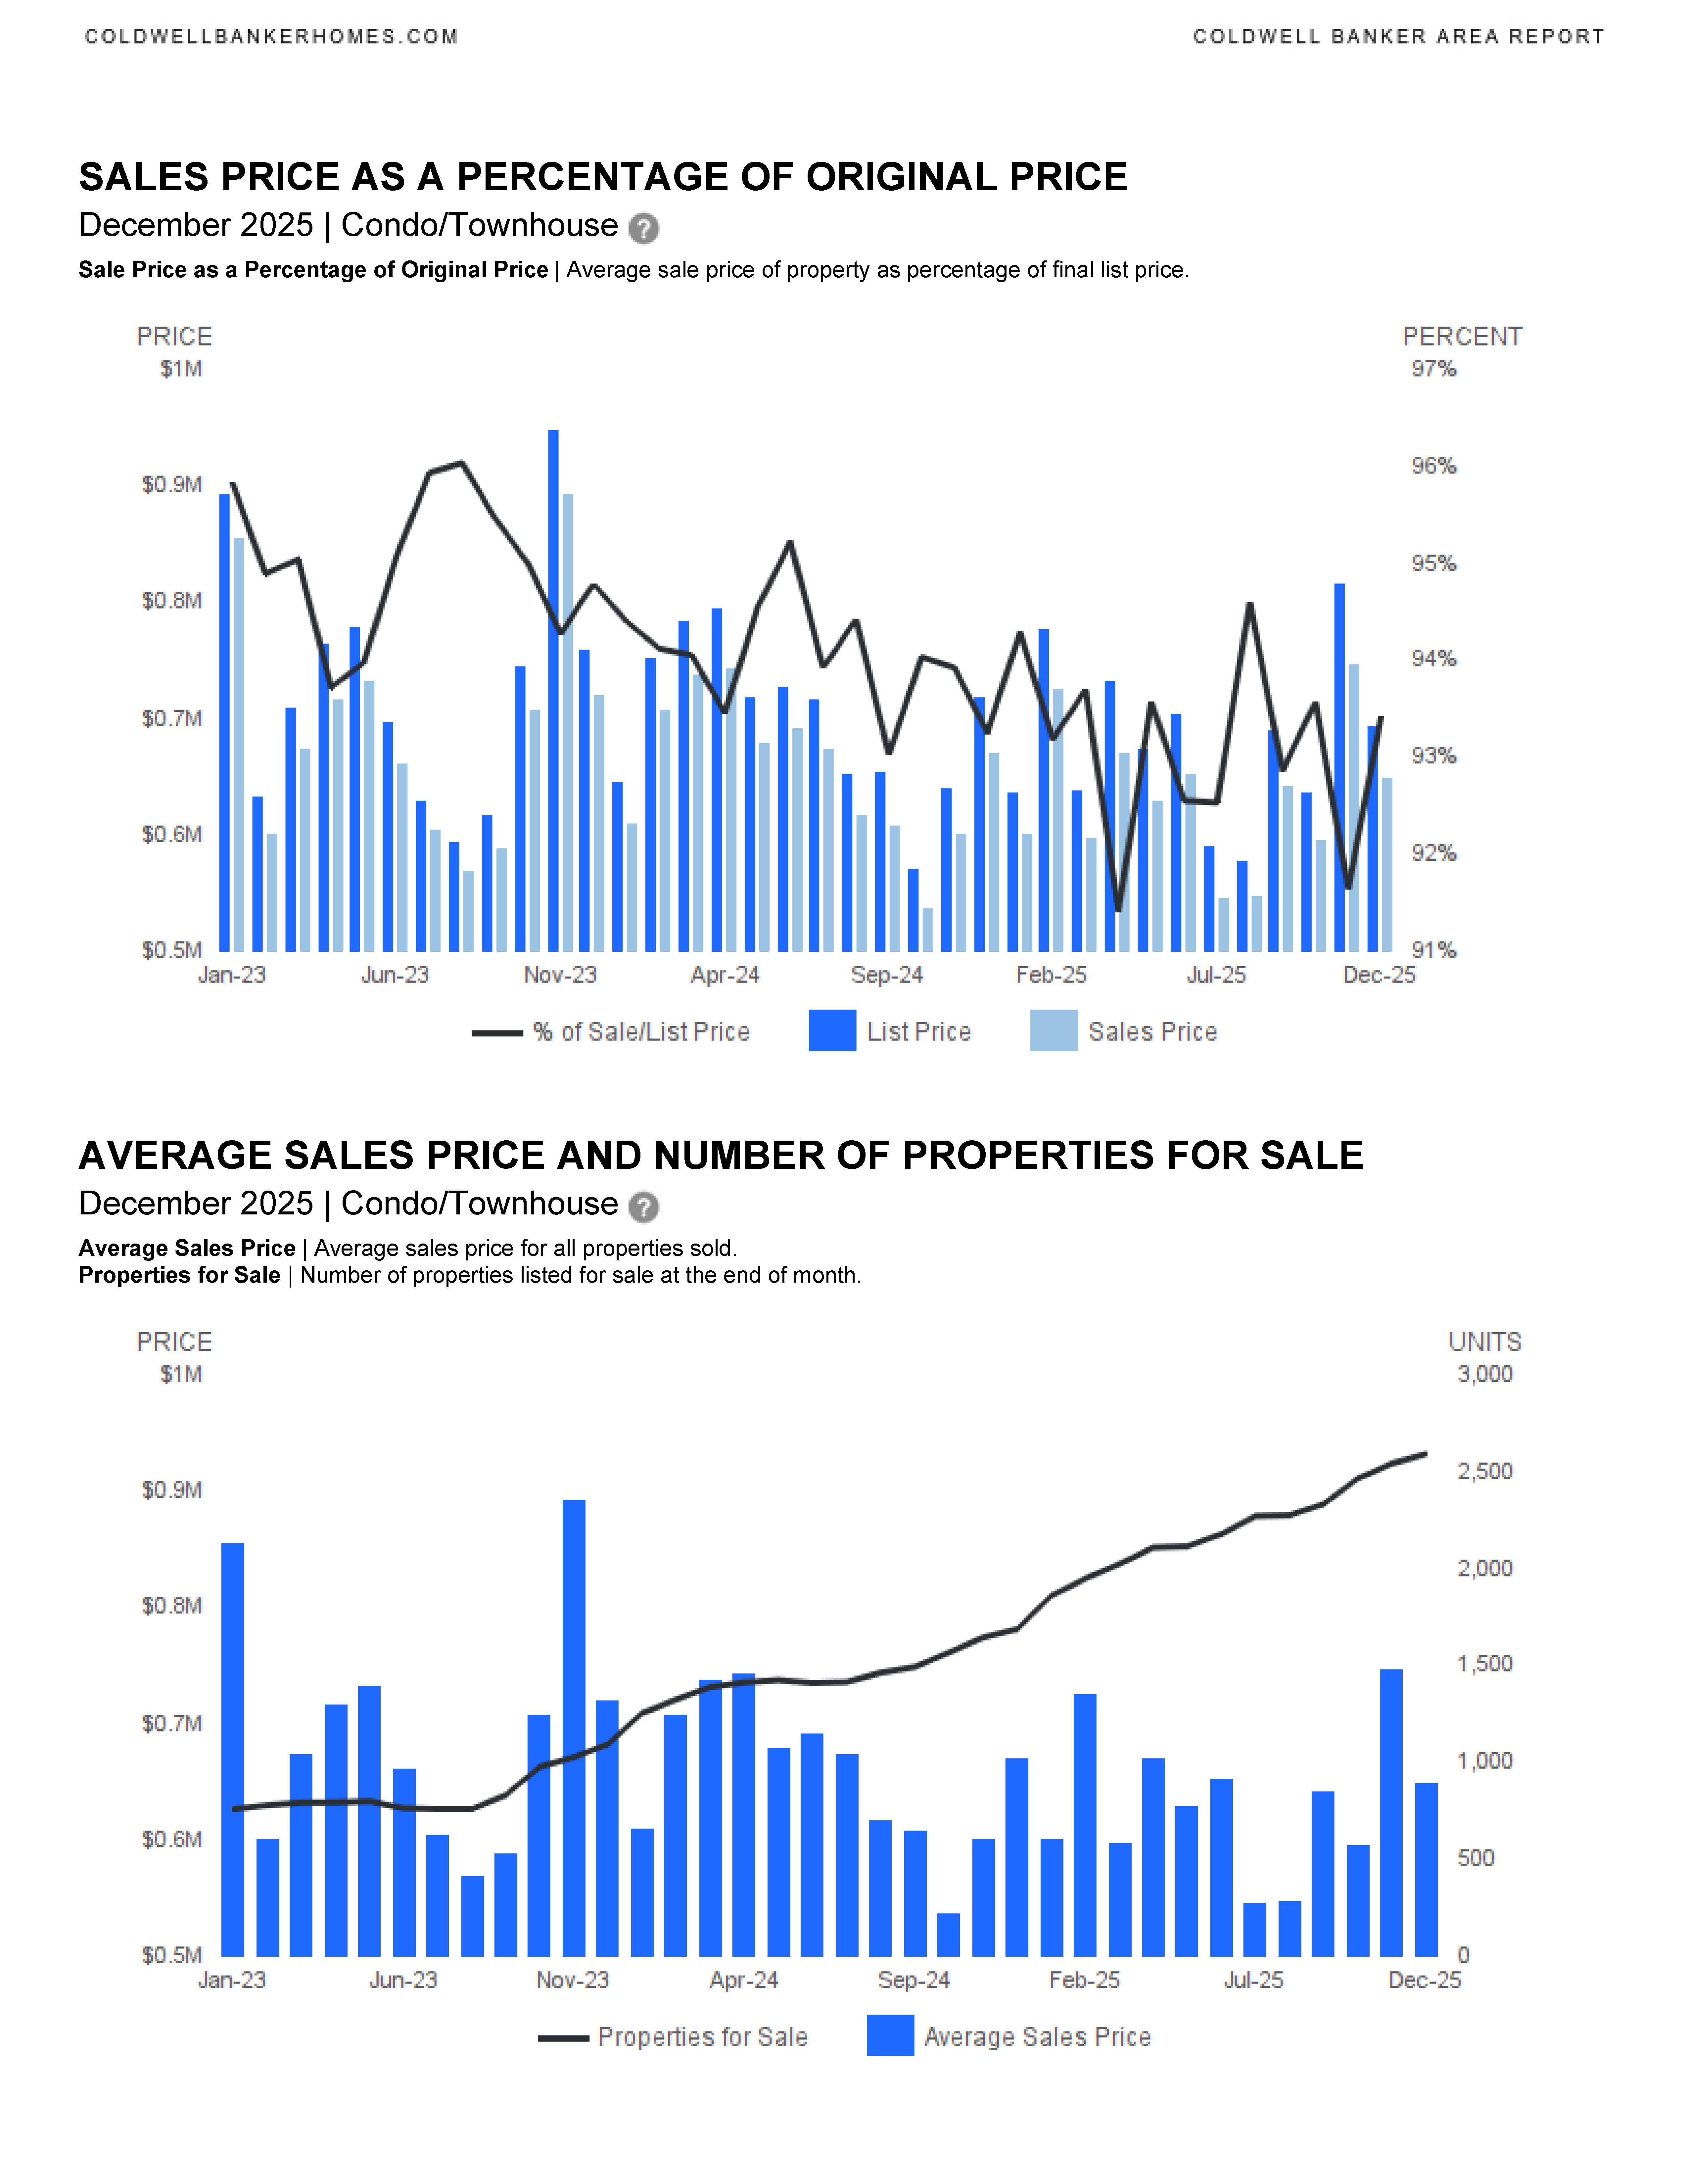
- More discounts are occurring
- List‑to‑Sold Price Ratio: 94.2%
What It Means
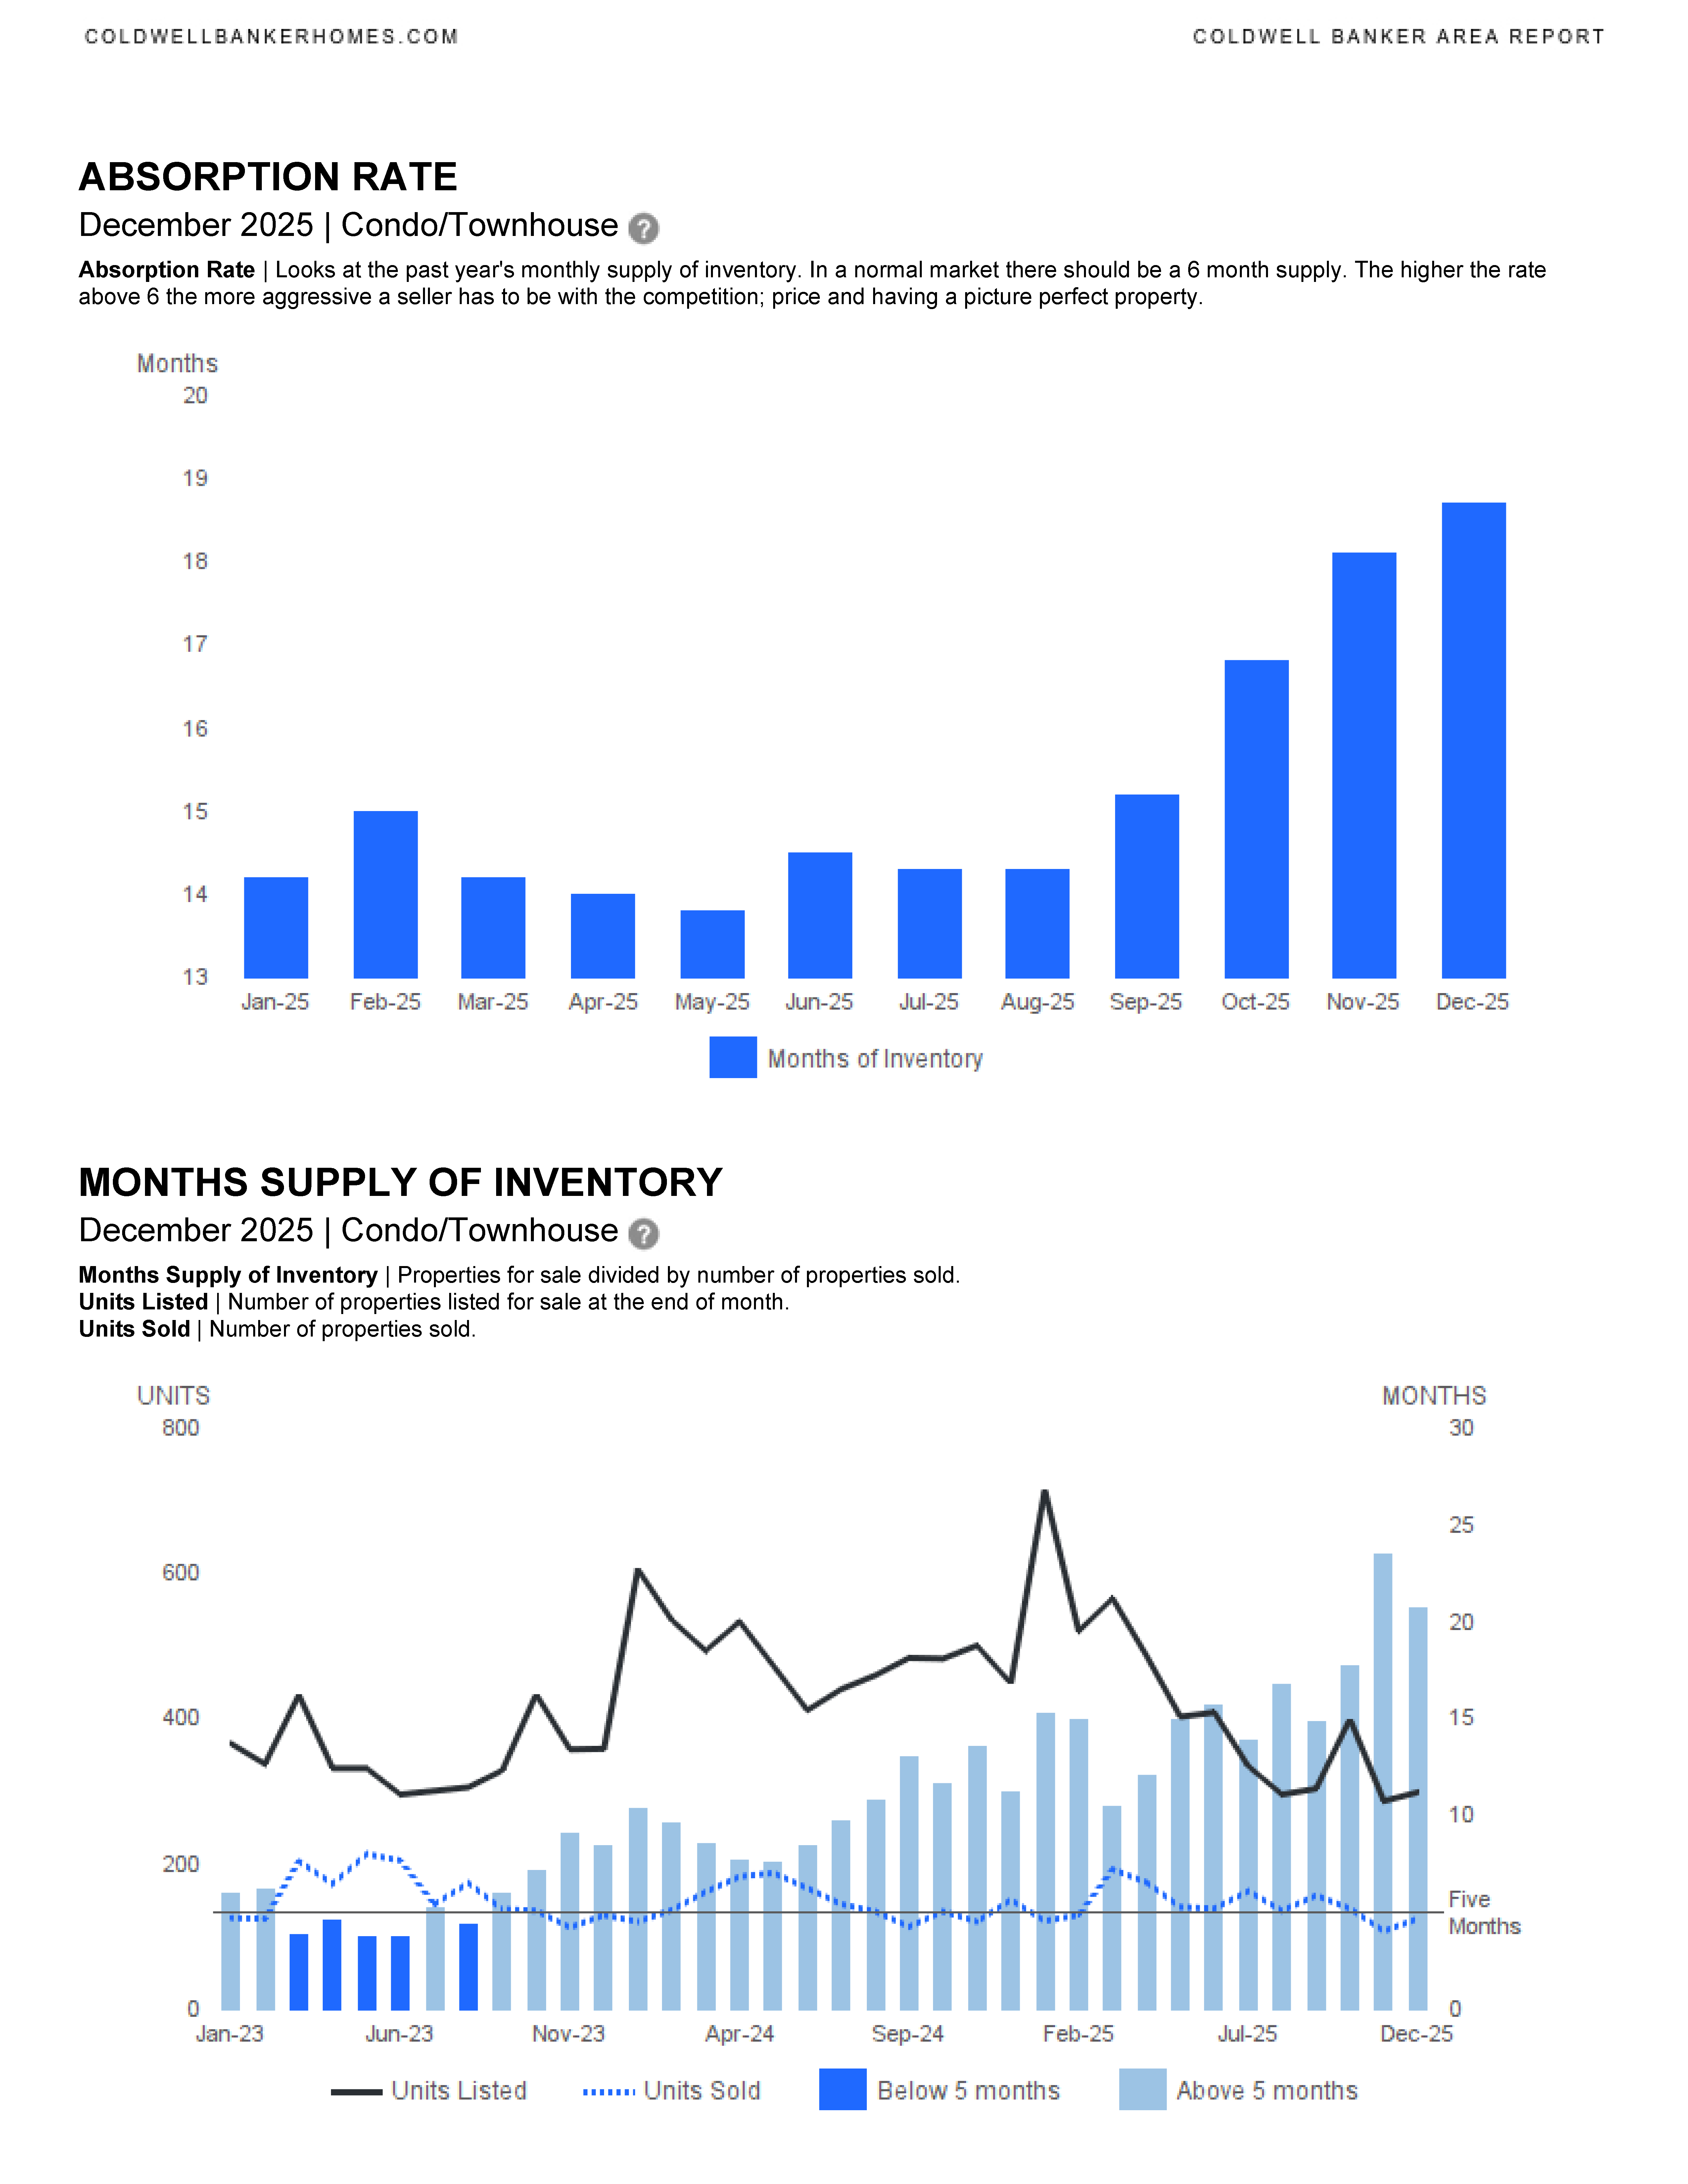
- The condo market is clearly buyer‑favored.
- Pricing pressure and longer timelines suggest strategic pricing is critical for sellers.
- Buyers may find value opportunities, especially compared to single‑family homes.
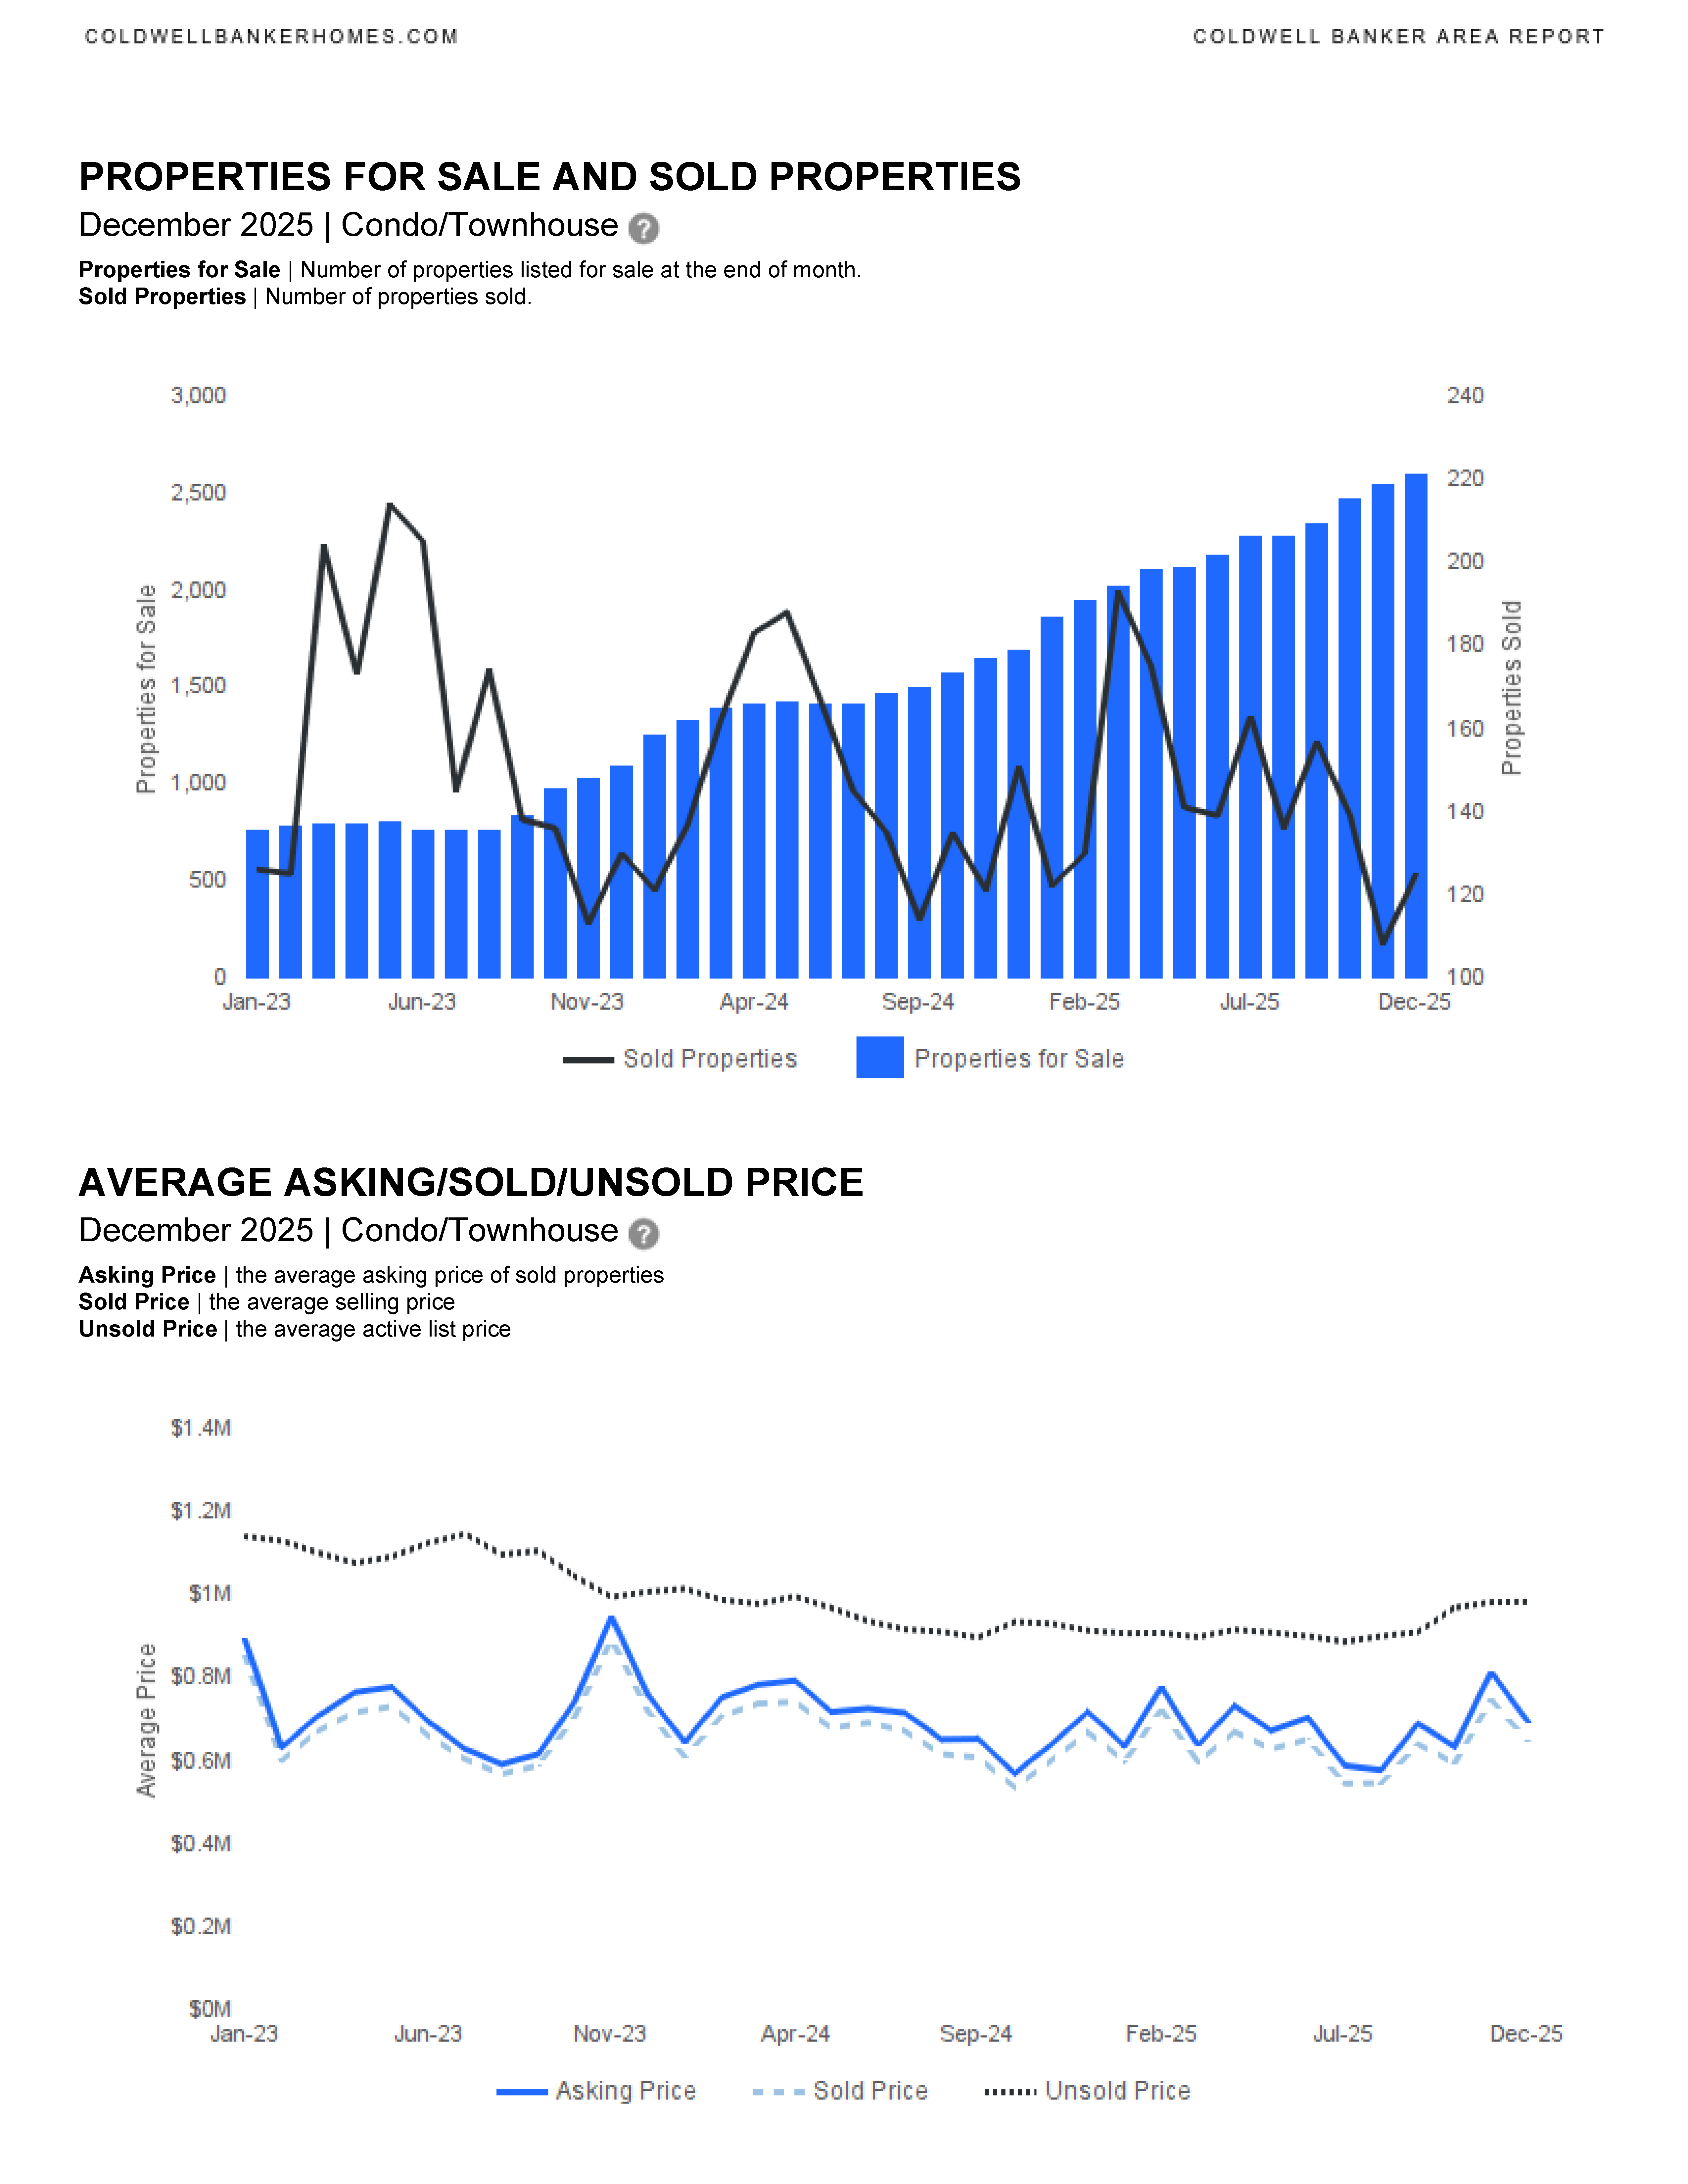
Inventory & Supply
- The market continues to reflect higher months of supply, especially for condos.
- A “balanced” market is typically around 6 months of supply—current levels indicate increased competition among sellers in many segments.
Bottom Line
- Single‑family homes: Prices are strong, but the pace has slowed. Sellers must stay competitive; buyers have more leverage than in recent years.
- Condos/townhomes: Softer prices, longer selling times, and fewer sales point to a clear buyer’s market.
- Overall: Fort Lauderdale has moved away from the ultra‑competitive pandemic era and into a more normalized, negotiation‑friendly market.
We are in a new housing market in SE Florida. This is the time to work with an experienced and knowledgeable real estate professional. Please contact me if you would like to be sent updated market reports for YOUR specific neighborhood, Fort Lauderdale, or another SE Florida city. We can discuss the market, current trends and how we can work together to accomplish your real estate goals. I am here to help.
CONTACT ANNETTE
Let’s start working together!
Annette Dammeyer, REALTOR®, ABR®, AHWD®
Coldwell Banker Realty
901 E Las Olas Blvd STE 101, Fort Lauderdale, FL 33301
808.747.3686
SL 3535792
January 2026 ~ AI Real Estate Scams, New Home Trends and More!
January 2026 NewsletterWelcome to Your January 2026 Real Estate & Lifestyle Update!
We are about to celebrate the “Happy New Year”! As we step into 2026, I’m excited to bring you insights on AI scams in real estate, trends, and tips to help you make informed decisions—whether you’re buying, selling, renting, or simply looking to refresh your home. Here’s what you’ll find in this month’s newsletter: Your home is more than a place—it’s an investment and a lifestyle. Let’s make 2026 a fantastic year! Warm wishes for health and prosperity in the new year, |
|||||||||||
|
National Stories
|
|||||||||||
Real Estate Updates | Area Reports | November 2025
|

Thank you for joining me for this January 2026 Newsletter!
As we step into a brand-new year, remember that your home is more than four walls—it’s where your dreams take shape and your future grows. Whether you’re planning to buy, sell, invest, or simply refresh your space, I’m here to guide you every step of the way.
If you have questions, need advice, or just want to chat about your goals for 2026, reach out anytime—I’d love to help make this your best year yet!
Here’s to new beginnings, exciting opportunities, and a year filled with success and joy.
CONTACT ANNETTE
Let’s start working together!
Annette Dammeyer, REALTOR®, ABR®, AHWD®
Coldwell Banker Realty
901 E Las Olas Blvd STE 101, Fort Lauderdale, FL 33301
808.747.3686
SL 3535792
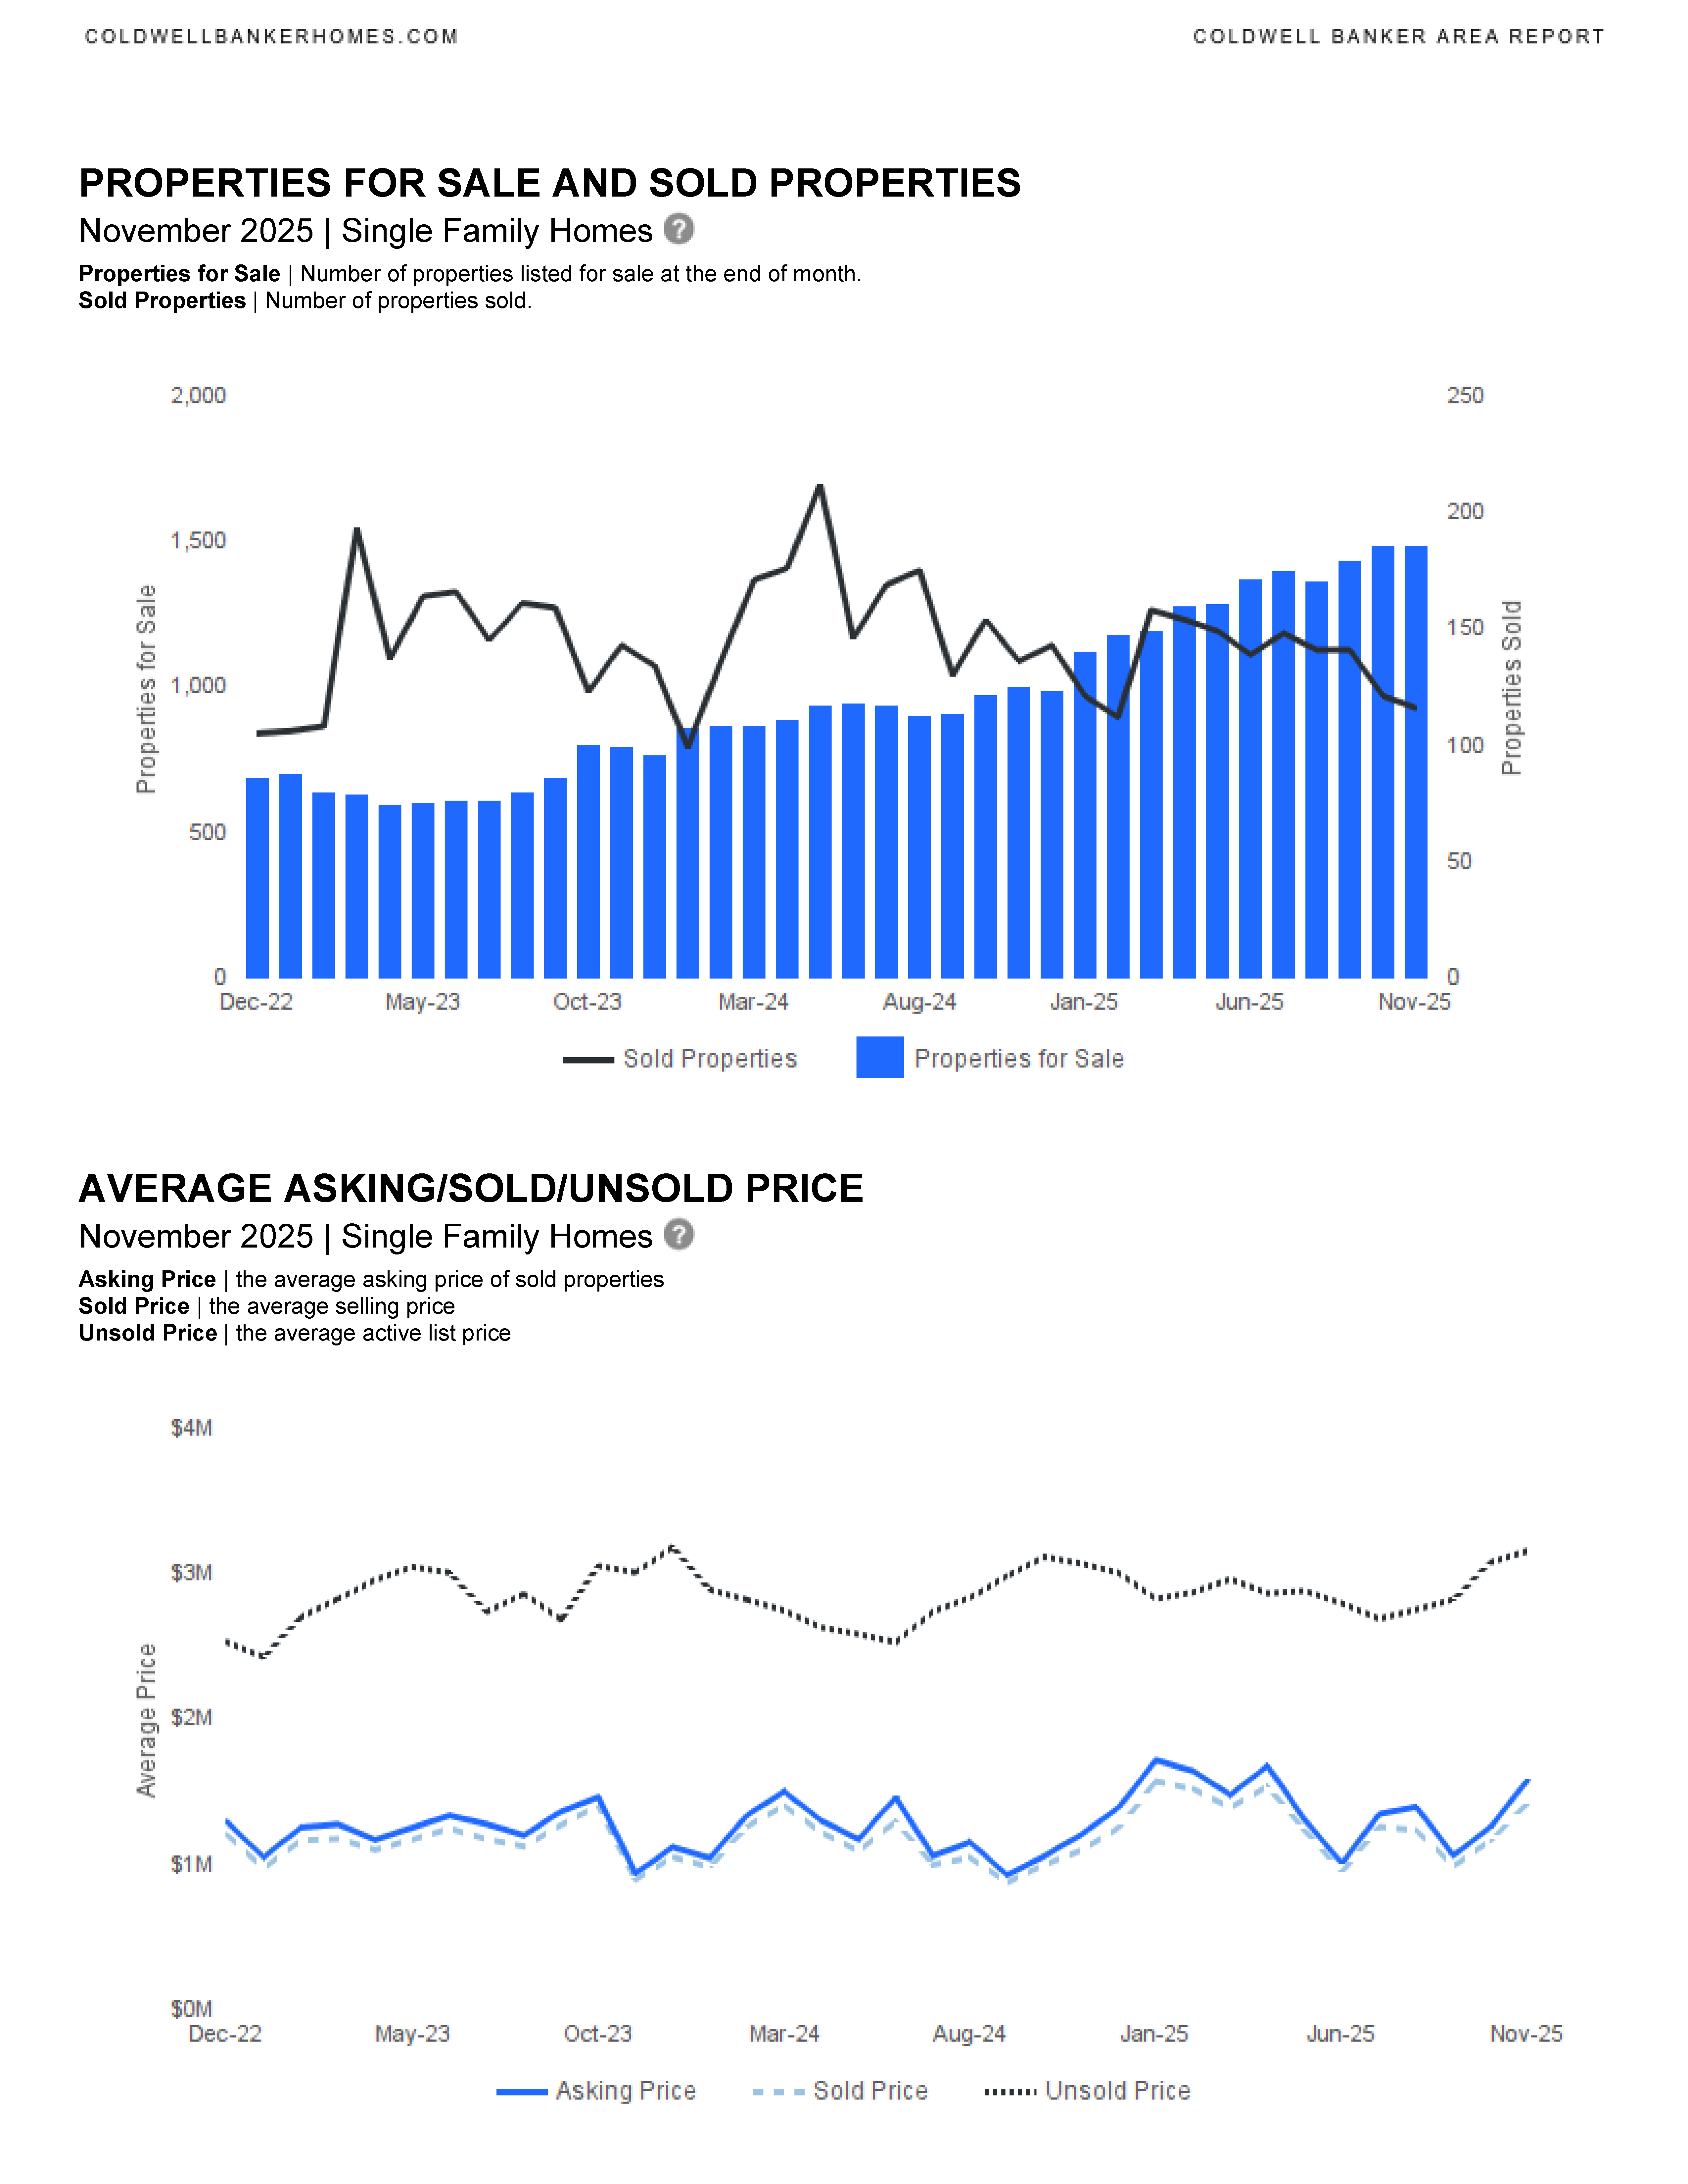
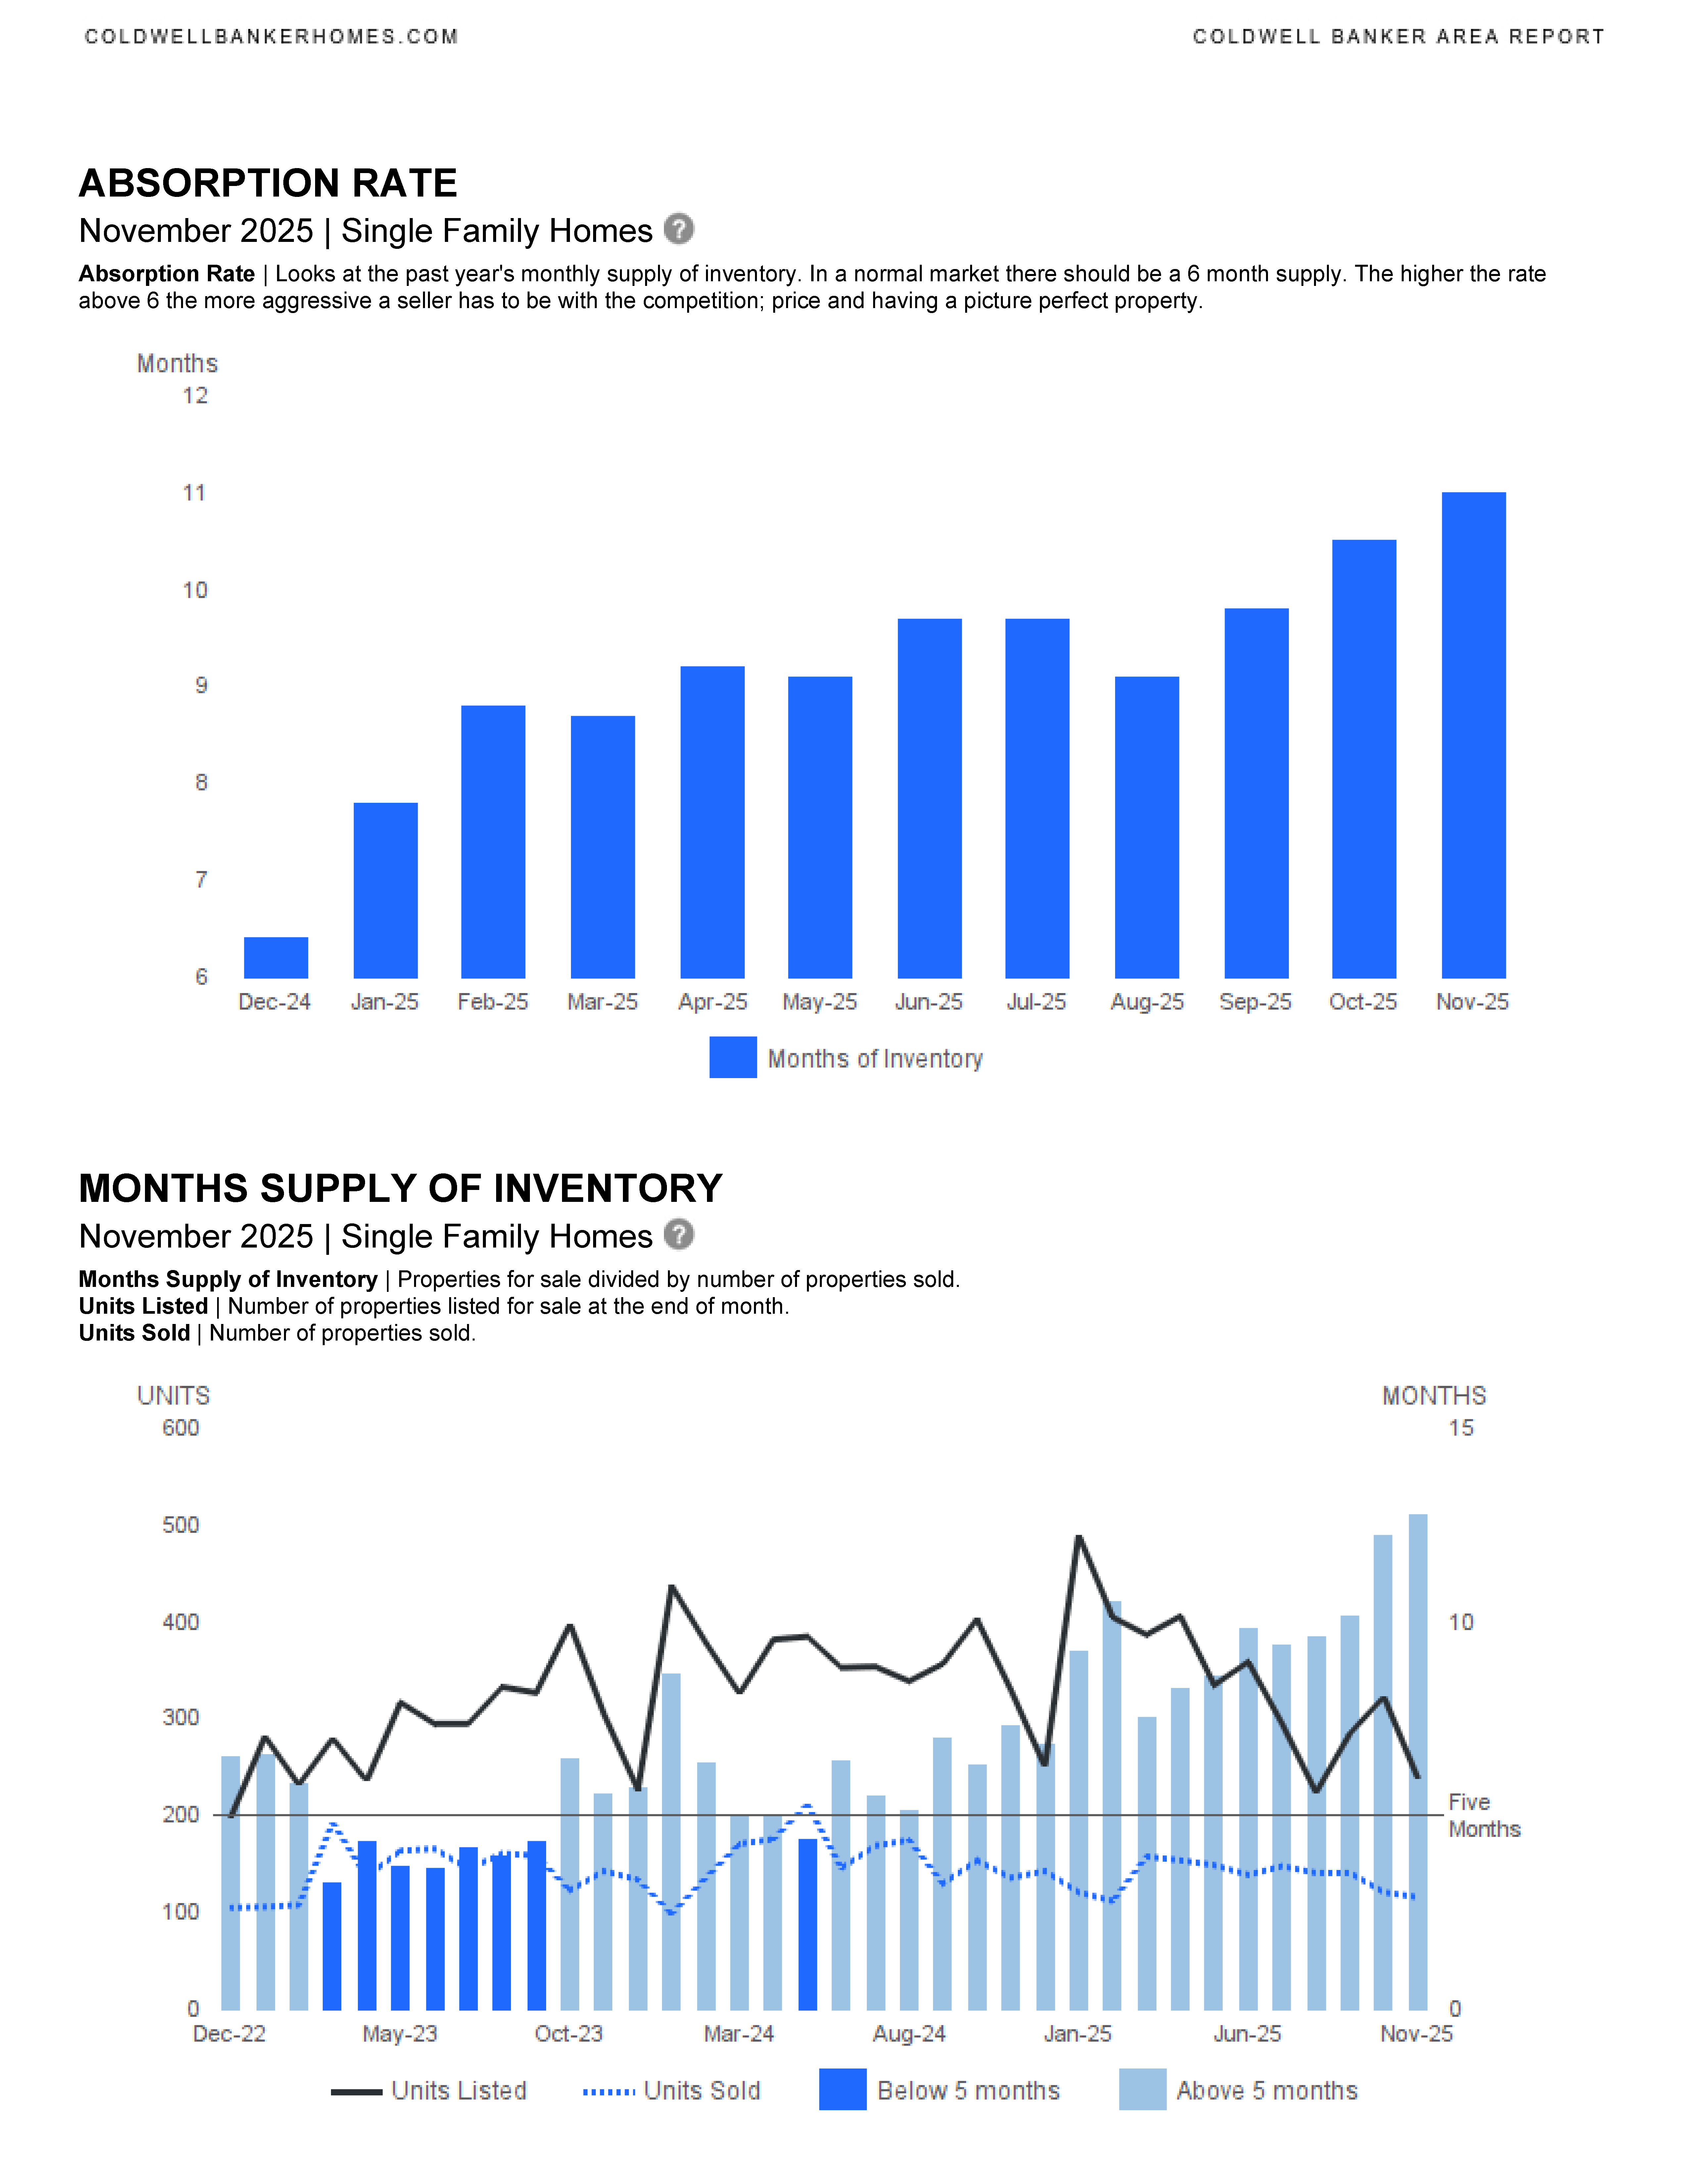
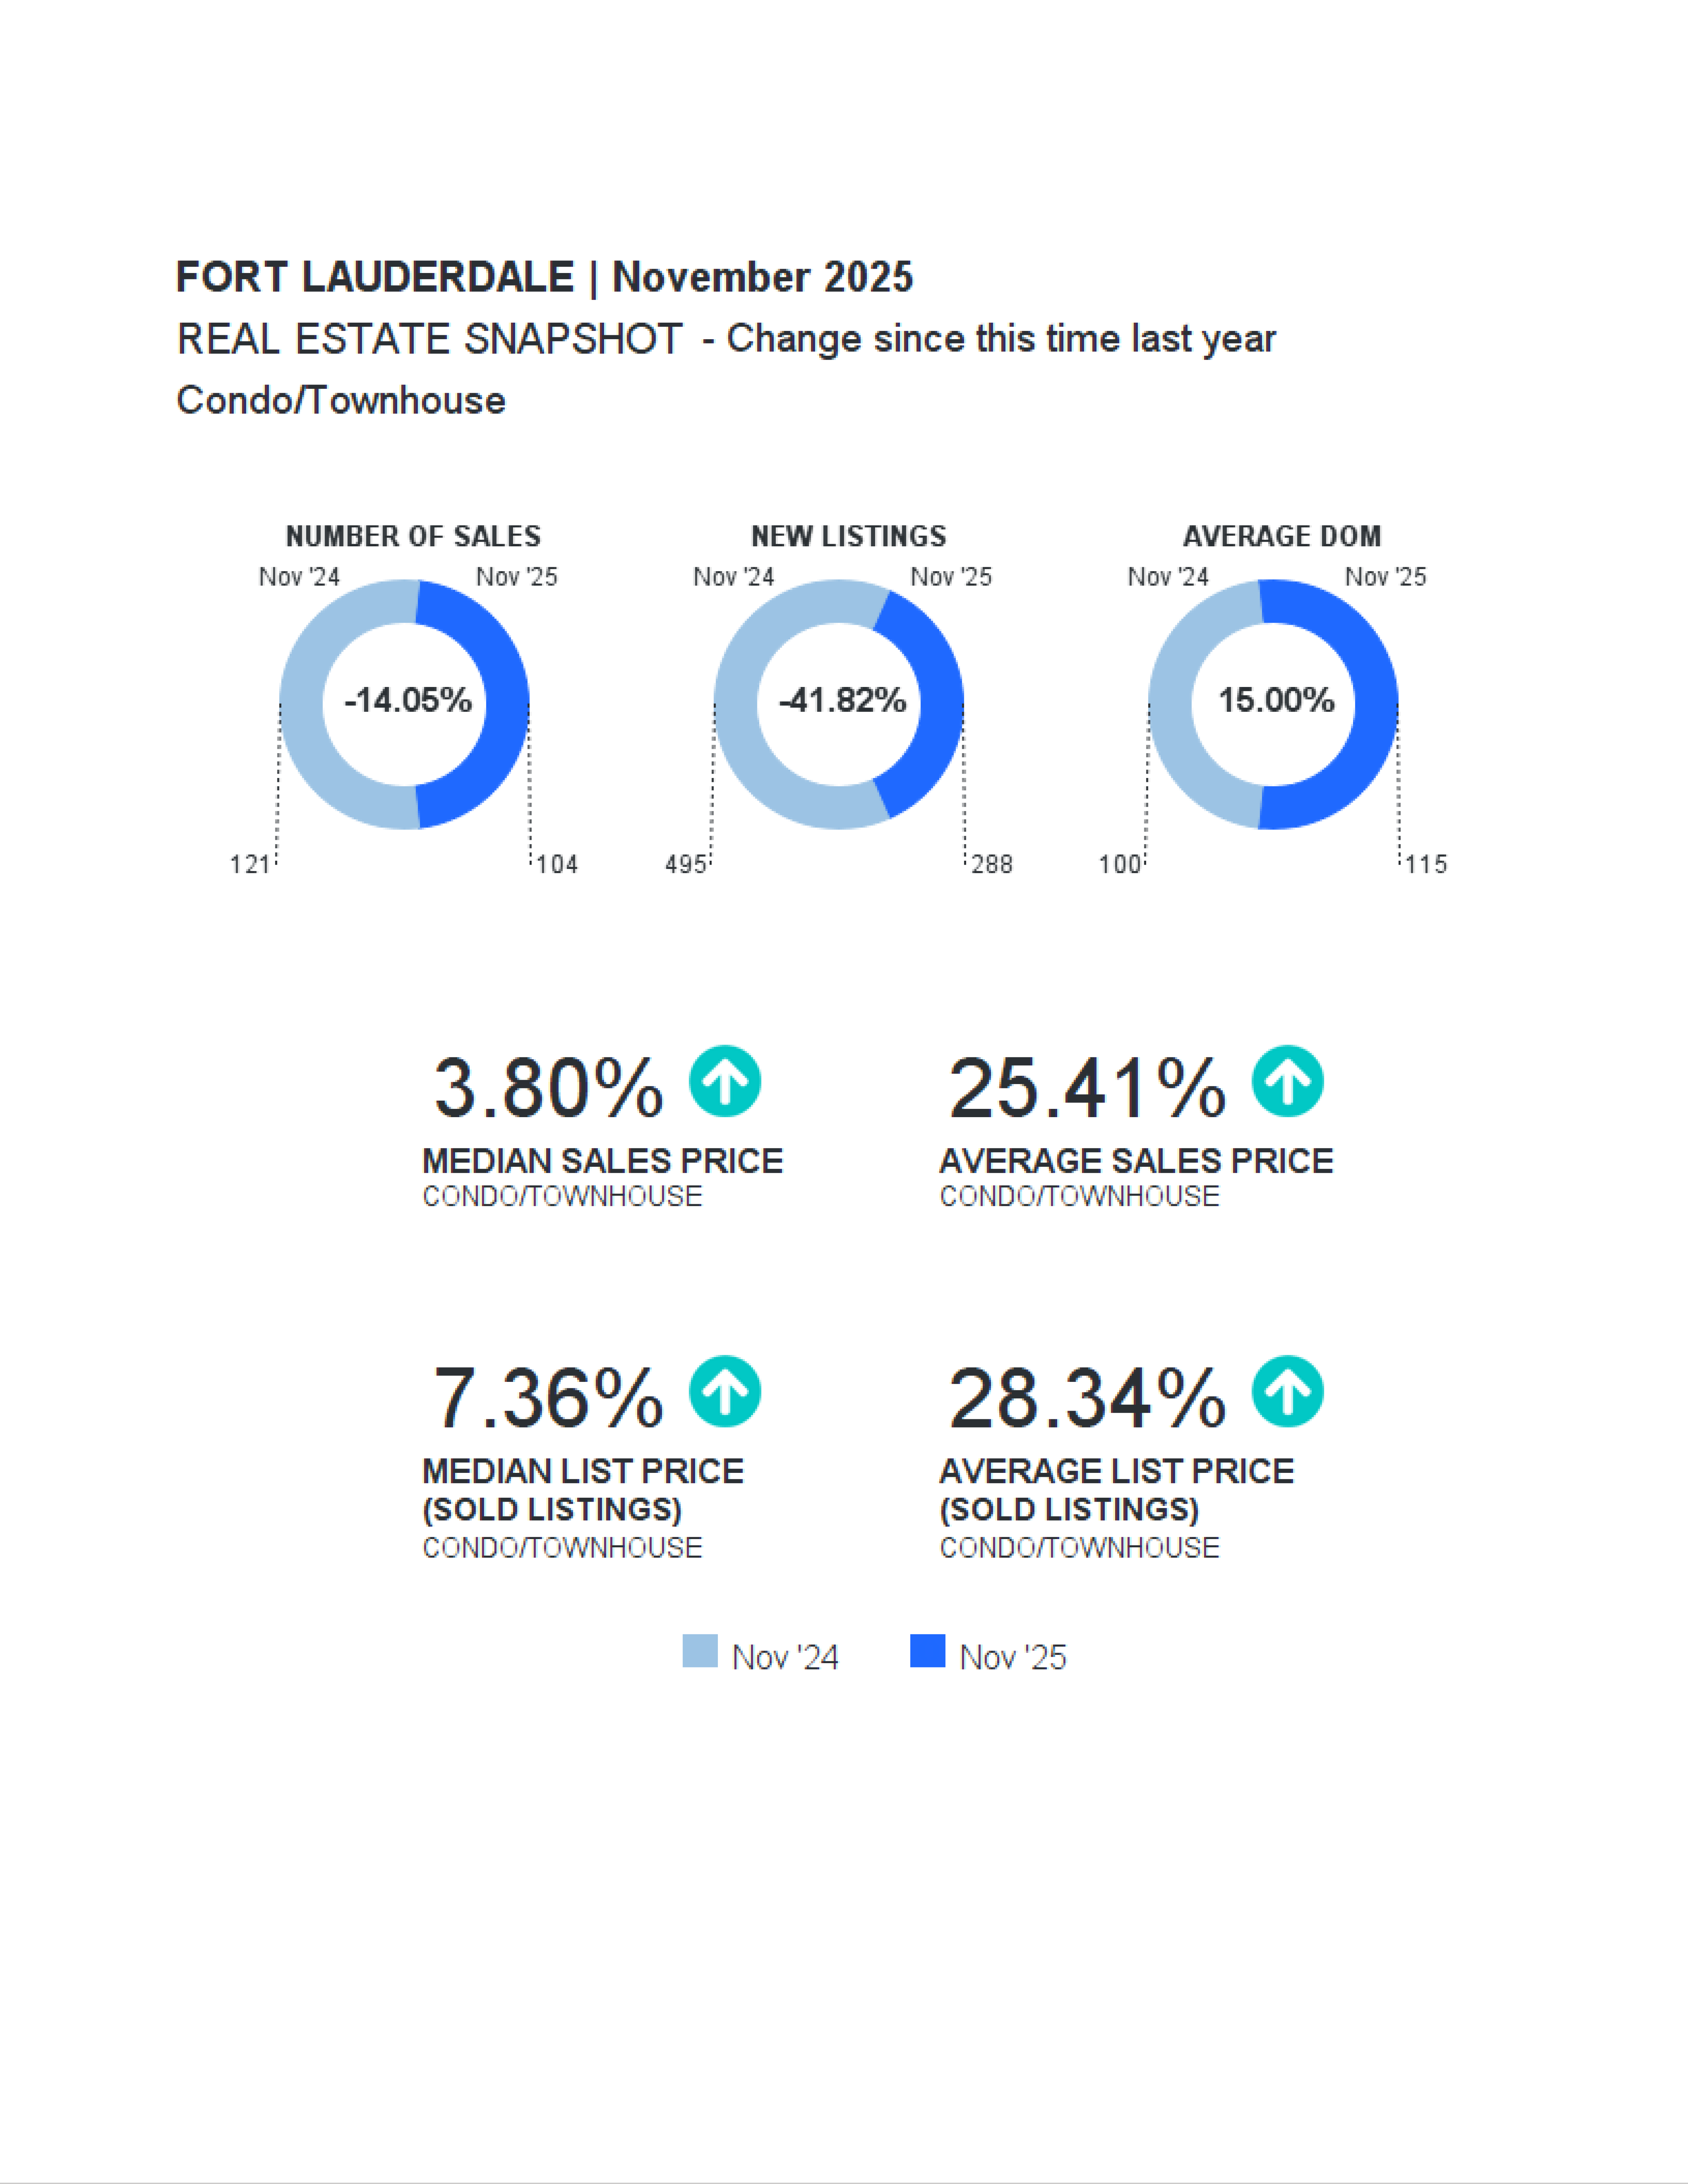
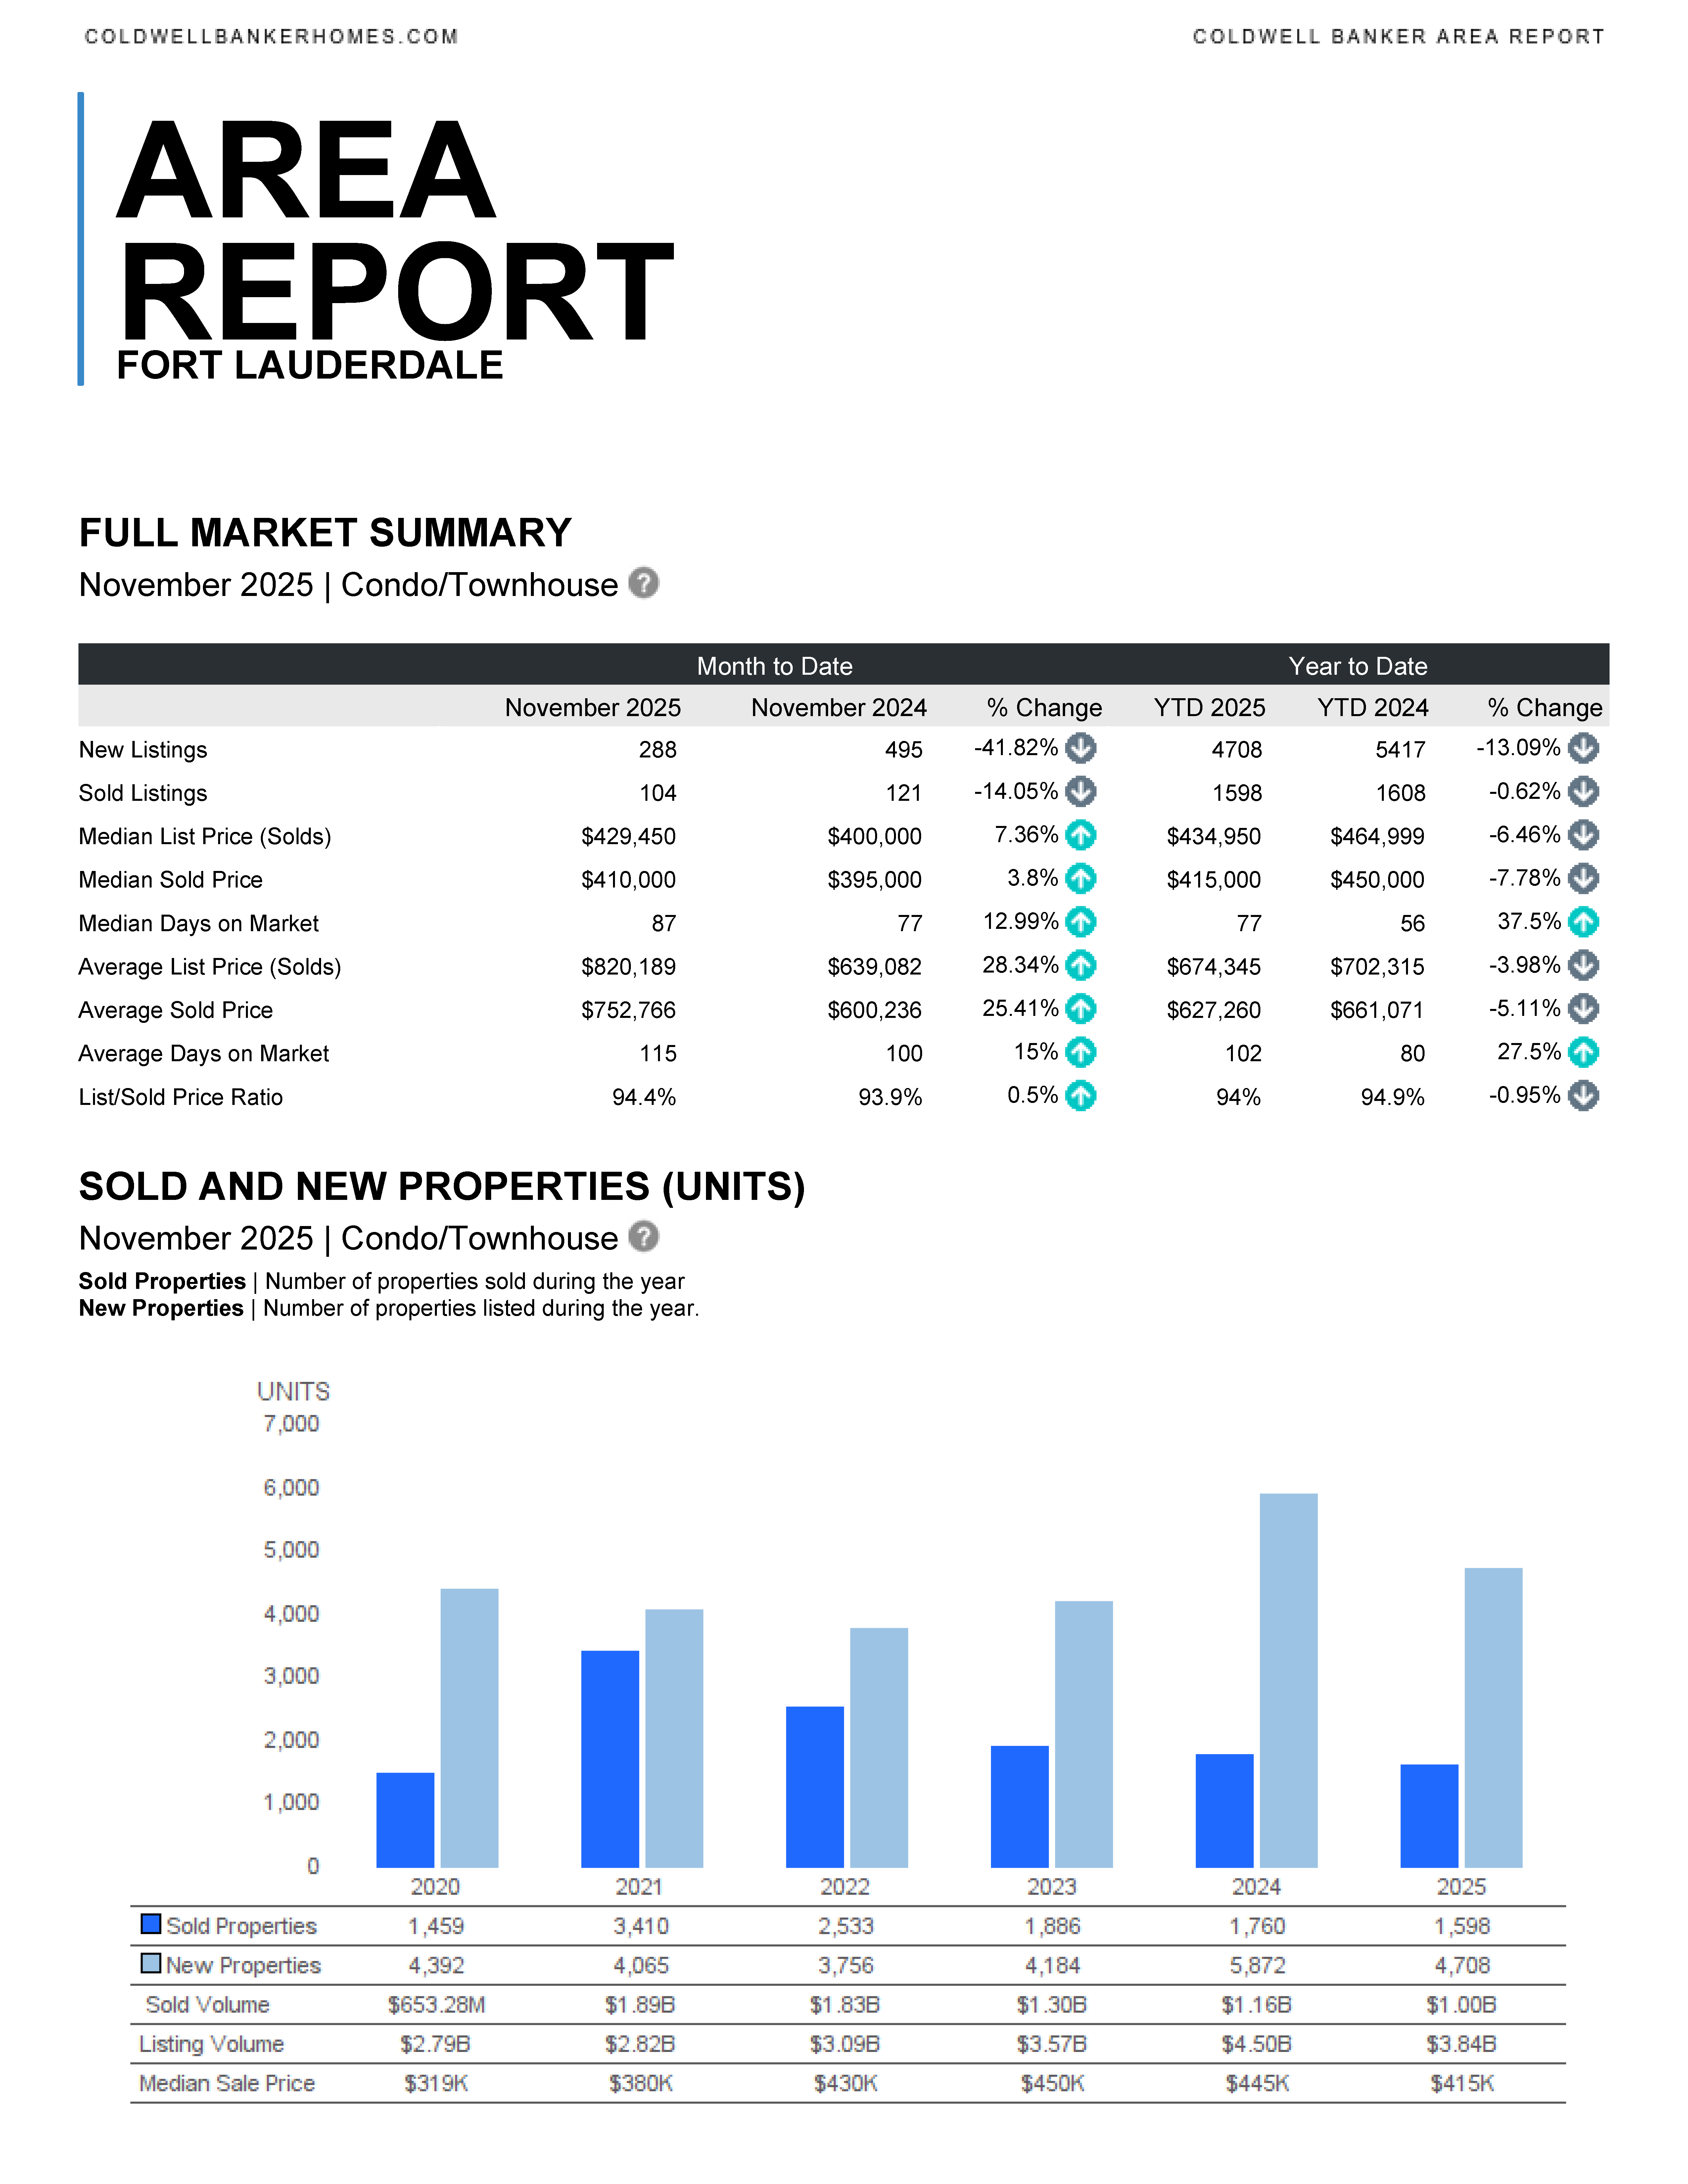
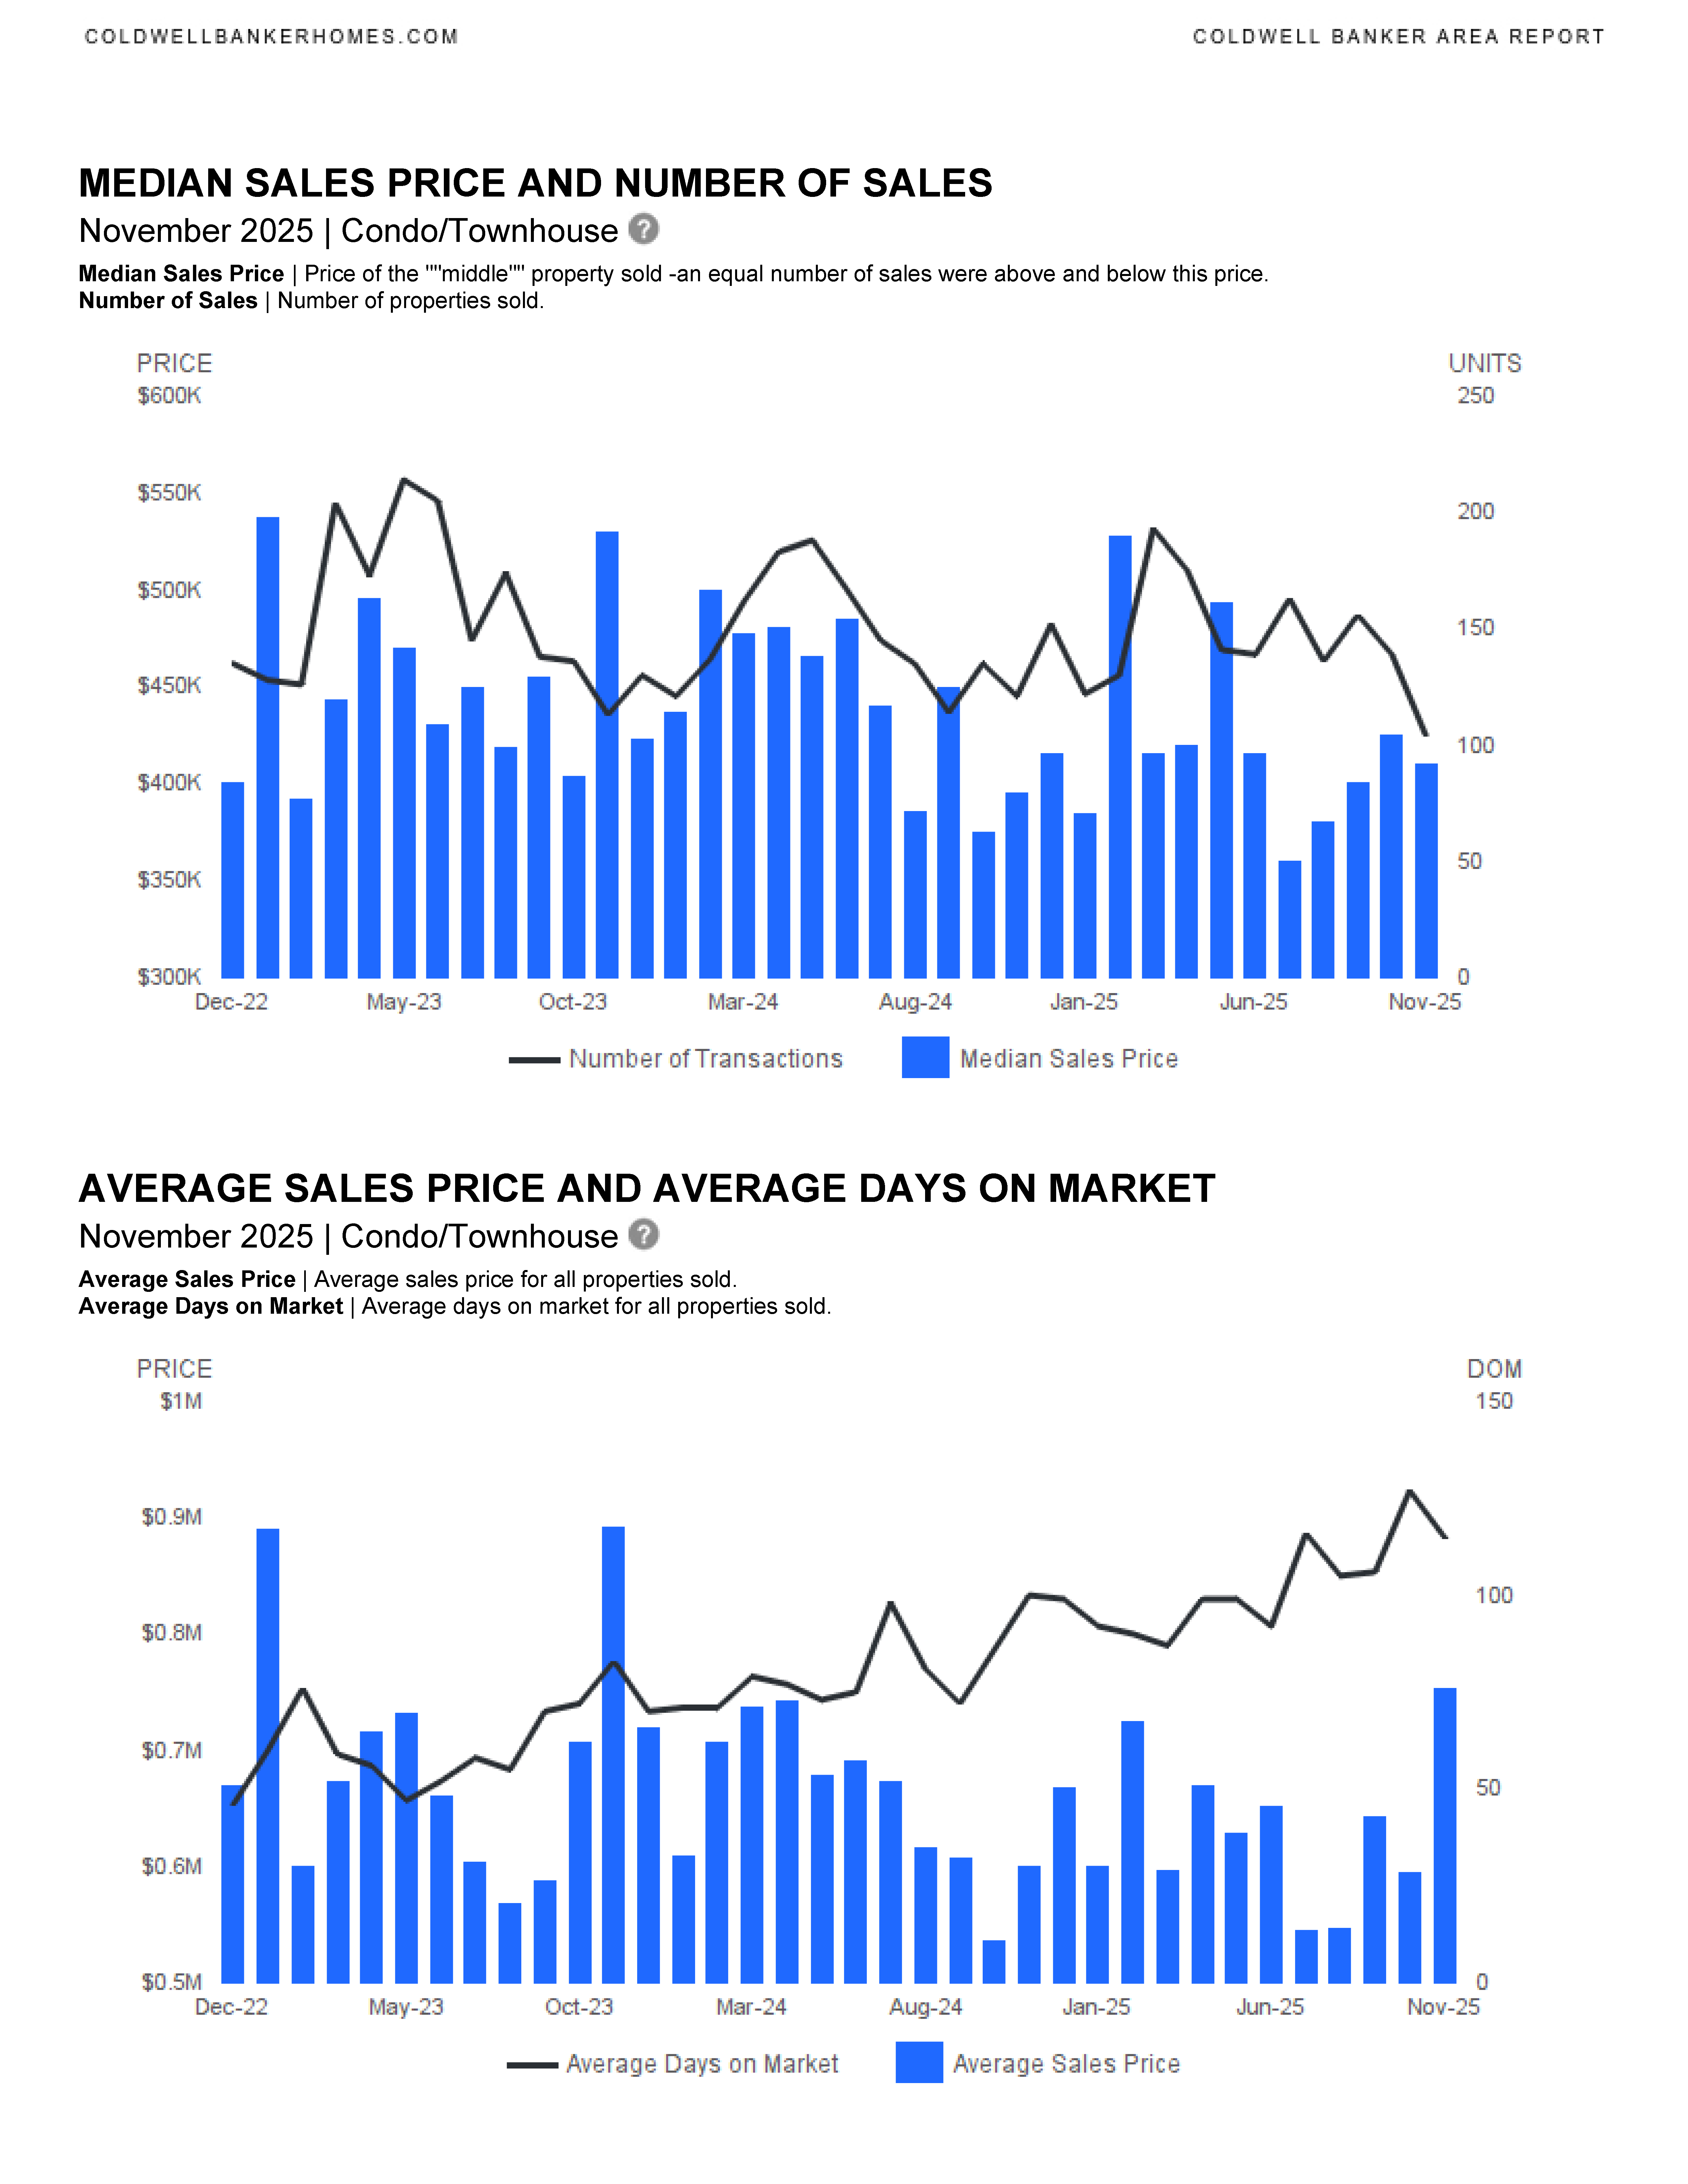
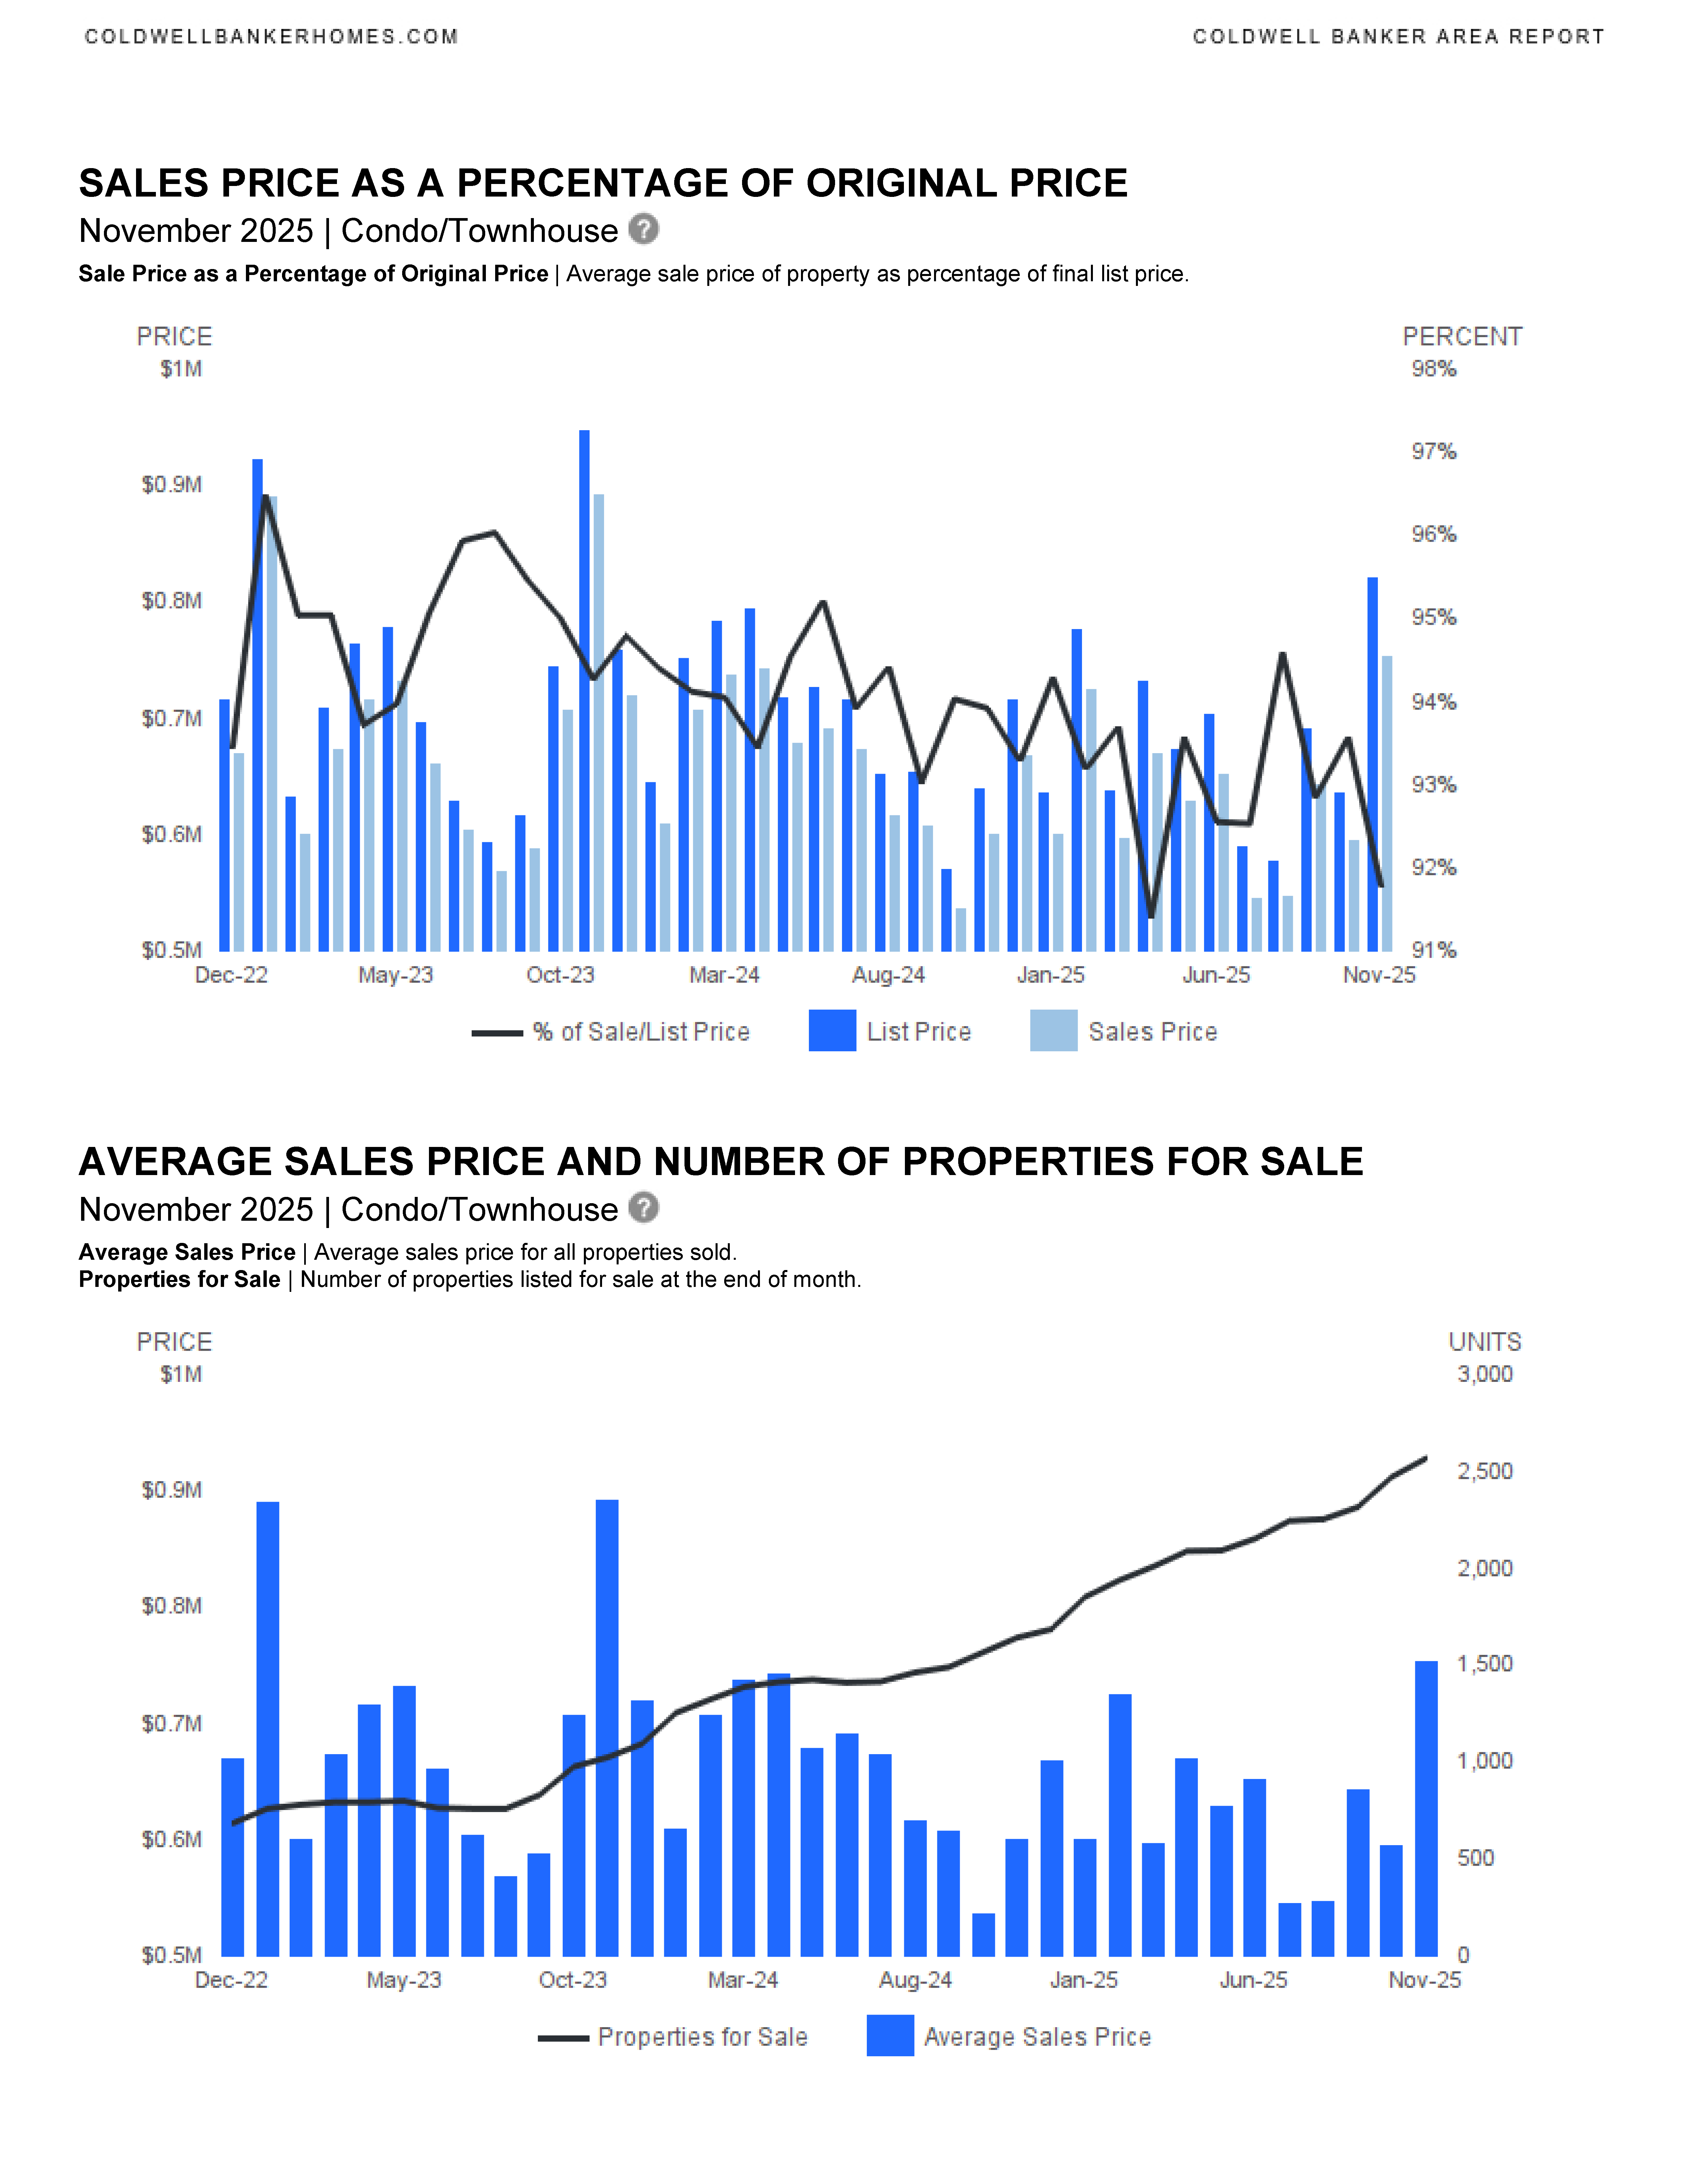
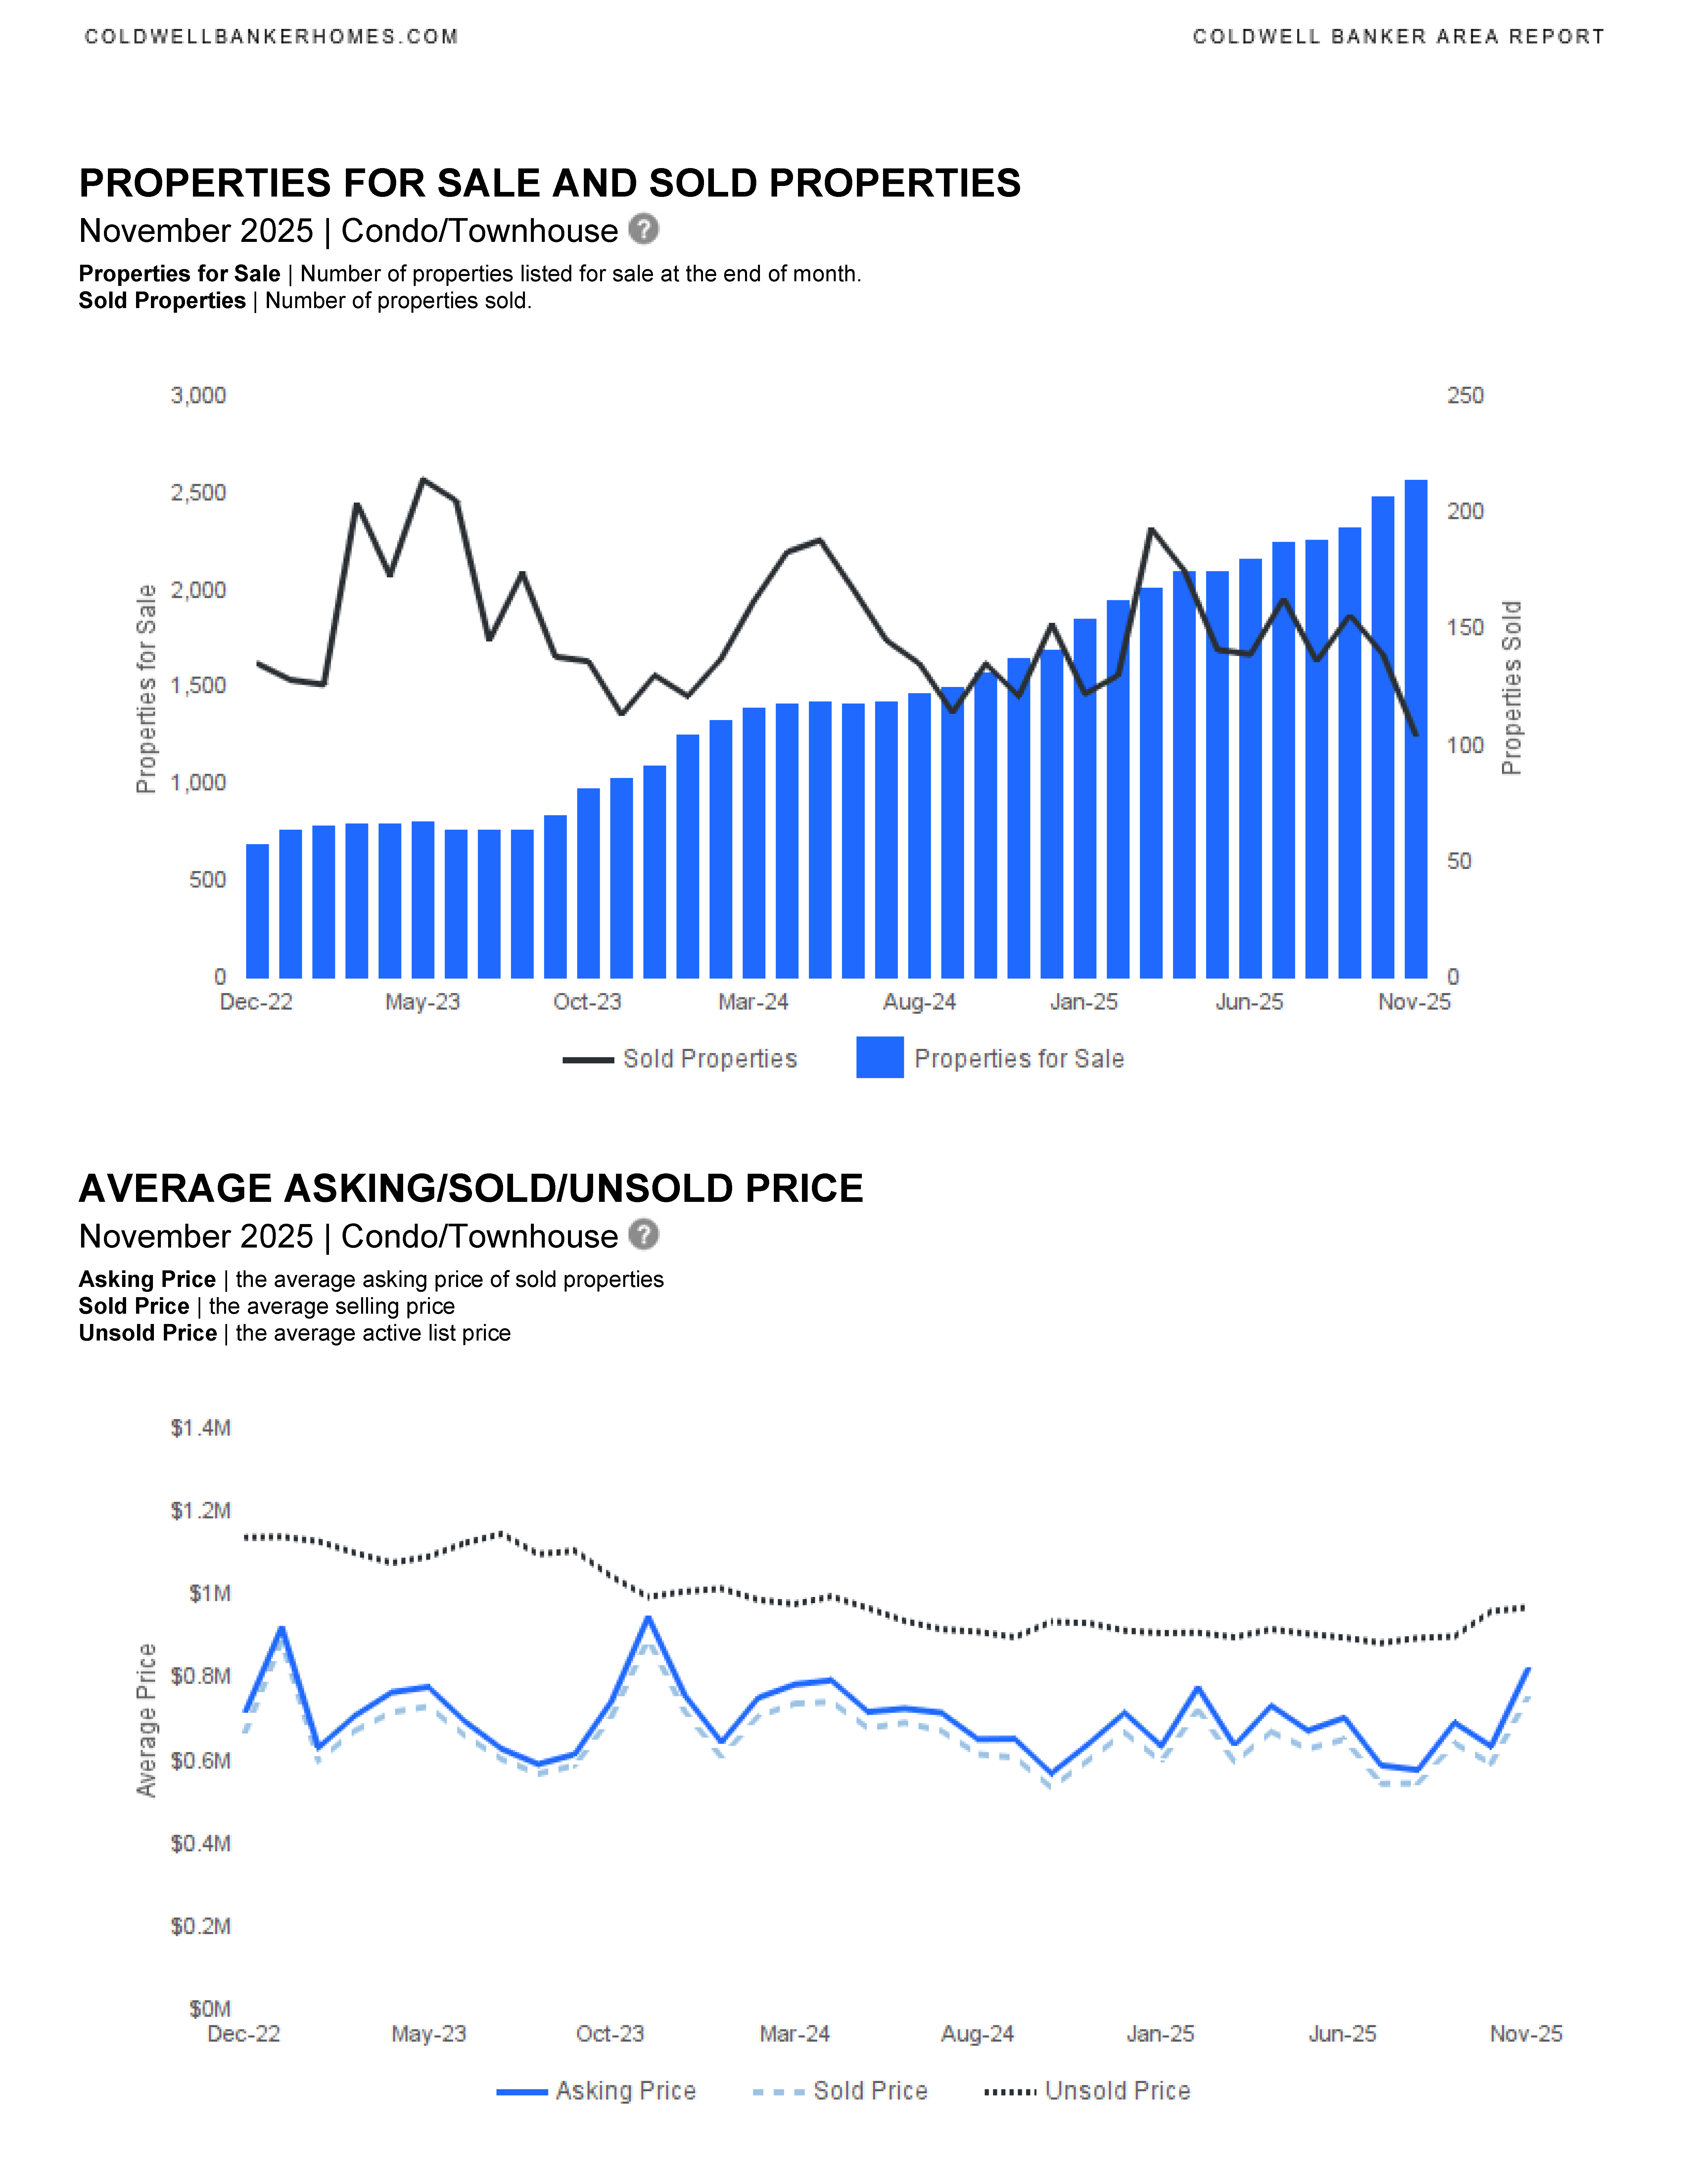
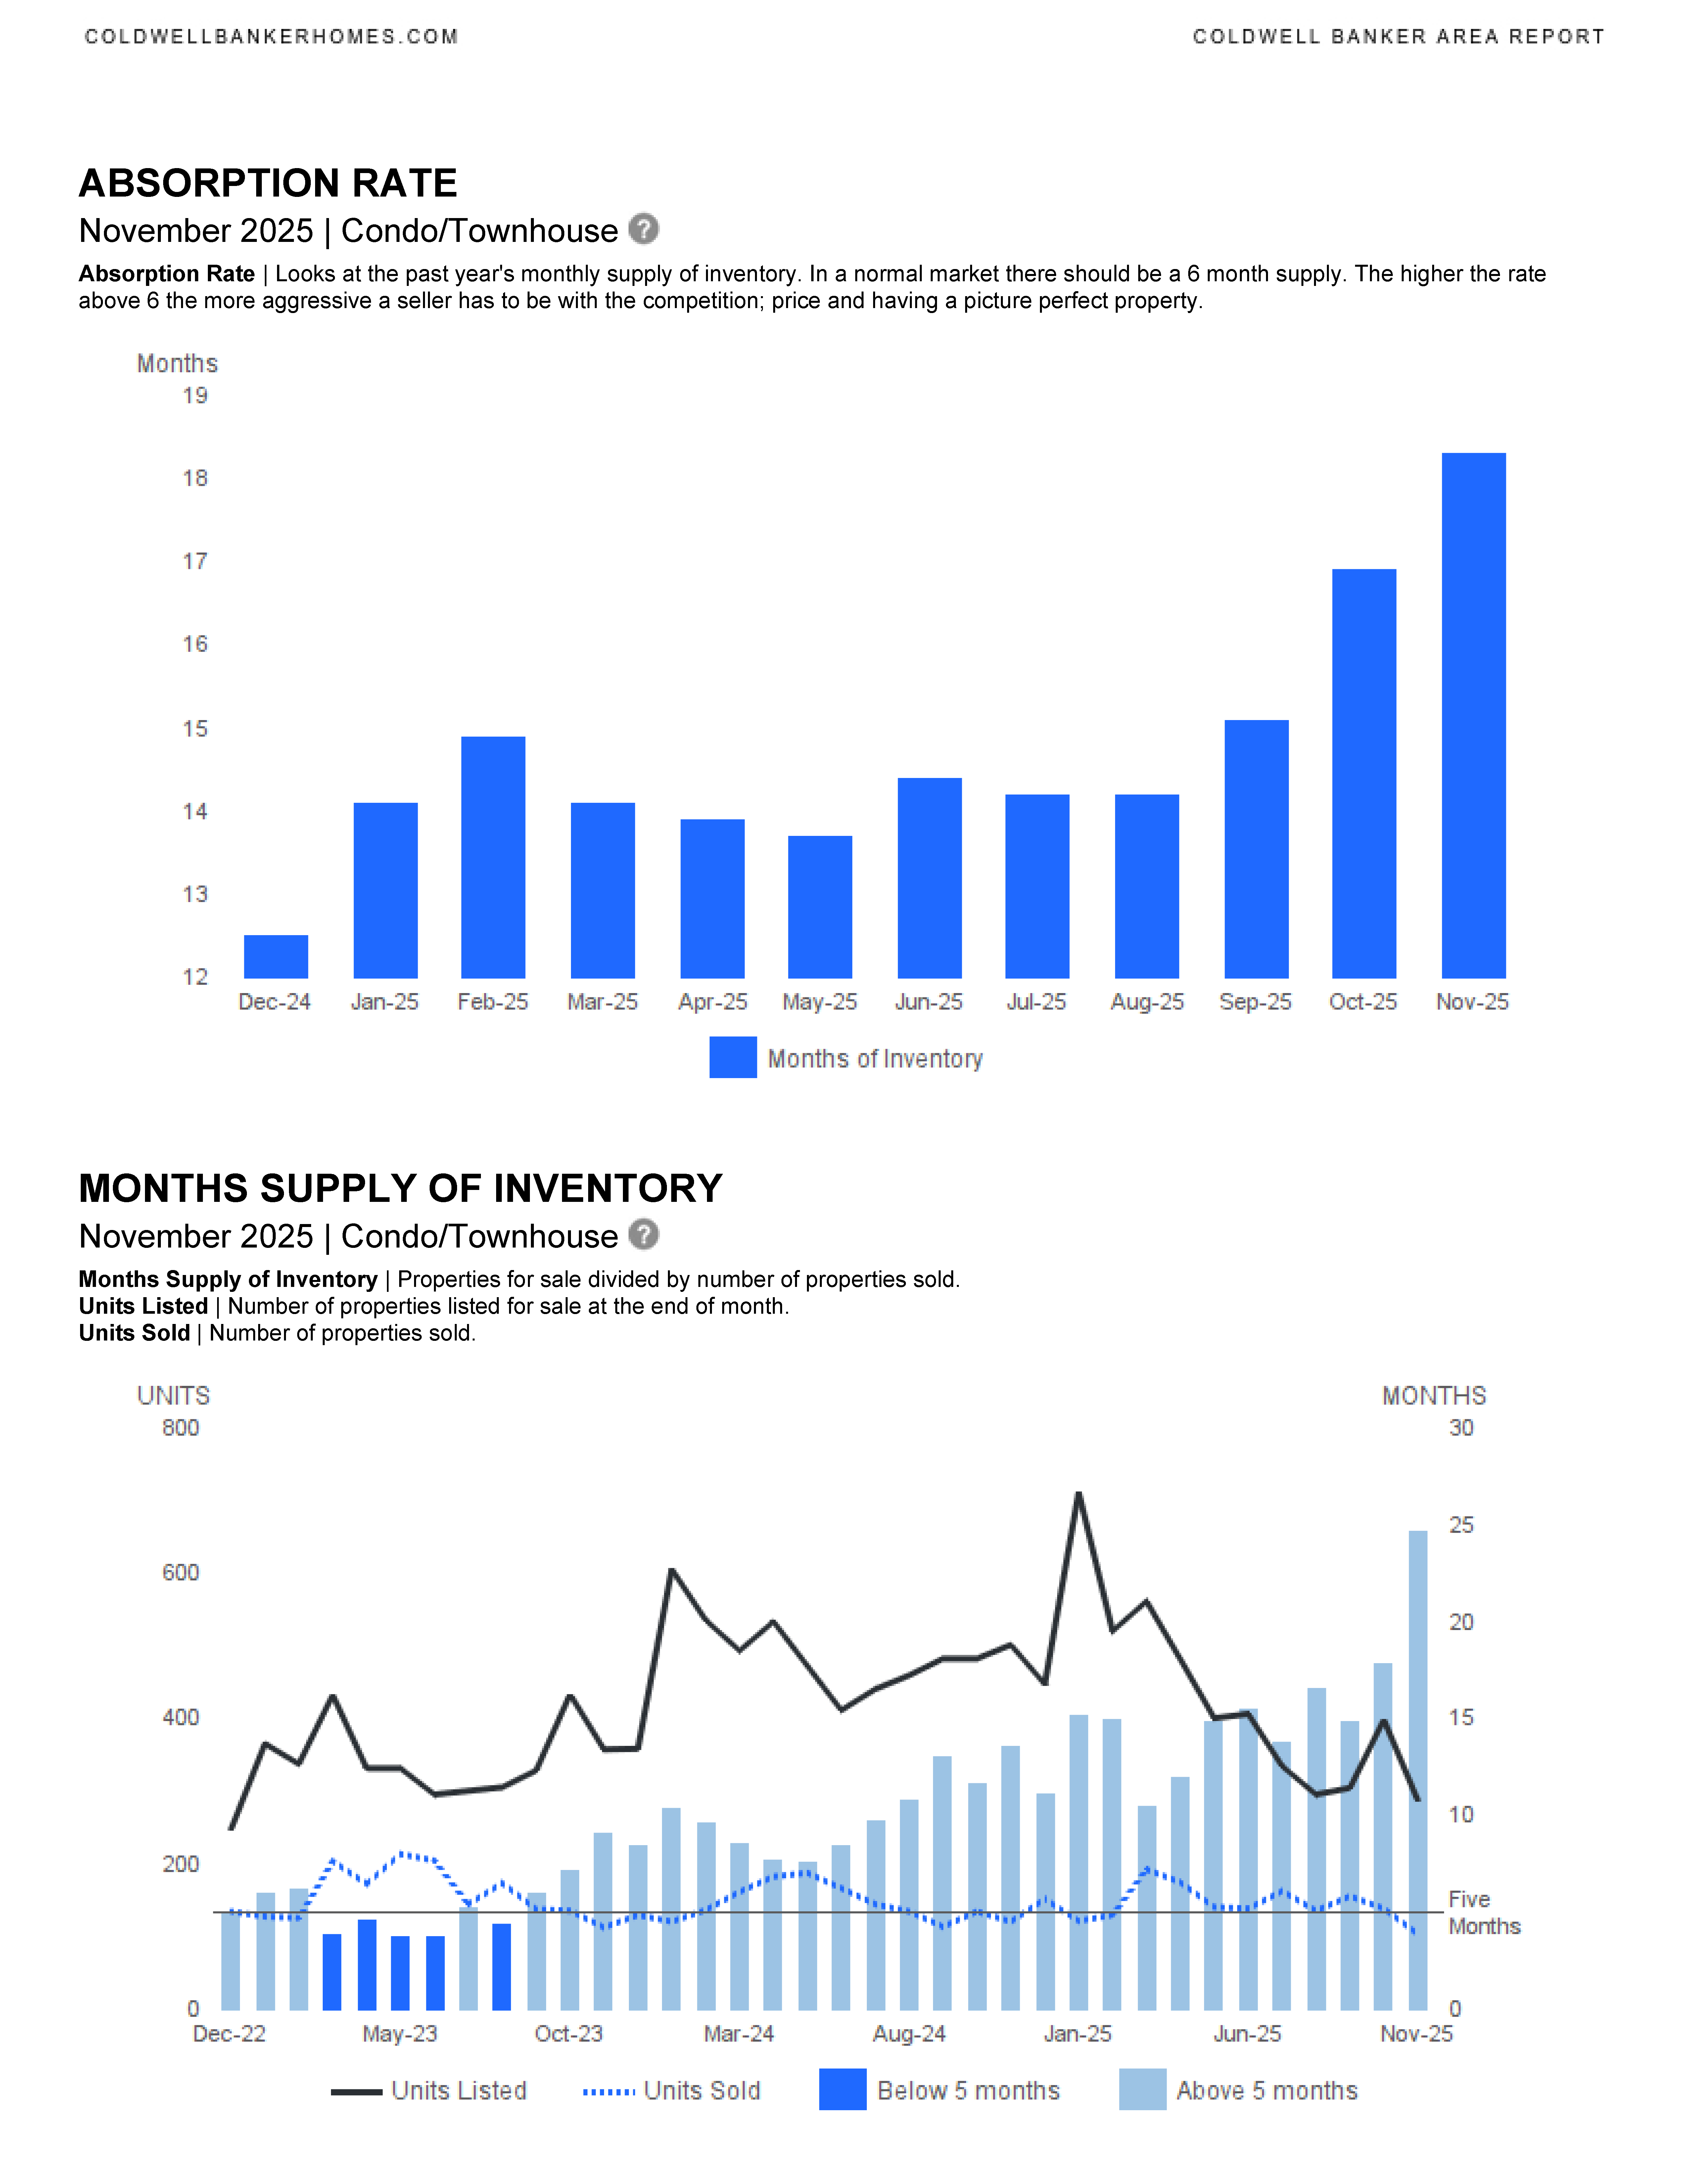
Fort Lauderdale November 2025 Area Report
Fort Lauderdale November 2025 real estate statistics have been published.
Fort Lauderdale Area Reports
Single Family Homes
Condominium & Townhouses
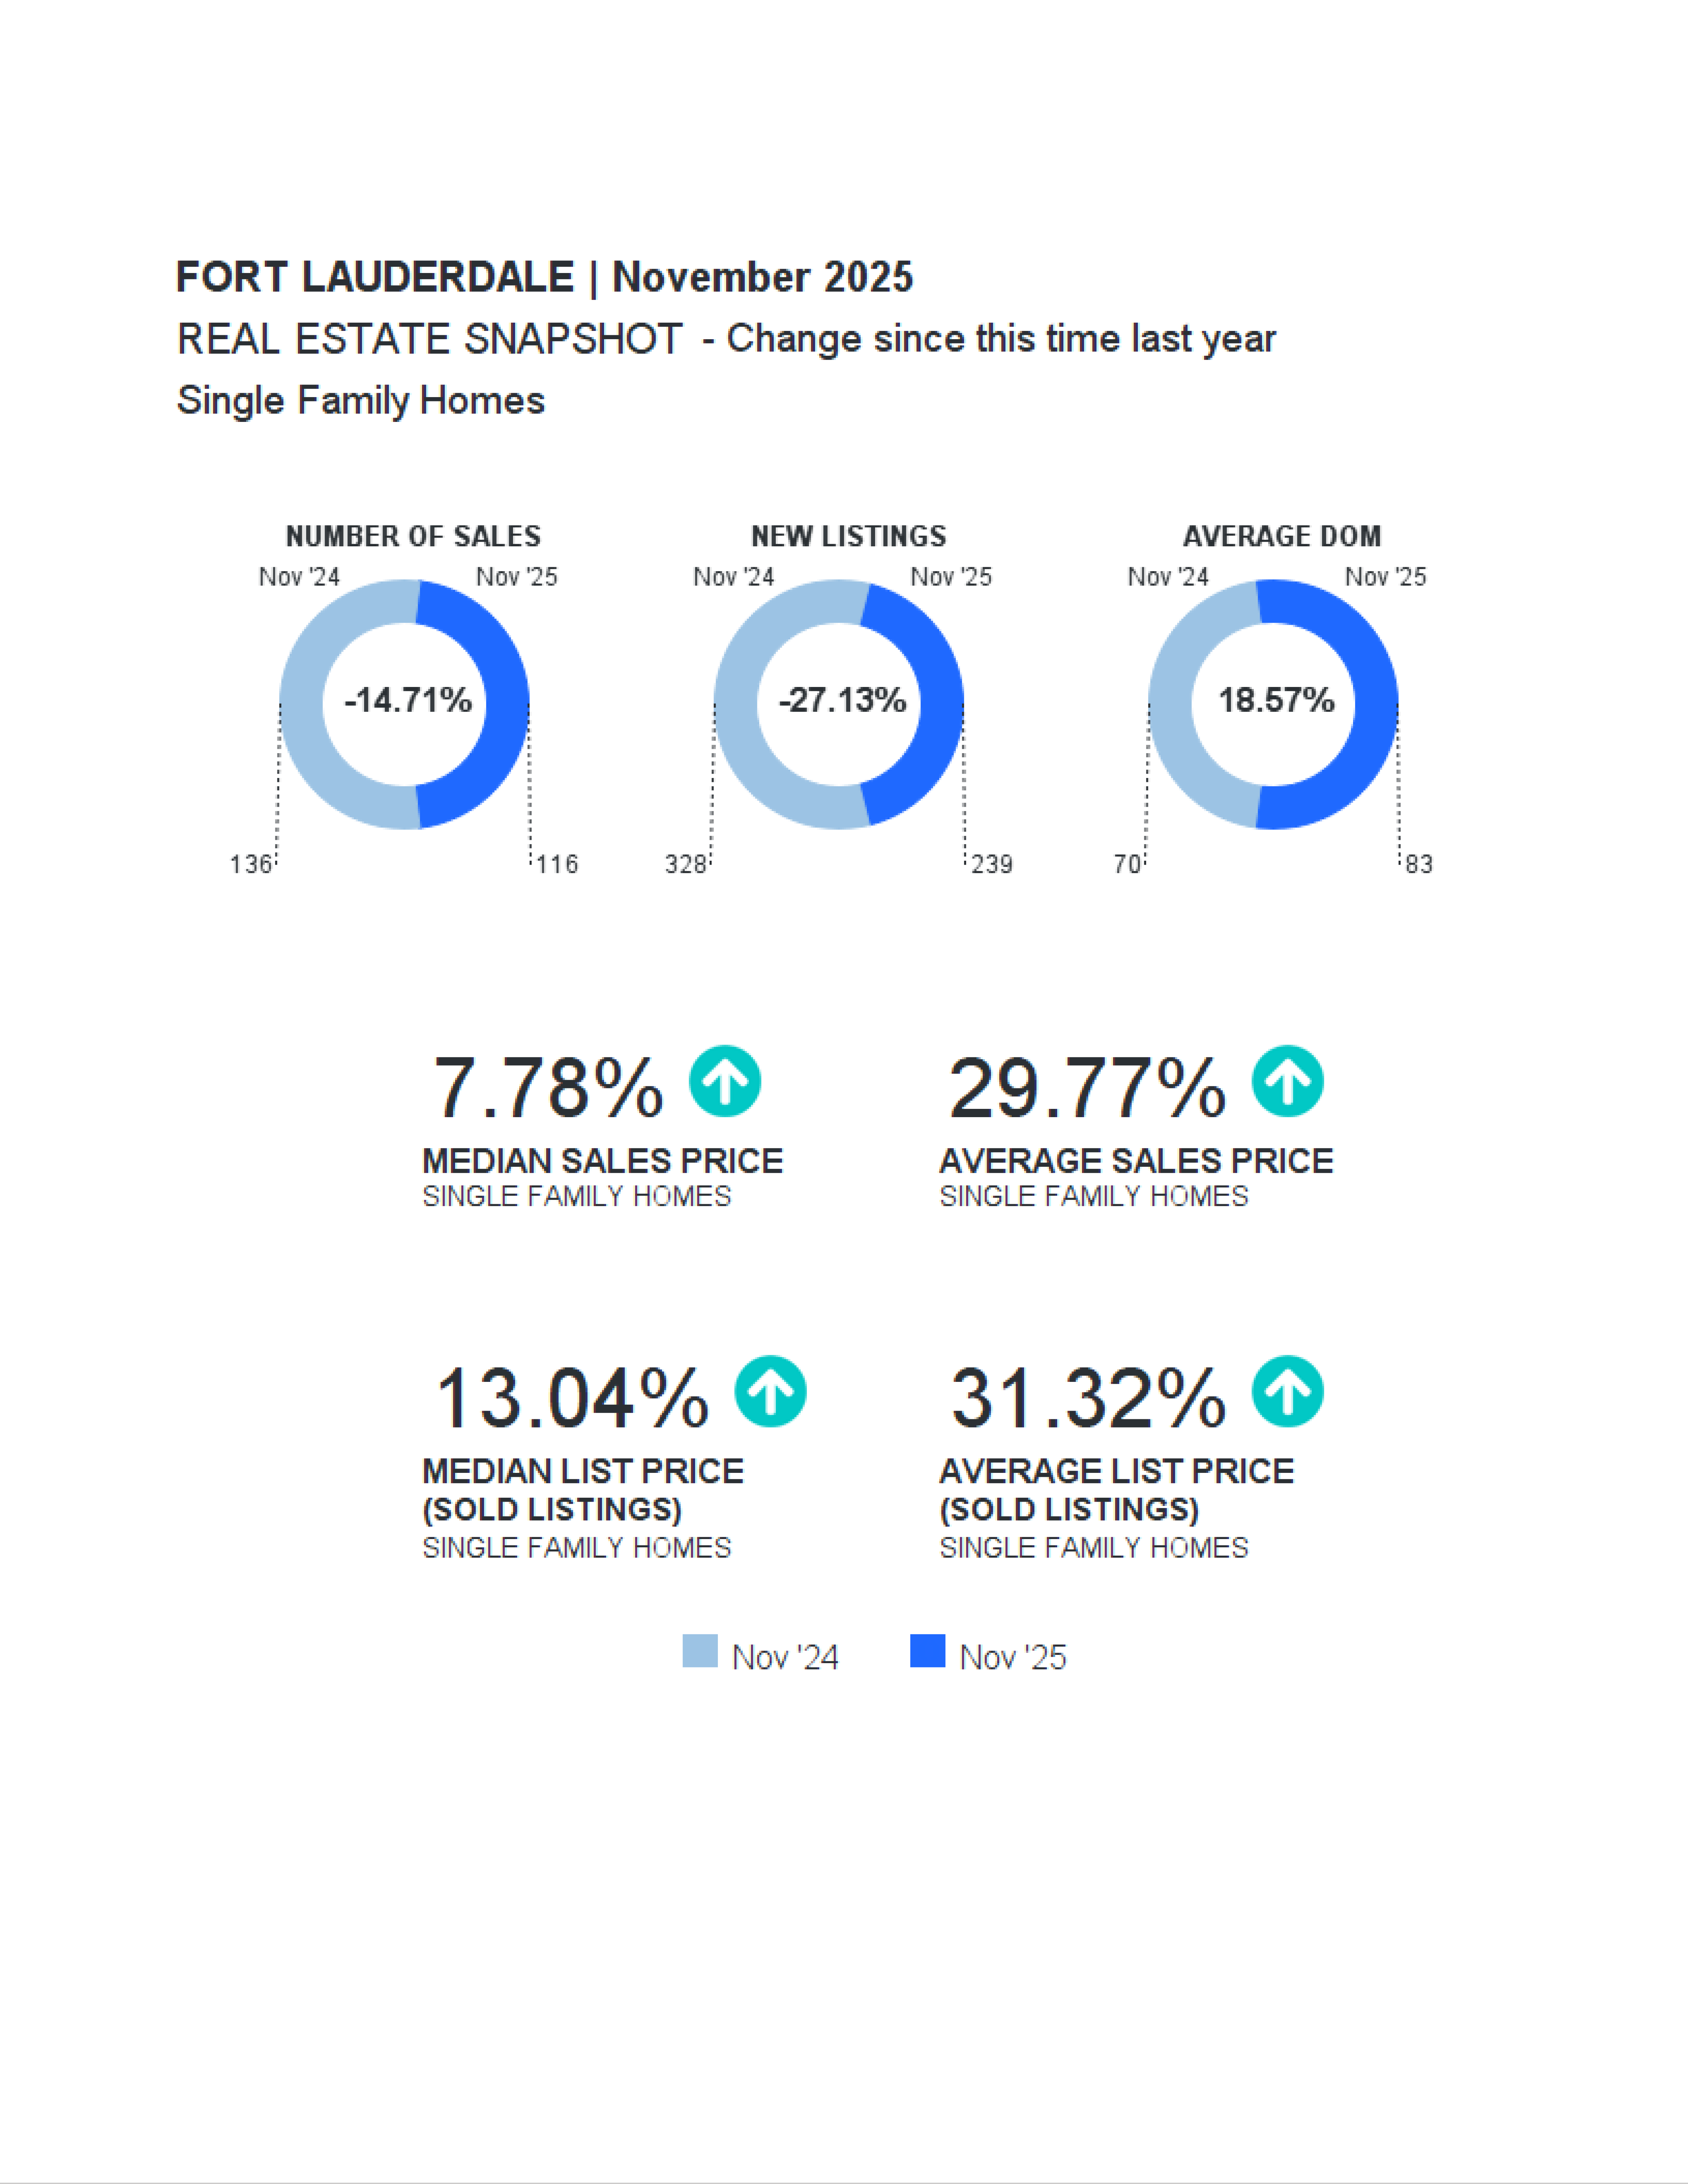
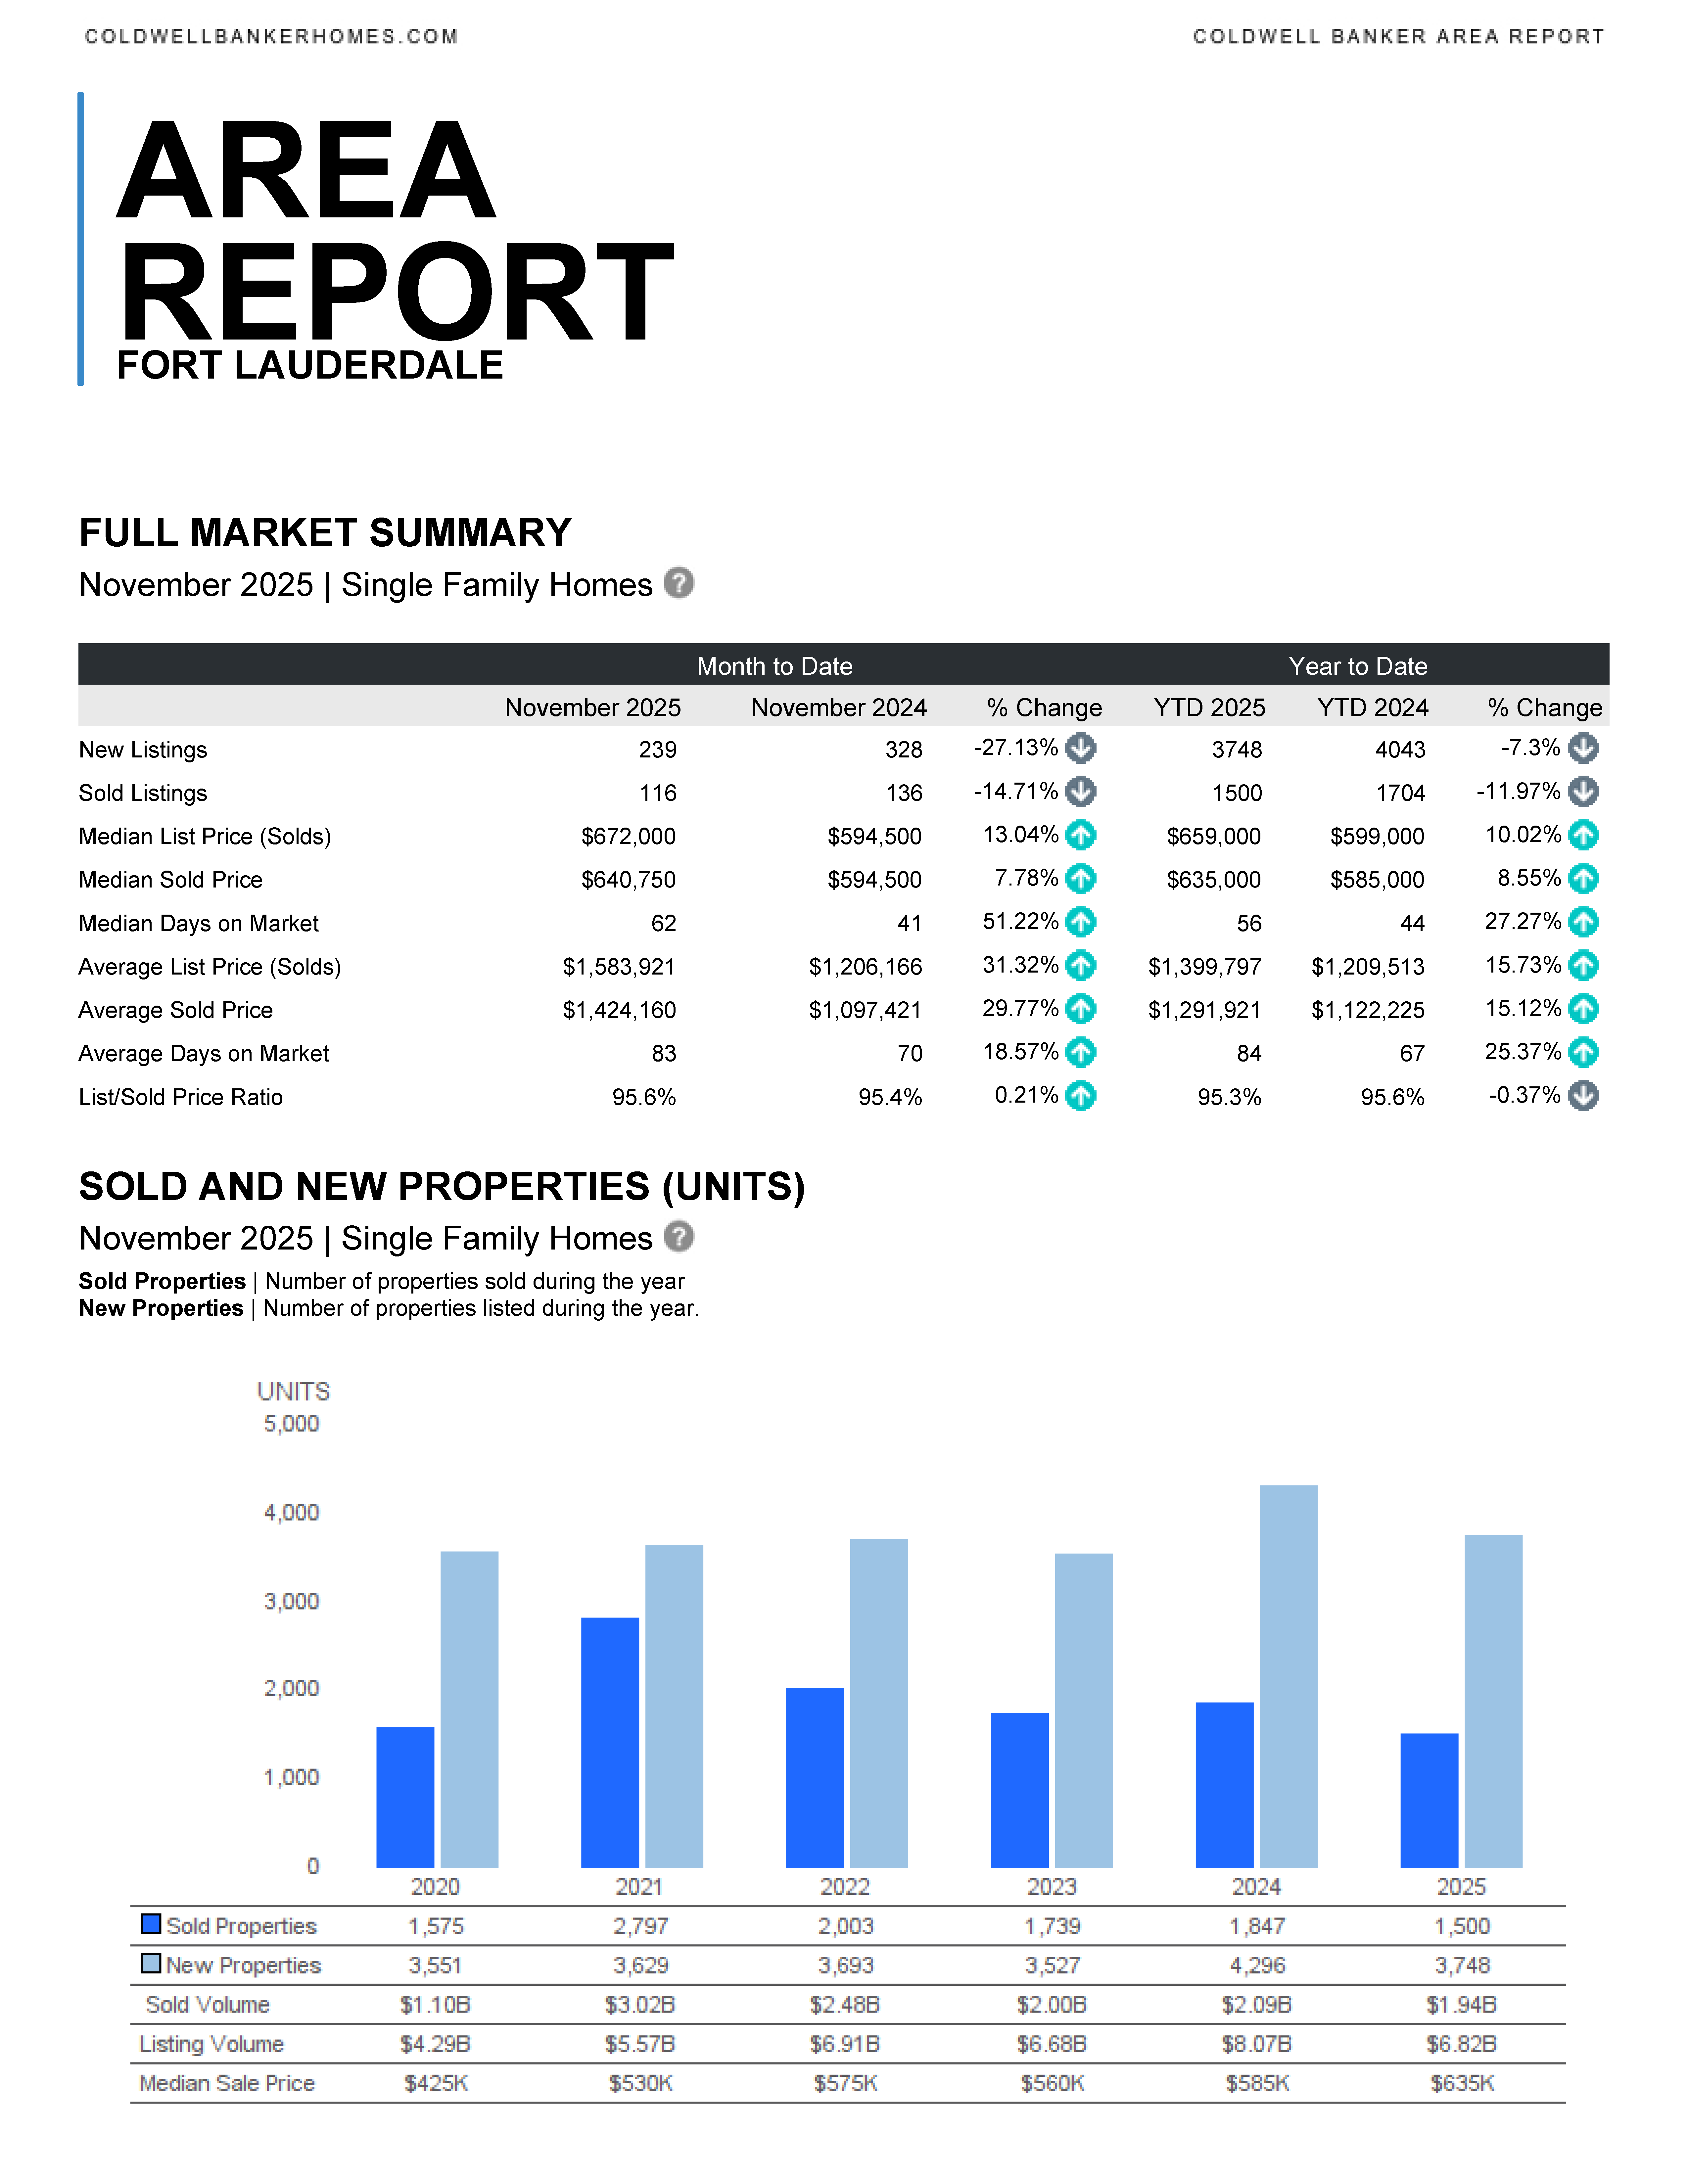
Fort Lauderdale Real Estate Market Summary – November 2025
🏡Single-Family Homes
- New Listings: 239 (↓27.1% YoY)
- Sold Listings: 116 (↓14.7% YoY)
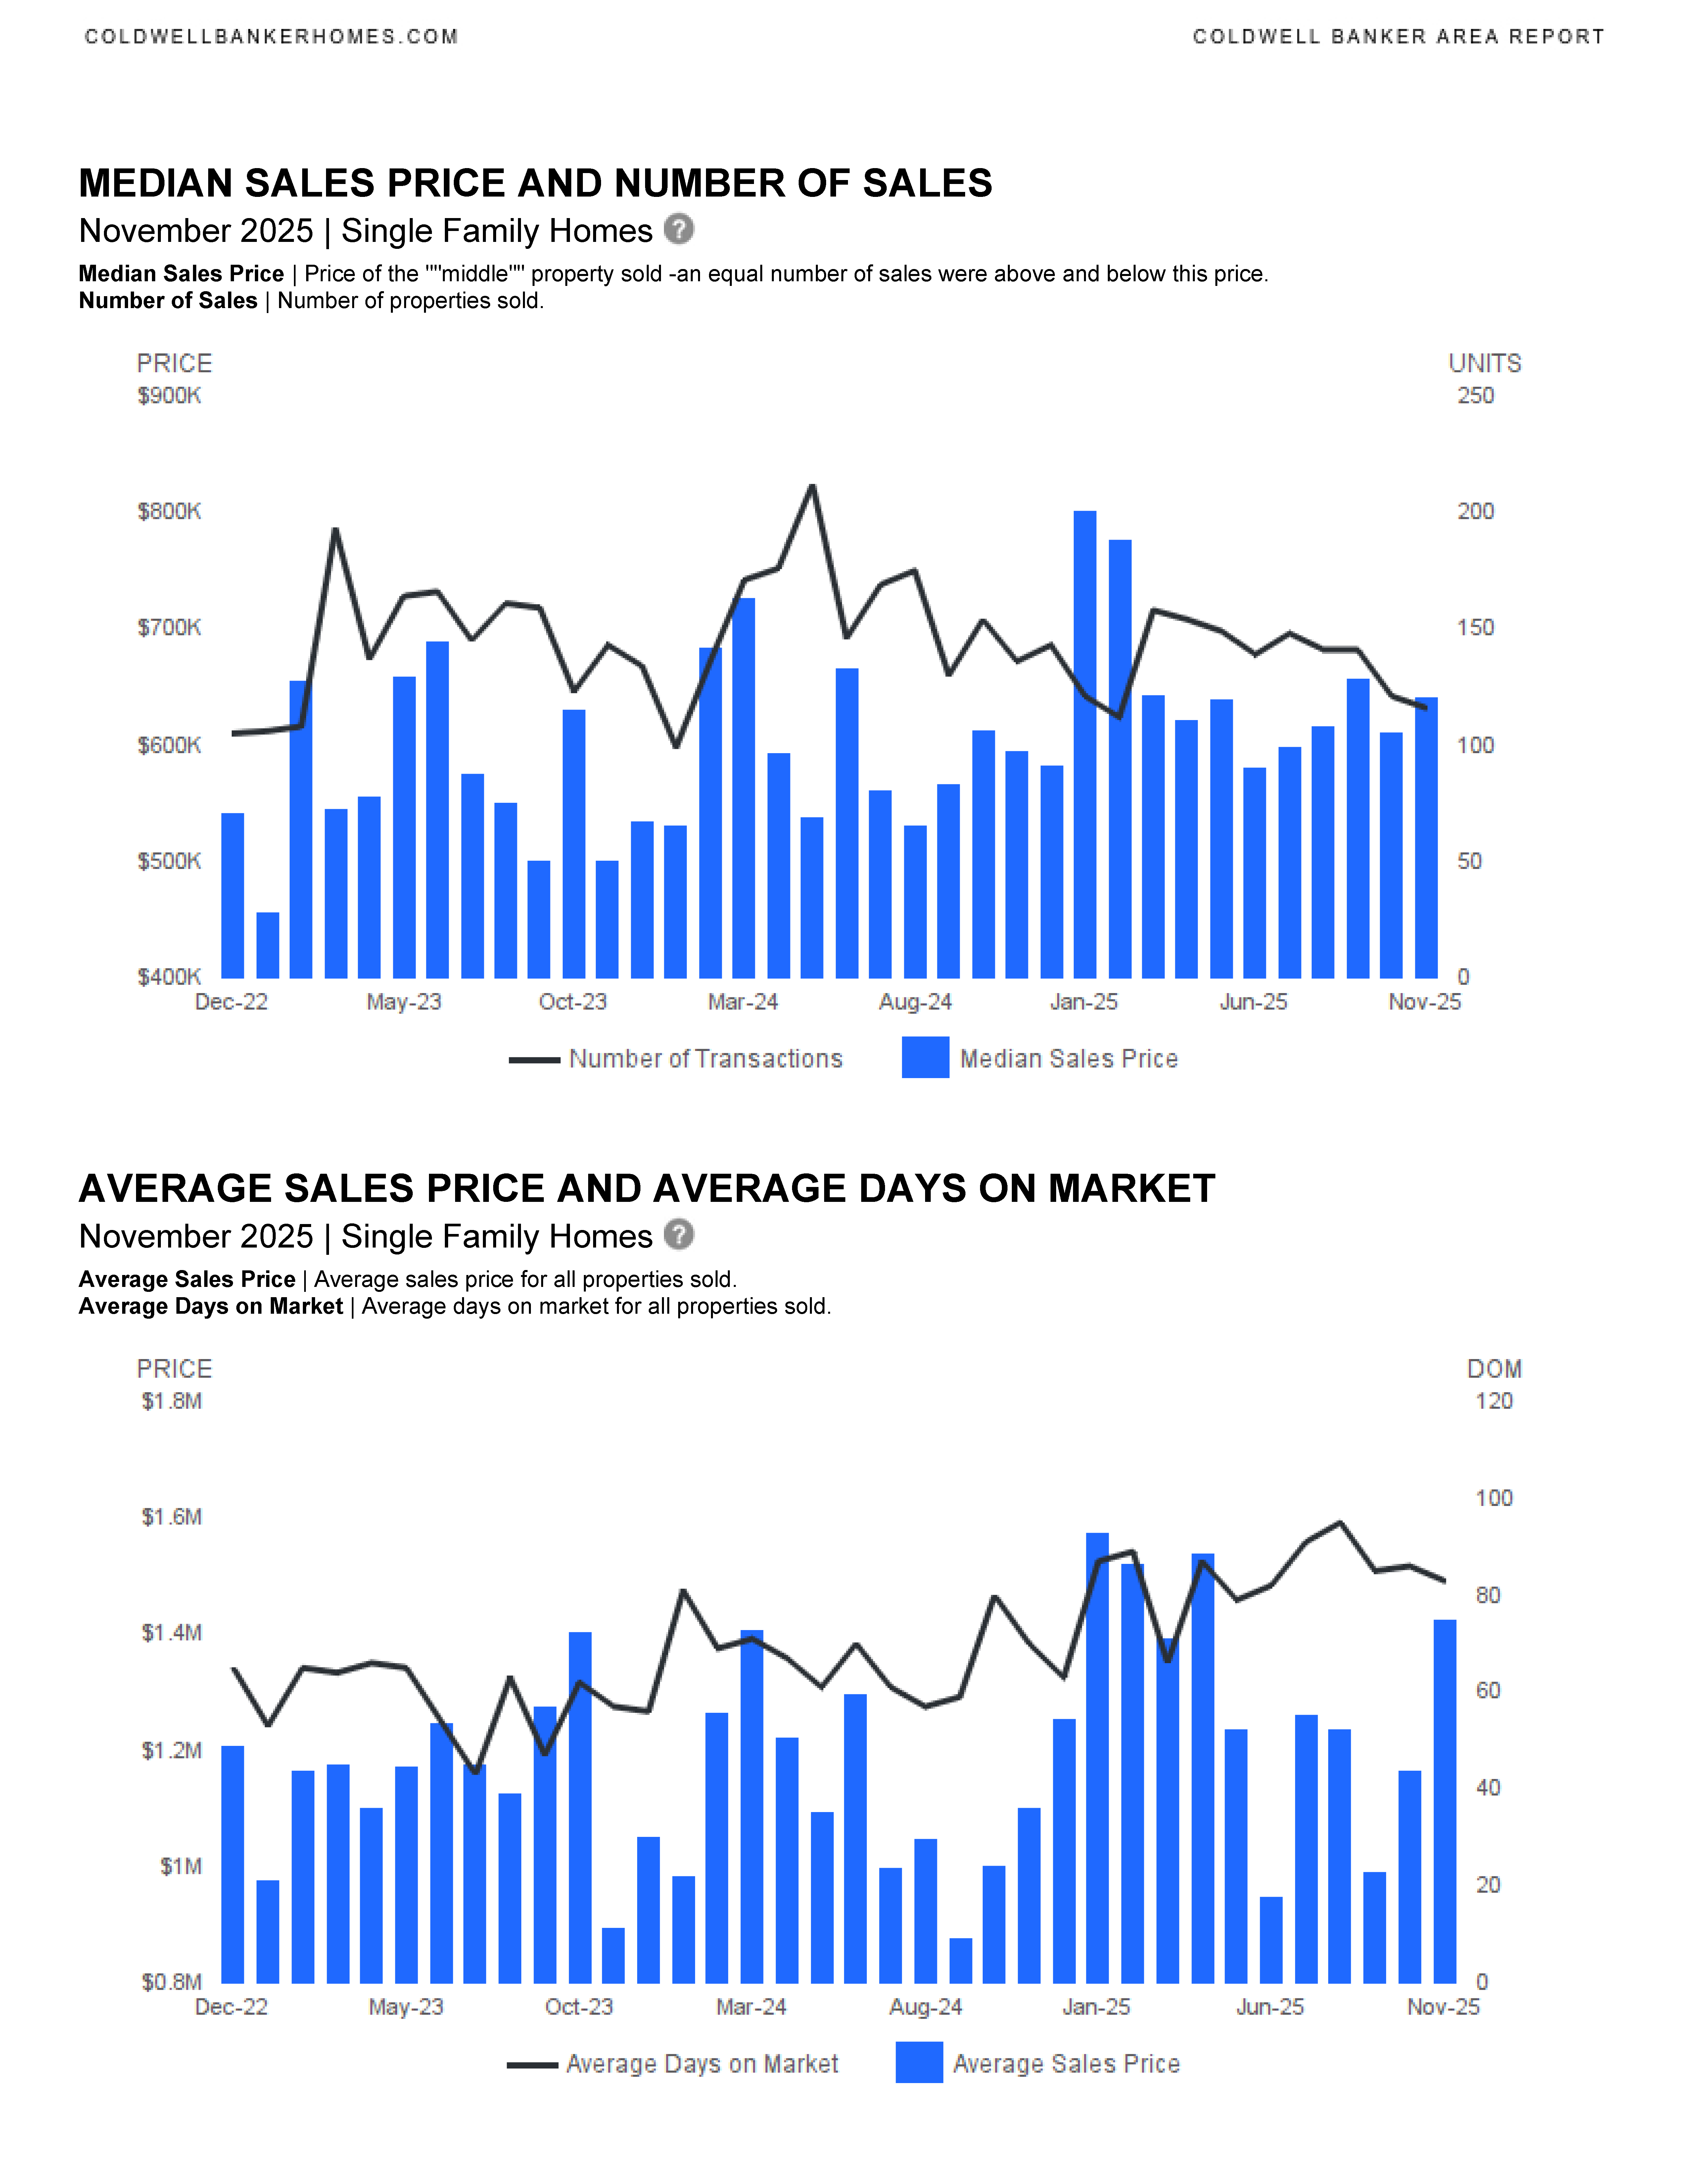
- Median Sold Price: $640,750 (↑7.8% YoY)
- Average Sold Price: $1,424,160 (↑29.8% YoY)
- Median Days on Market: 62 (↑51.2% YoY)
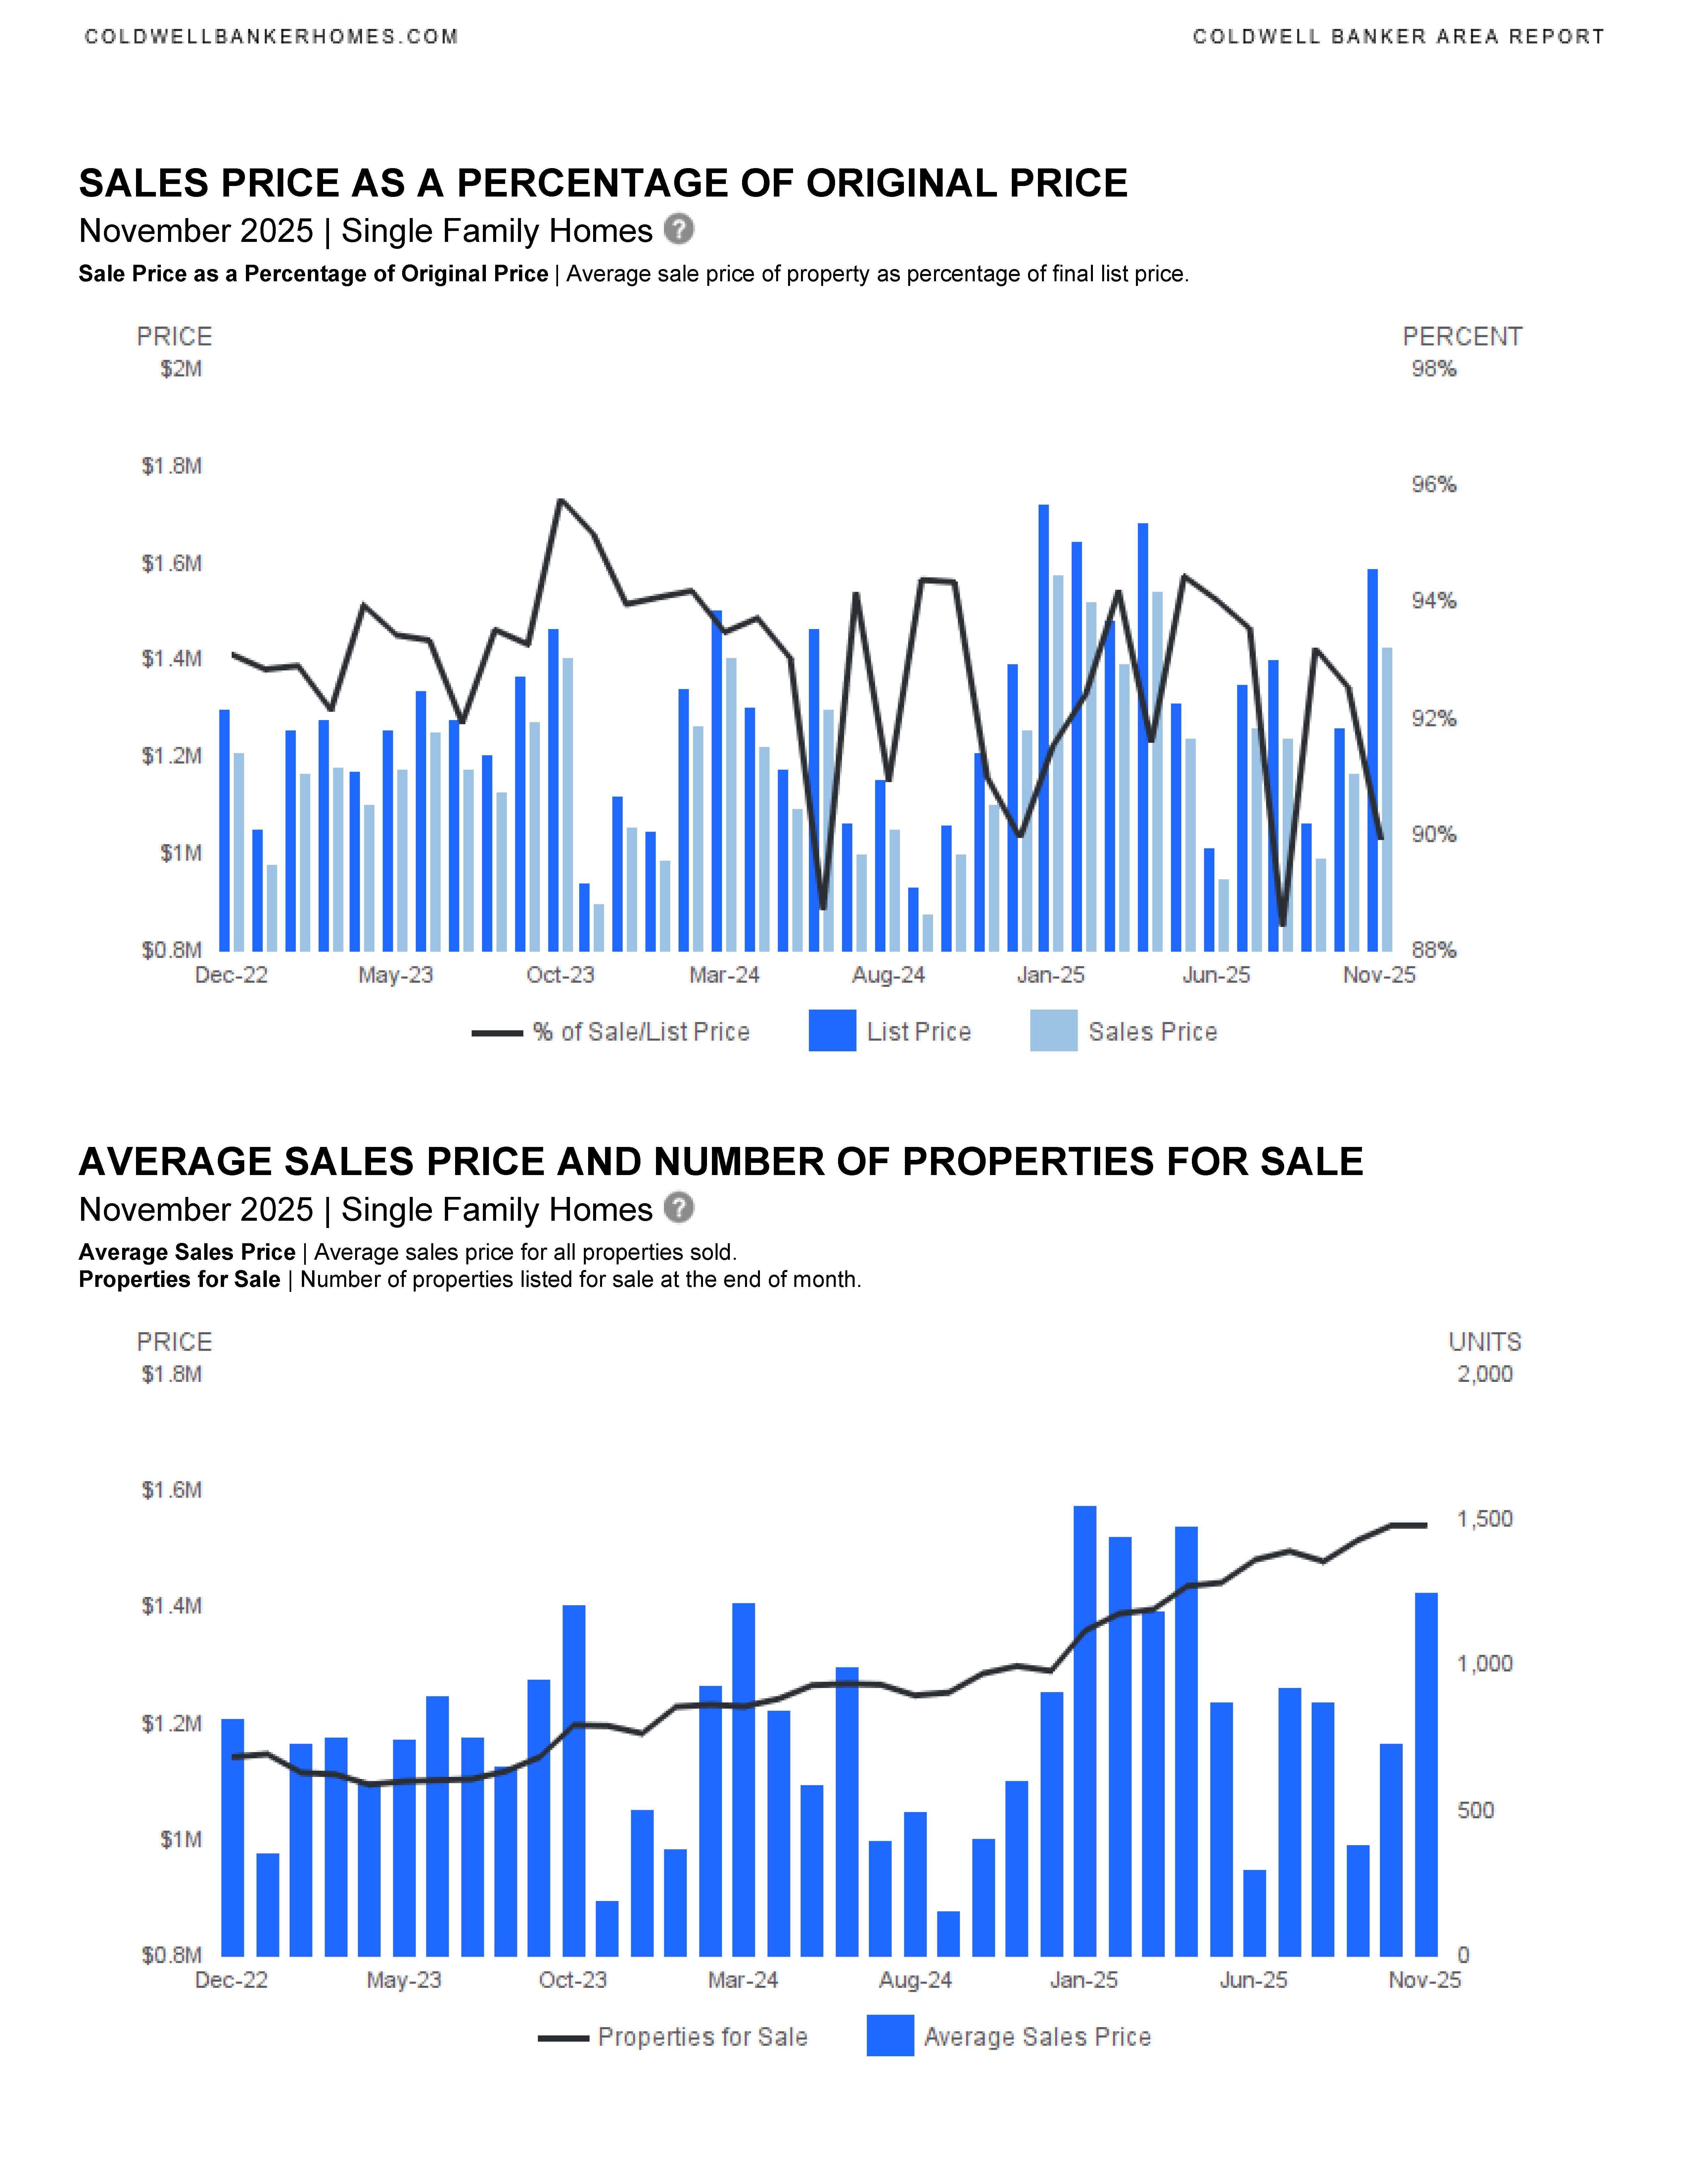
- List/Sold Price Ratio: 95.6% (stable)
- Year-to-Date: Sales down 12%, prices up ~8–15%.
Key Trend: Inventory and sales declined, but prices surged significantly, especially at the high end.
🏢Condo/Townhomes
- New Listings: 288 (↓41.8% YoY)
- Sold Listings: 104 (↓14.1% YoY)
- Median Sold Price: $410,000 (↑3.8% YoY)
- Average Sold Price: $752,766 (↑25.4% YoY)
- Median Days on Market: 87 (↑13% YoY)
- List/Sold Price Ratio: 94.4% (slightly up)
- Year-to-Date: Sales nearly flat, prices mixed (median ↓7.8%, average ↓5.1%).
Key Trend: Sharp drop in new listings, slower sales pace, but luxury segment drove average prices higher.
📊Overall Market Insights
- Inventory is tightening, with fewer new listings and longer days on market.
- Price growth is strong, especially in higher-end properties.
- Sellers still achieve ~94–96% of asking price, indicating stable demand despite slower sales.
We are in a new housing market in SE Florida. This is the time to work with an experienced and knowledgeable real estate professional. Please contact me if you would like to be sent updated market reports for YOUR specific neighborhood, Fort Lauderdale, or another SE Florida city. We can discuss the market, current trends and how we can work together to accomplish your real estate goals. I am here to help.
CONTACT ANNETTE
Let’s start working together!
Annette Dammeyer, REALTOR®, ABR®, AHWD®
Coldwell Banker Realty
901 E Las Olas Blvd STE 101, Fort Lauderdale, FL 33301
808.747.3686
SL 3535792
December 2025~ Holiday Fun, Gift Ideas, Moving Tips & More!
December 2025 NewsletterWelcome to Your December Market & Lifestyle Update!Hello, Fort Lauderdale friends and neighbors! As your local real estate resource, I’m thrilled to bring you this month’s newsletter packed with festive cheer and practical tips to make the most of the season. December is one of my favorite times in South Florida—our waterways sparkle with holiday lights, and the community comes alive with celebrations. In this newsletter, you’ll find:
And as always, I’ve included local market reports so you can stay informed about real estate trends in our area. Whether you’re buying, selling, or just curious, these insights will help you make confident decisions. Grab a cup of cocoa, settle in, and let’s dive into everything December has to offer! |
|||||||||||
National Stories
|
|||||||||||
|
|
|||||||||||
Real Estate Updates | Area Reports | October 2025
|
Thank you for letting me be part of this wonderful community—I’m here for you not just during the holidays, but all year long to help with your real estate needs. Wishing you joy, peace, and a beautiful season!
CONTACT ANNETTE
Let’s start working together!
Annette Dammeyer, REALTOR®, ABR®, AHWD®
Coldwell Banker Realty
901 E Las Olas Blvd STE 101, Fort Lauderdale, FL 33301
808.747.3686
SL 3535792
Holiday Events for December 2025
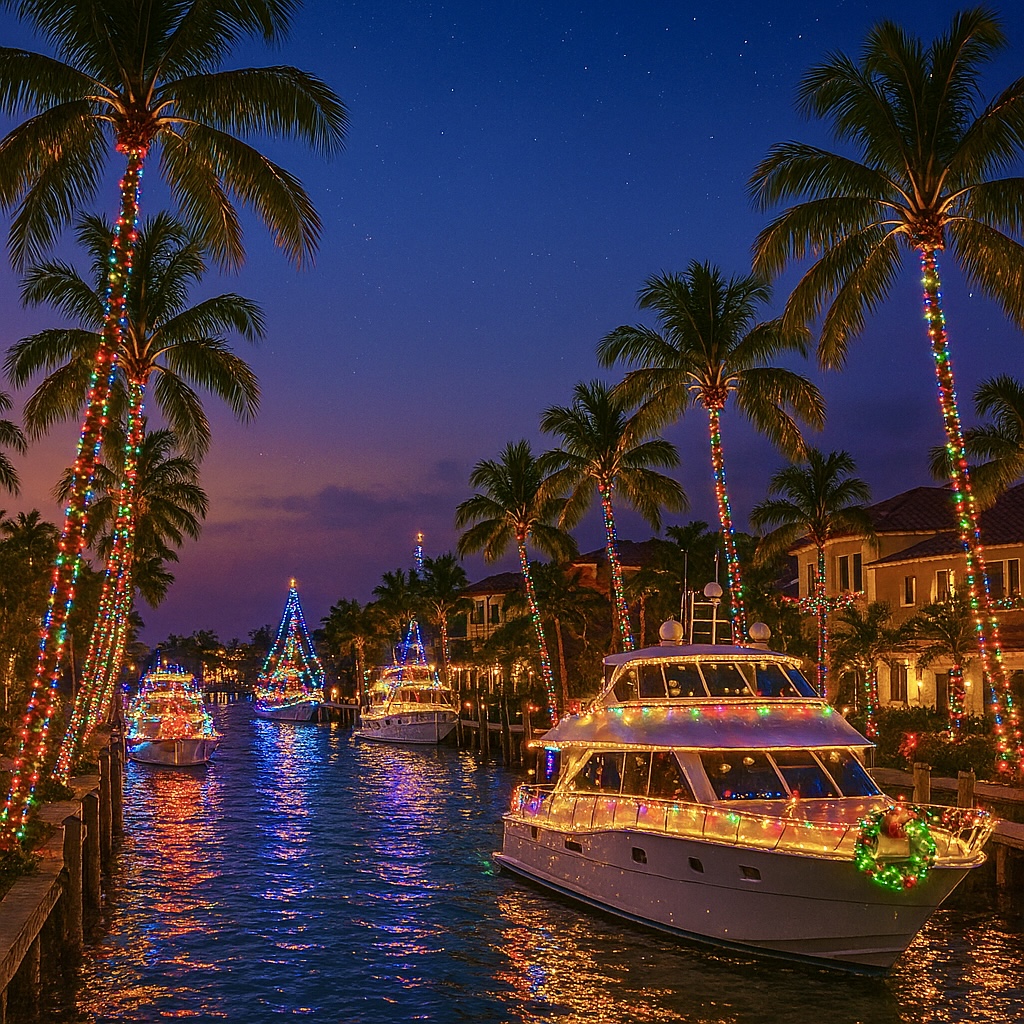
🎄 Fort Lauderdale Holiday Events 2025: Your Local Guide from a Neighbor & Realtor
🏡 As your local real estate agent, I love highlighting what makes our community special. December in Fort Lauderdale is magical—our waterways sparkle, our streets come alive, and neighbors gather to celebrate. Here’s a few popular holiday events to enjoy in and around Fort Lauderdale.
🌊 Winterfest Boat Parade – Dec 13, 2025
- “Greatest Show on H2O” with decorated yachts along the Intracoastal.
- Family-friendly viewing parties and VIP experiences.
- Lifestyle tie-in: Waterfront living means front-row seats to this tradition.
🎶 Holiday Concerts & Shows
- Trans-Siberian Orchestra – Dec 12, Amerant Bank Arena, Sunrise, FL
- The Nutcracker Ballet – Dec 18-21, 26, The Parker
- Frozen The Musical – Dec 13–Jan 4, family favorite at the Broward Center.
🎄 Parades & Festivals
- Candy Cane Parade on Hollywood Beach – Dec 6, Hollywood Broadwalk
- Light Up Sistrunk – Dec 5, cultural celebration, Sistrunk Blvd
- Victorian Christmas at Stranahan House – Dec 16–20.
🕎 Hanukkah Celebration
- Menorah Lighting on Las Olas Boulevard – Dec 14, Las Olas Oceanside Park
🎉 New Year’s Eve Festivities
- Downtown Countdown on Las Olas – Street parties, fireworks, live music.
- Beachfront Fireworks – Ring in 2026 by the ocean, multiple locations including Shooters, Four Seasons and B Ocean
📌 Local Realtor Insight
- Holiday events showcase why Fort Lauderdale is more than a place to live—it’s a lifestyle.
- Buyers love neighborhoods with walkable access to celebrations.
- Sellers benefit from highlighting proximity to cultural and seasonal events.
December 2025 is packed with festive magic in Fort Lauderdale. Whether you’re enjoying the Winterfest Boat Parade or ringing in the new year on Las Olas, these events remind us why Southeast Florida is one of the most desirable places to call home. Please reach out if you are looking to complete a residential transaction, I am here to help.
CONTACT ANNETTE
Let’s start working together!
Annette Dammeyer, REALTOR®, ABR®, AHWD®
Coldwell Banker Realty
901 E Las Olas Blvd STE 101, Fort Lauderdale, FL 33301
808.747.3686
SL 3535792
Fort Lauderdale October 2025 Area Report
Fort Lauderdale October 2025 real estate statistics have been published.
Fort Lauderdale Area Reports
Single Family Homes
Condominium & Townhouses
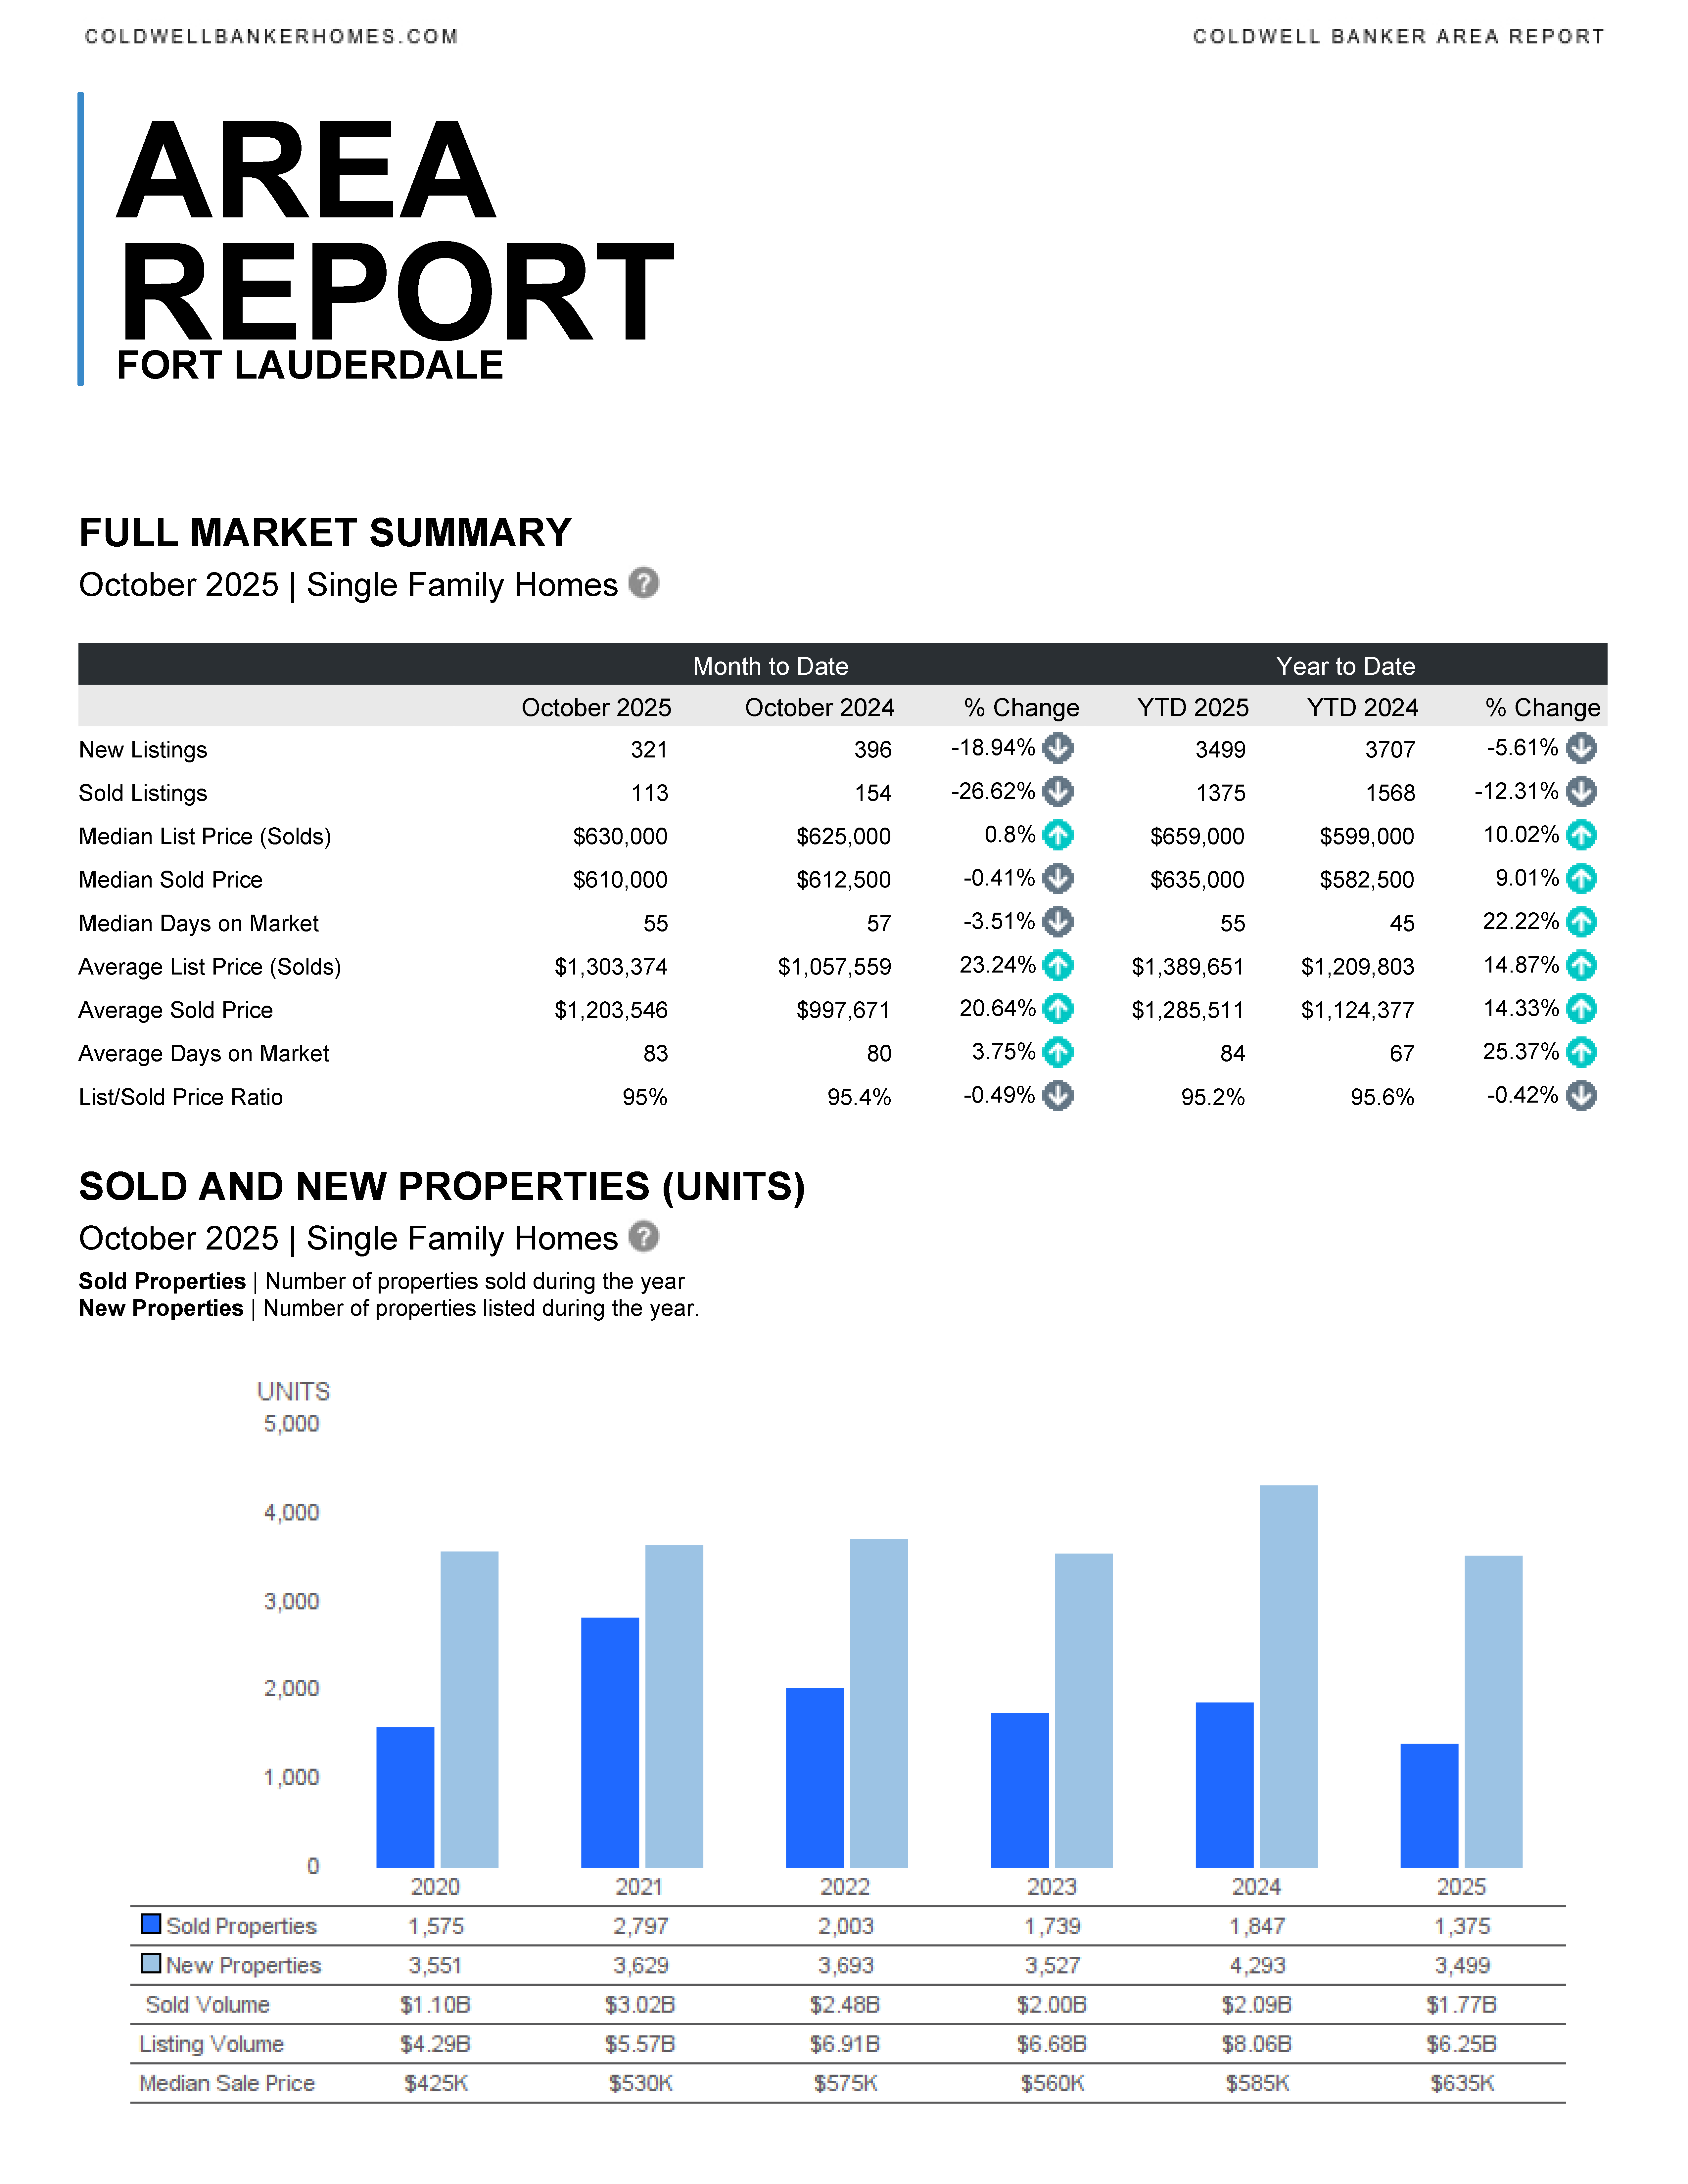
Fort Lauderdale Real Estate Market Summary – October 2025
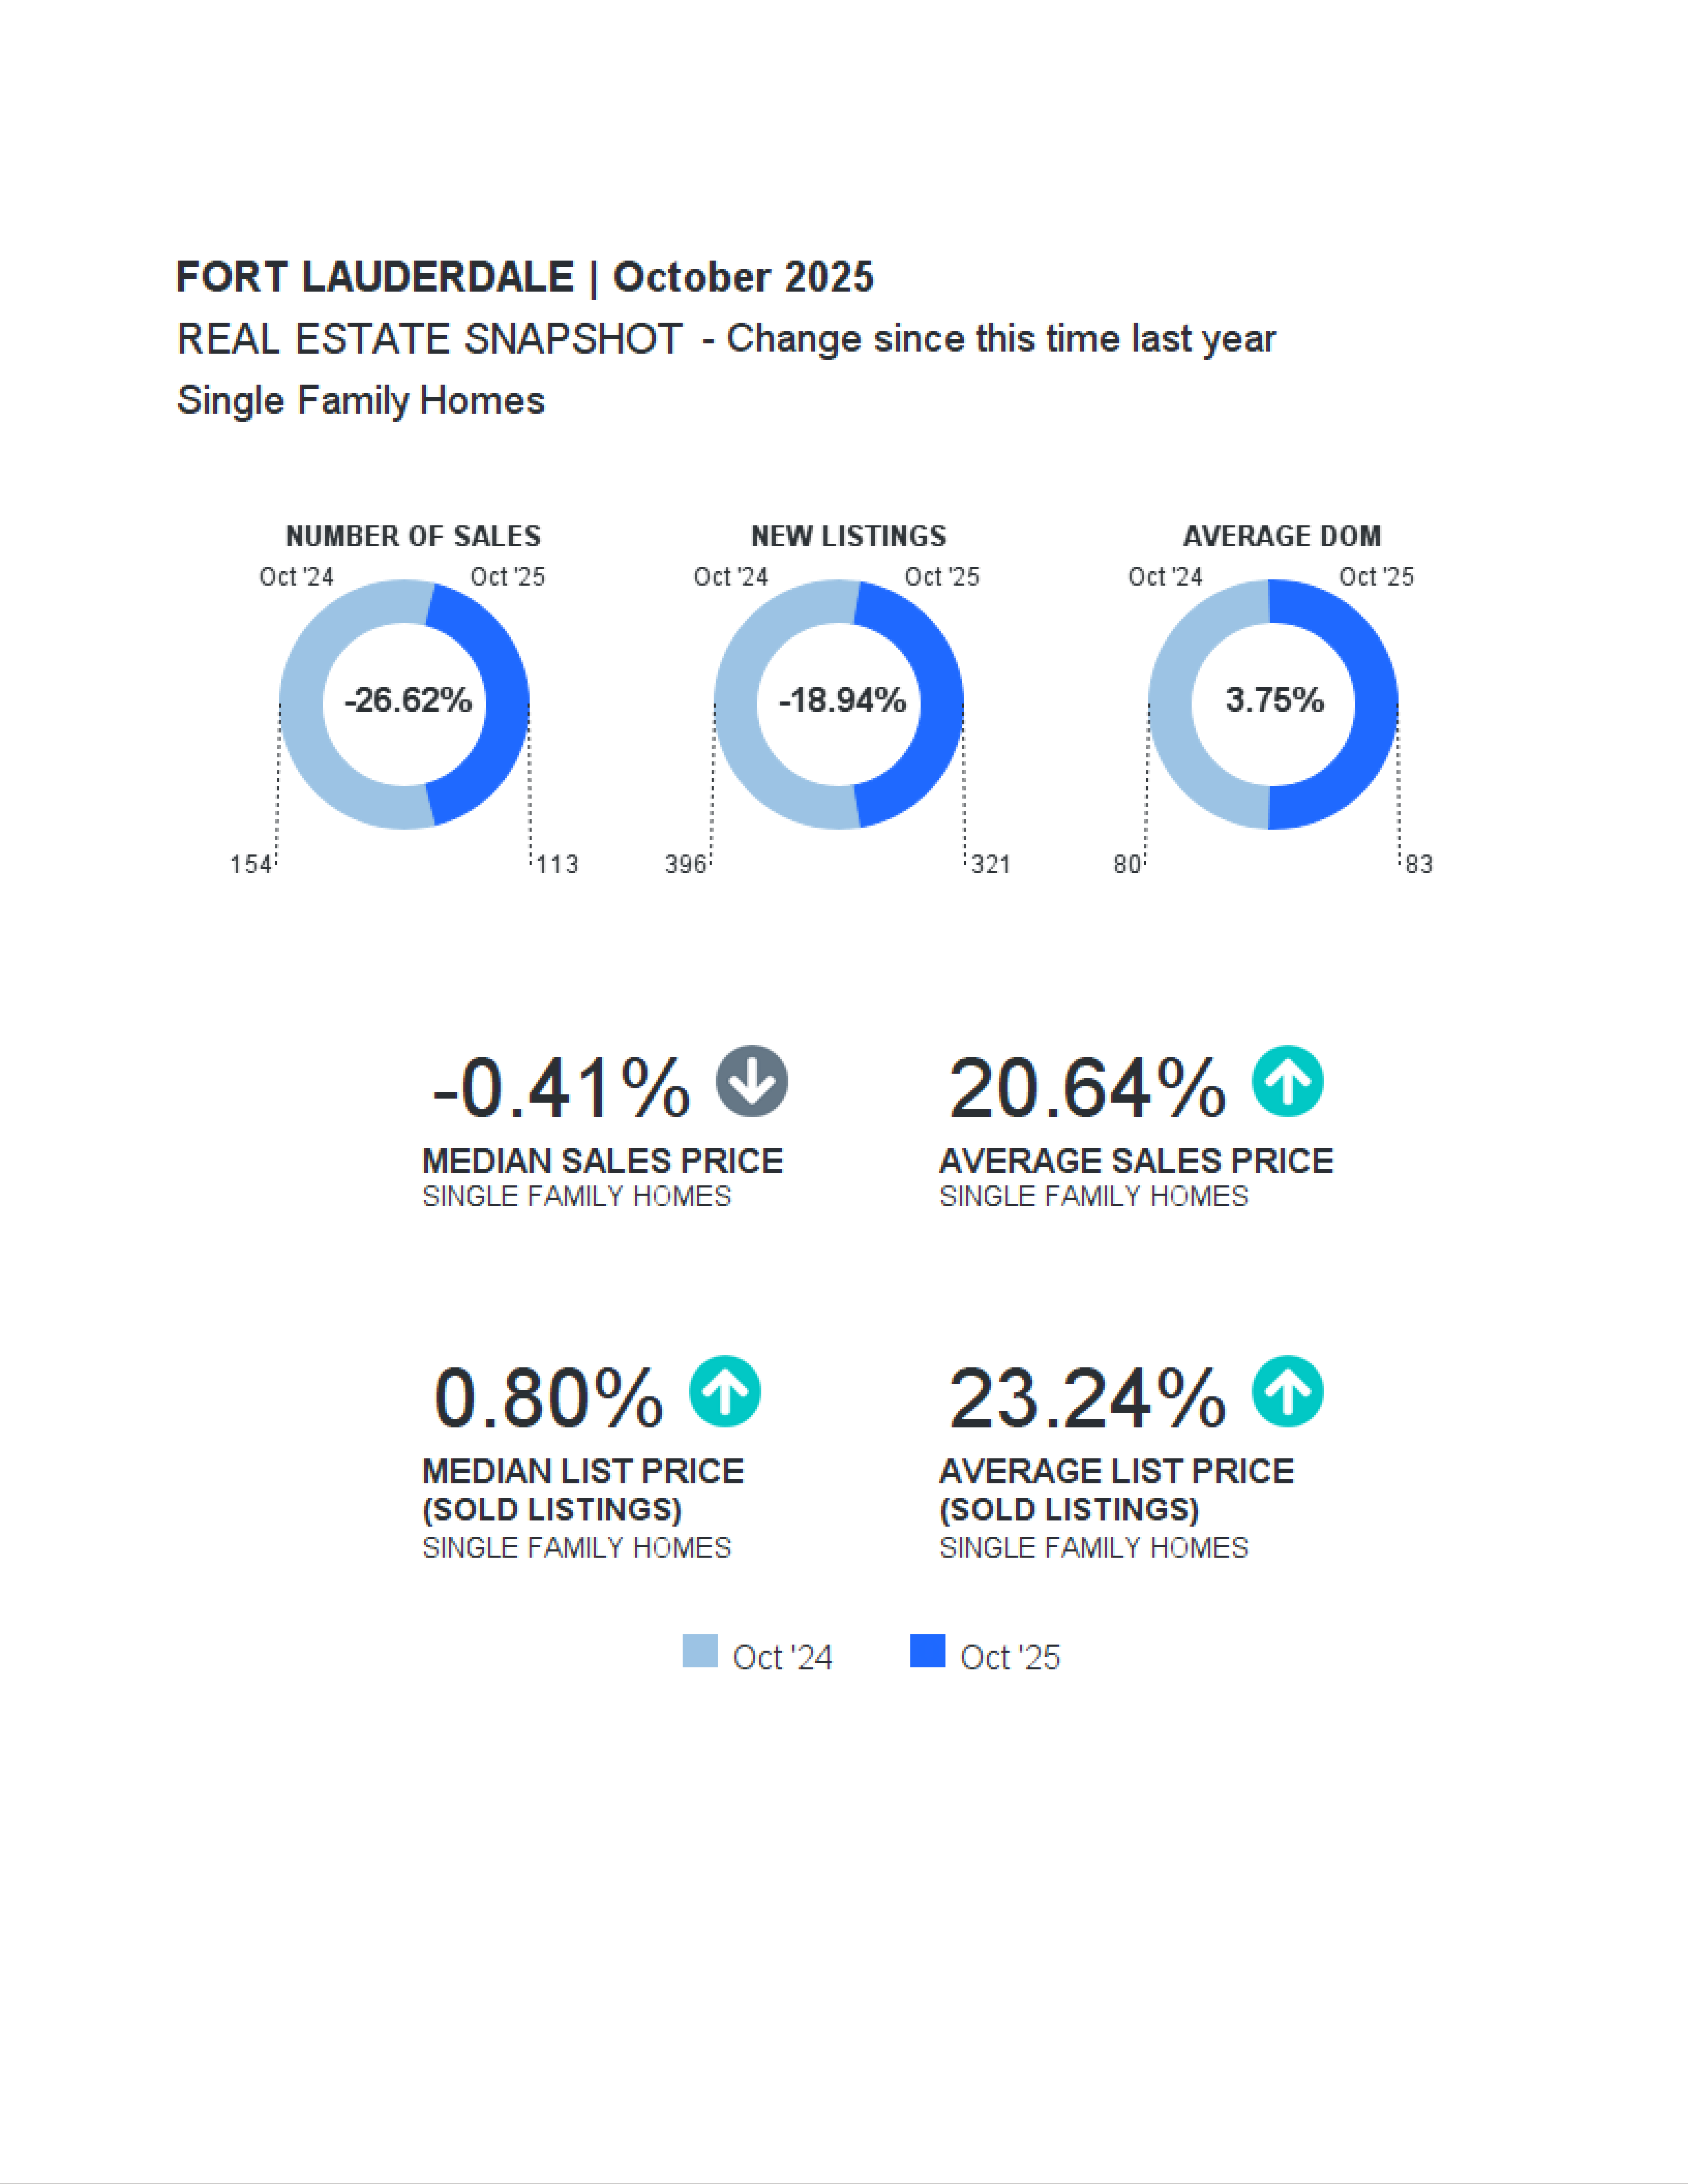
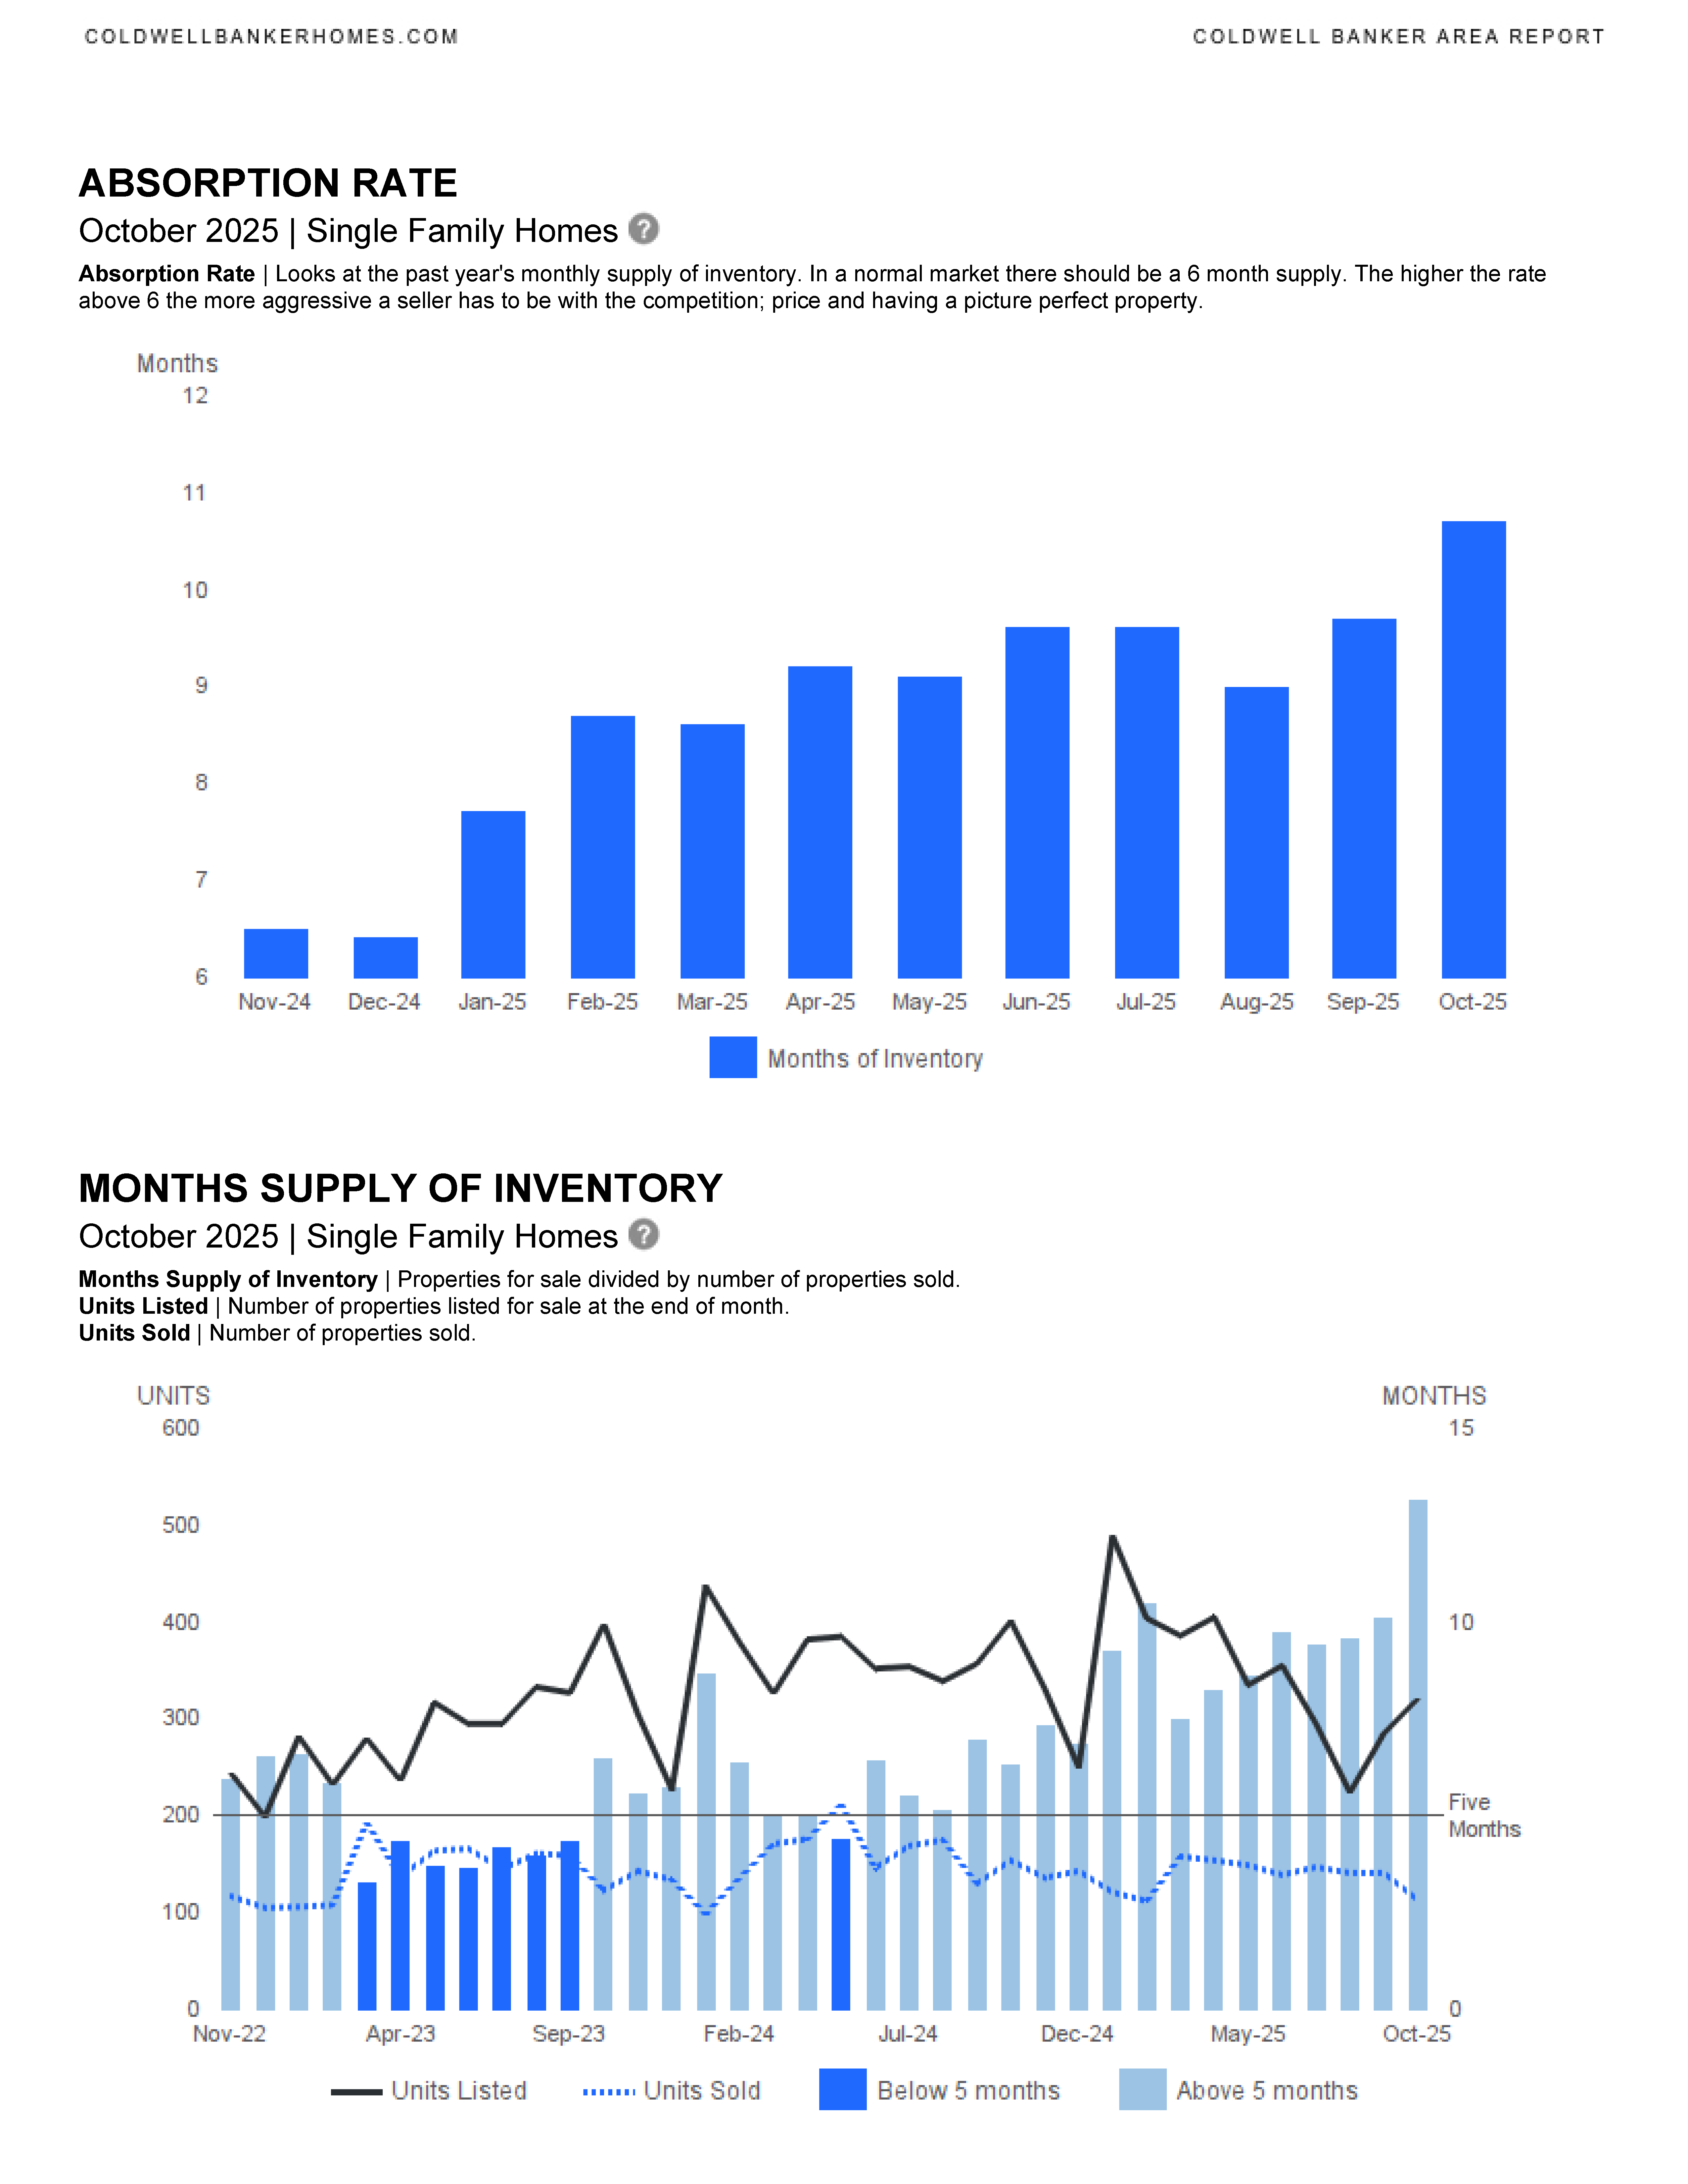
🏡 Single Family Homes – October 2025 Highlights
Monthly Changes (vs. October 2024):
- New Listings: 321 (⬇️ 18.9%)
- Sold Listings: 113 (⬇️ 26.6%)
- Median List Price (Solds): $630,000 (⬆️ 0.8%)
- Median Sold Price: $610,000 (⬇️ 0.4%)
- Average Sold Price: $1,203,546 (⬆️ 20.6%)
- Average Days on Market: 83 days (⬆️ 3.75%)
- List-to-Sale Price Ratio: 95% (slightly down)
Year-to-Date (YTD) Changes:
- New Listings: 3,499 (⬇️ 5.6%)
- Sold Listings: 1,375 (⬇️ 12.3%)
- Median Sold Price: $635,000 (⬆️ 9%)
- Average Sold Price: $1,285,511 (⬆️ 14.3%)
- Average Days on Market: 84 days (⬆️ 25.4%)
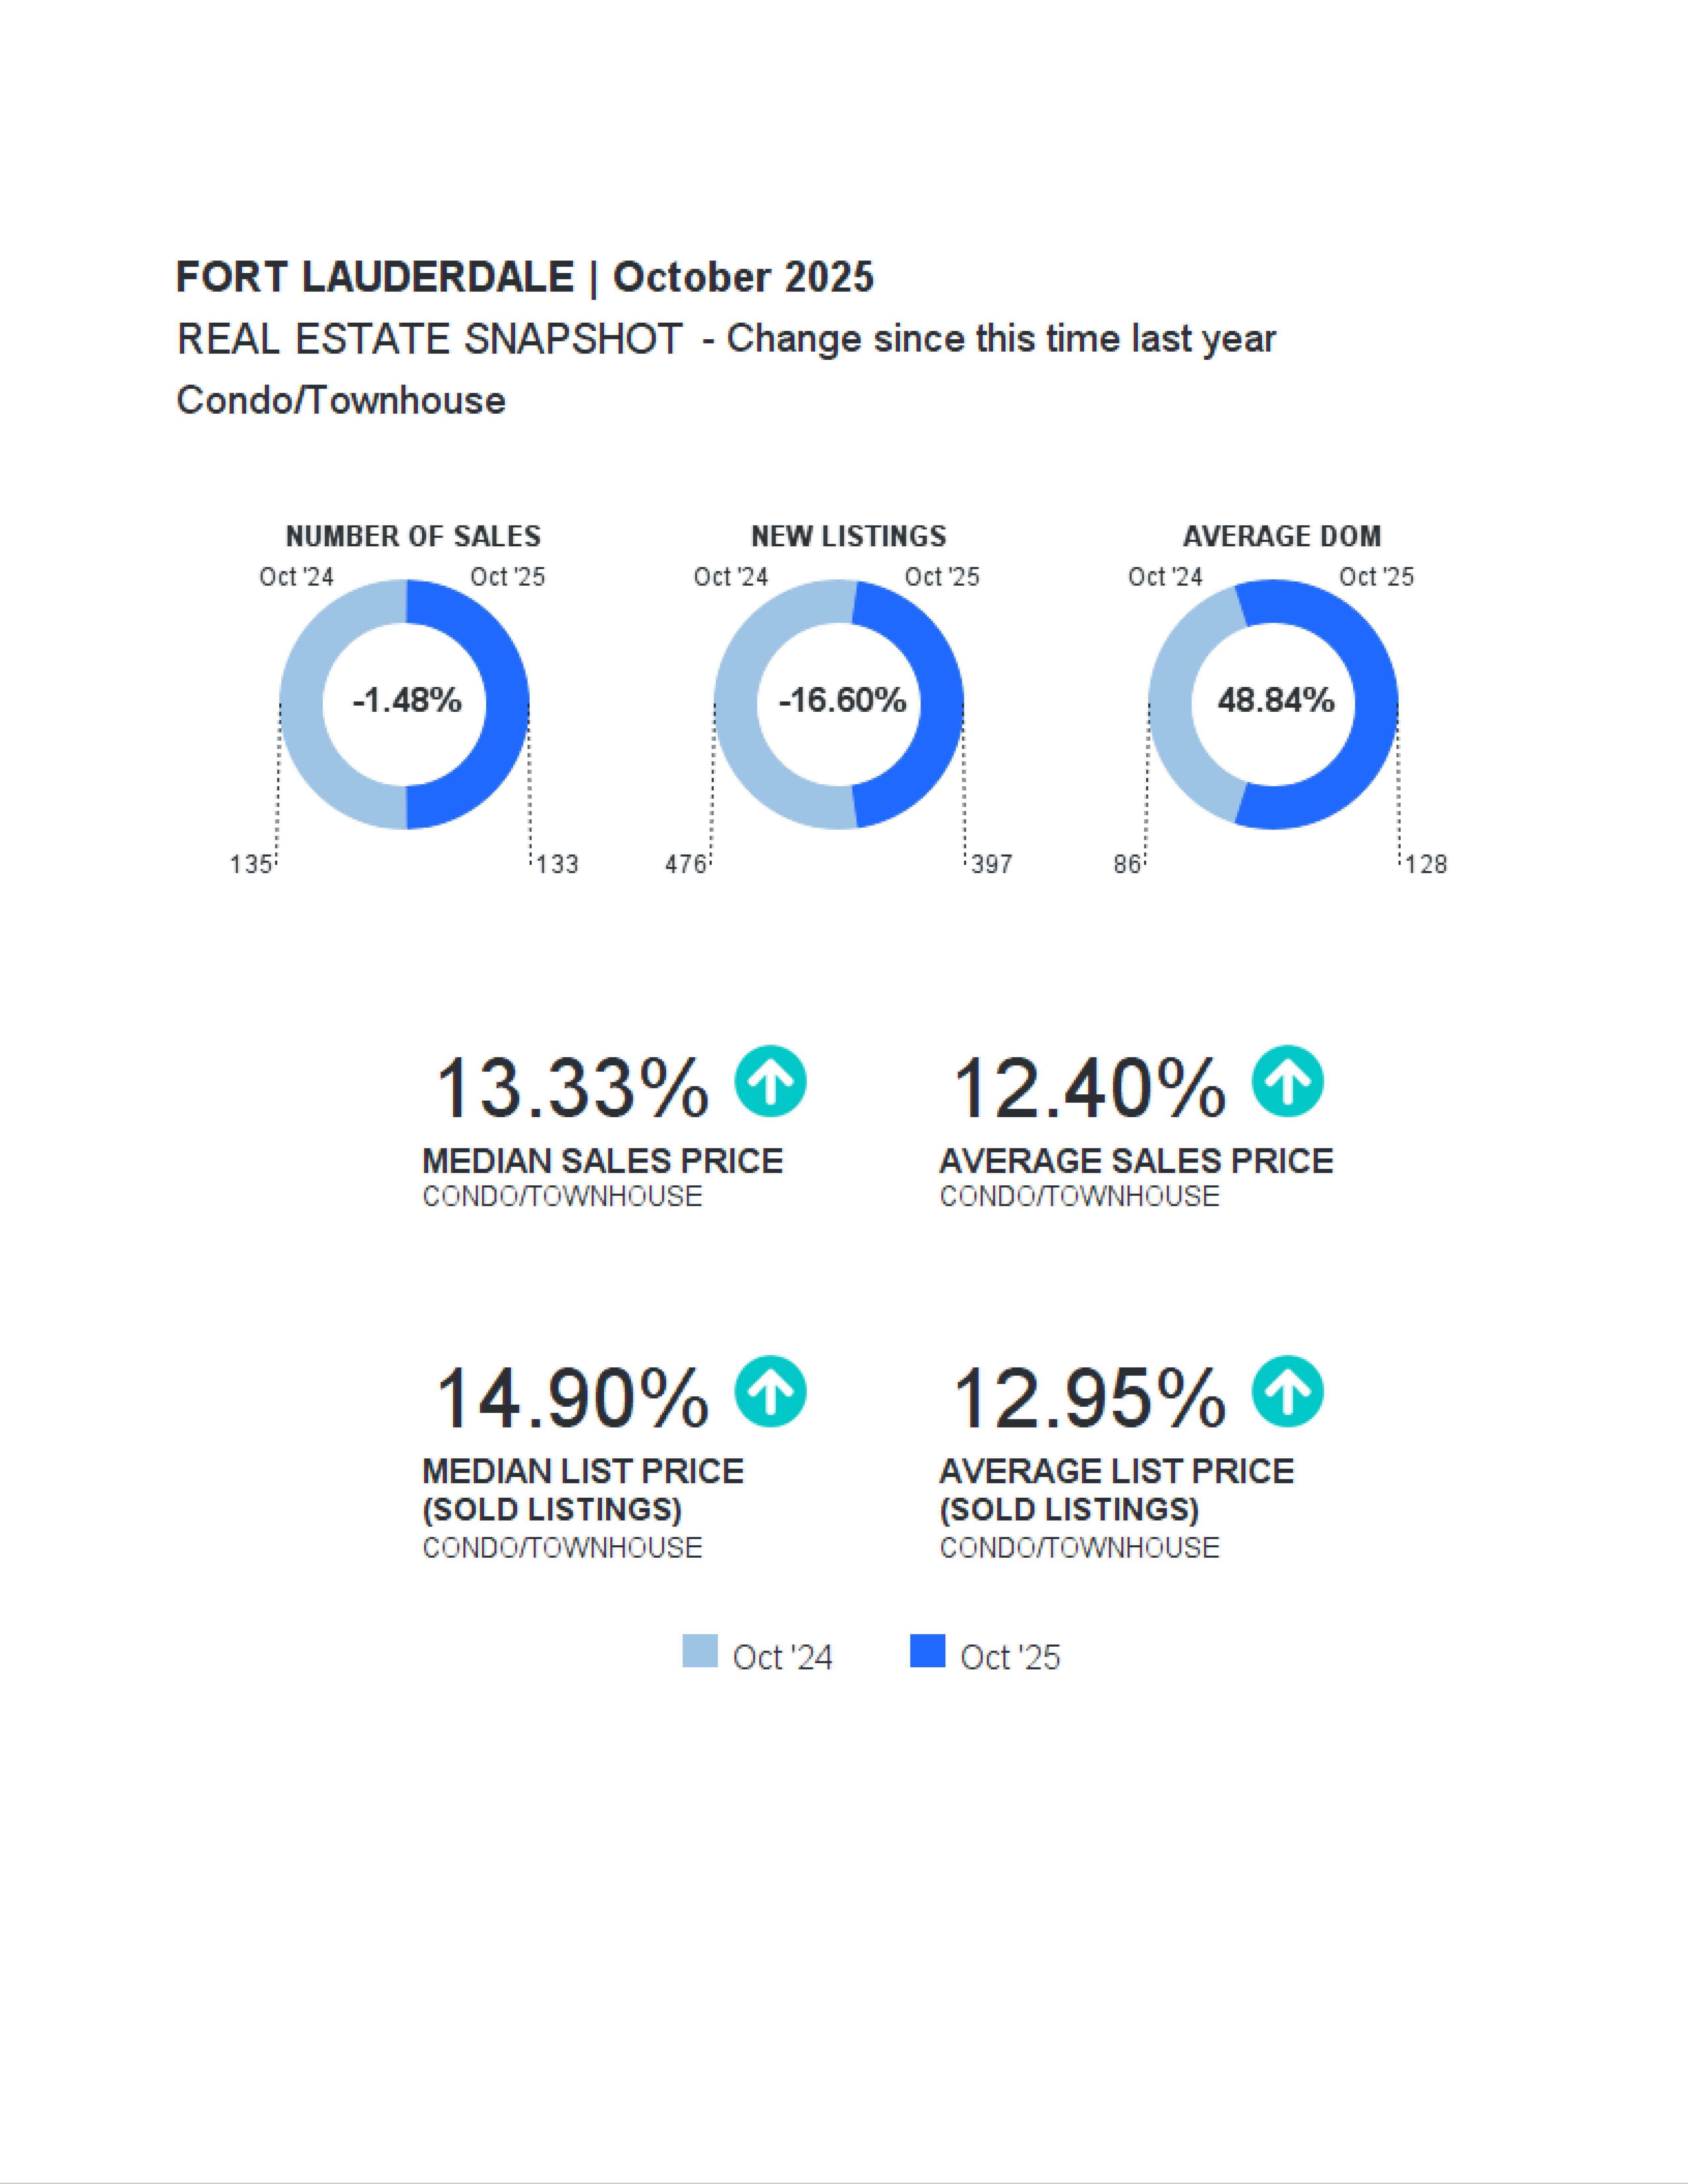
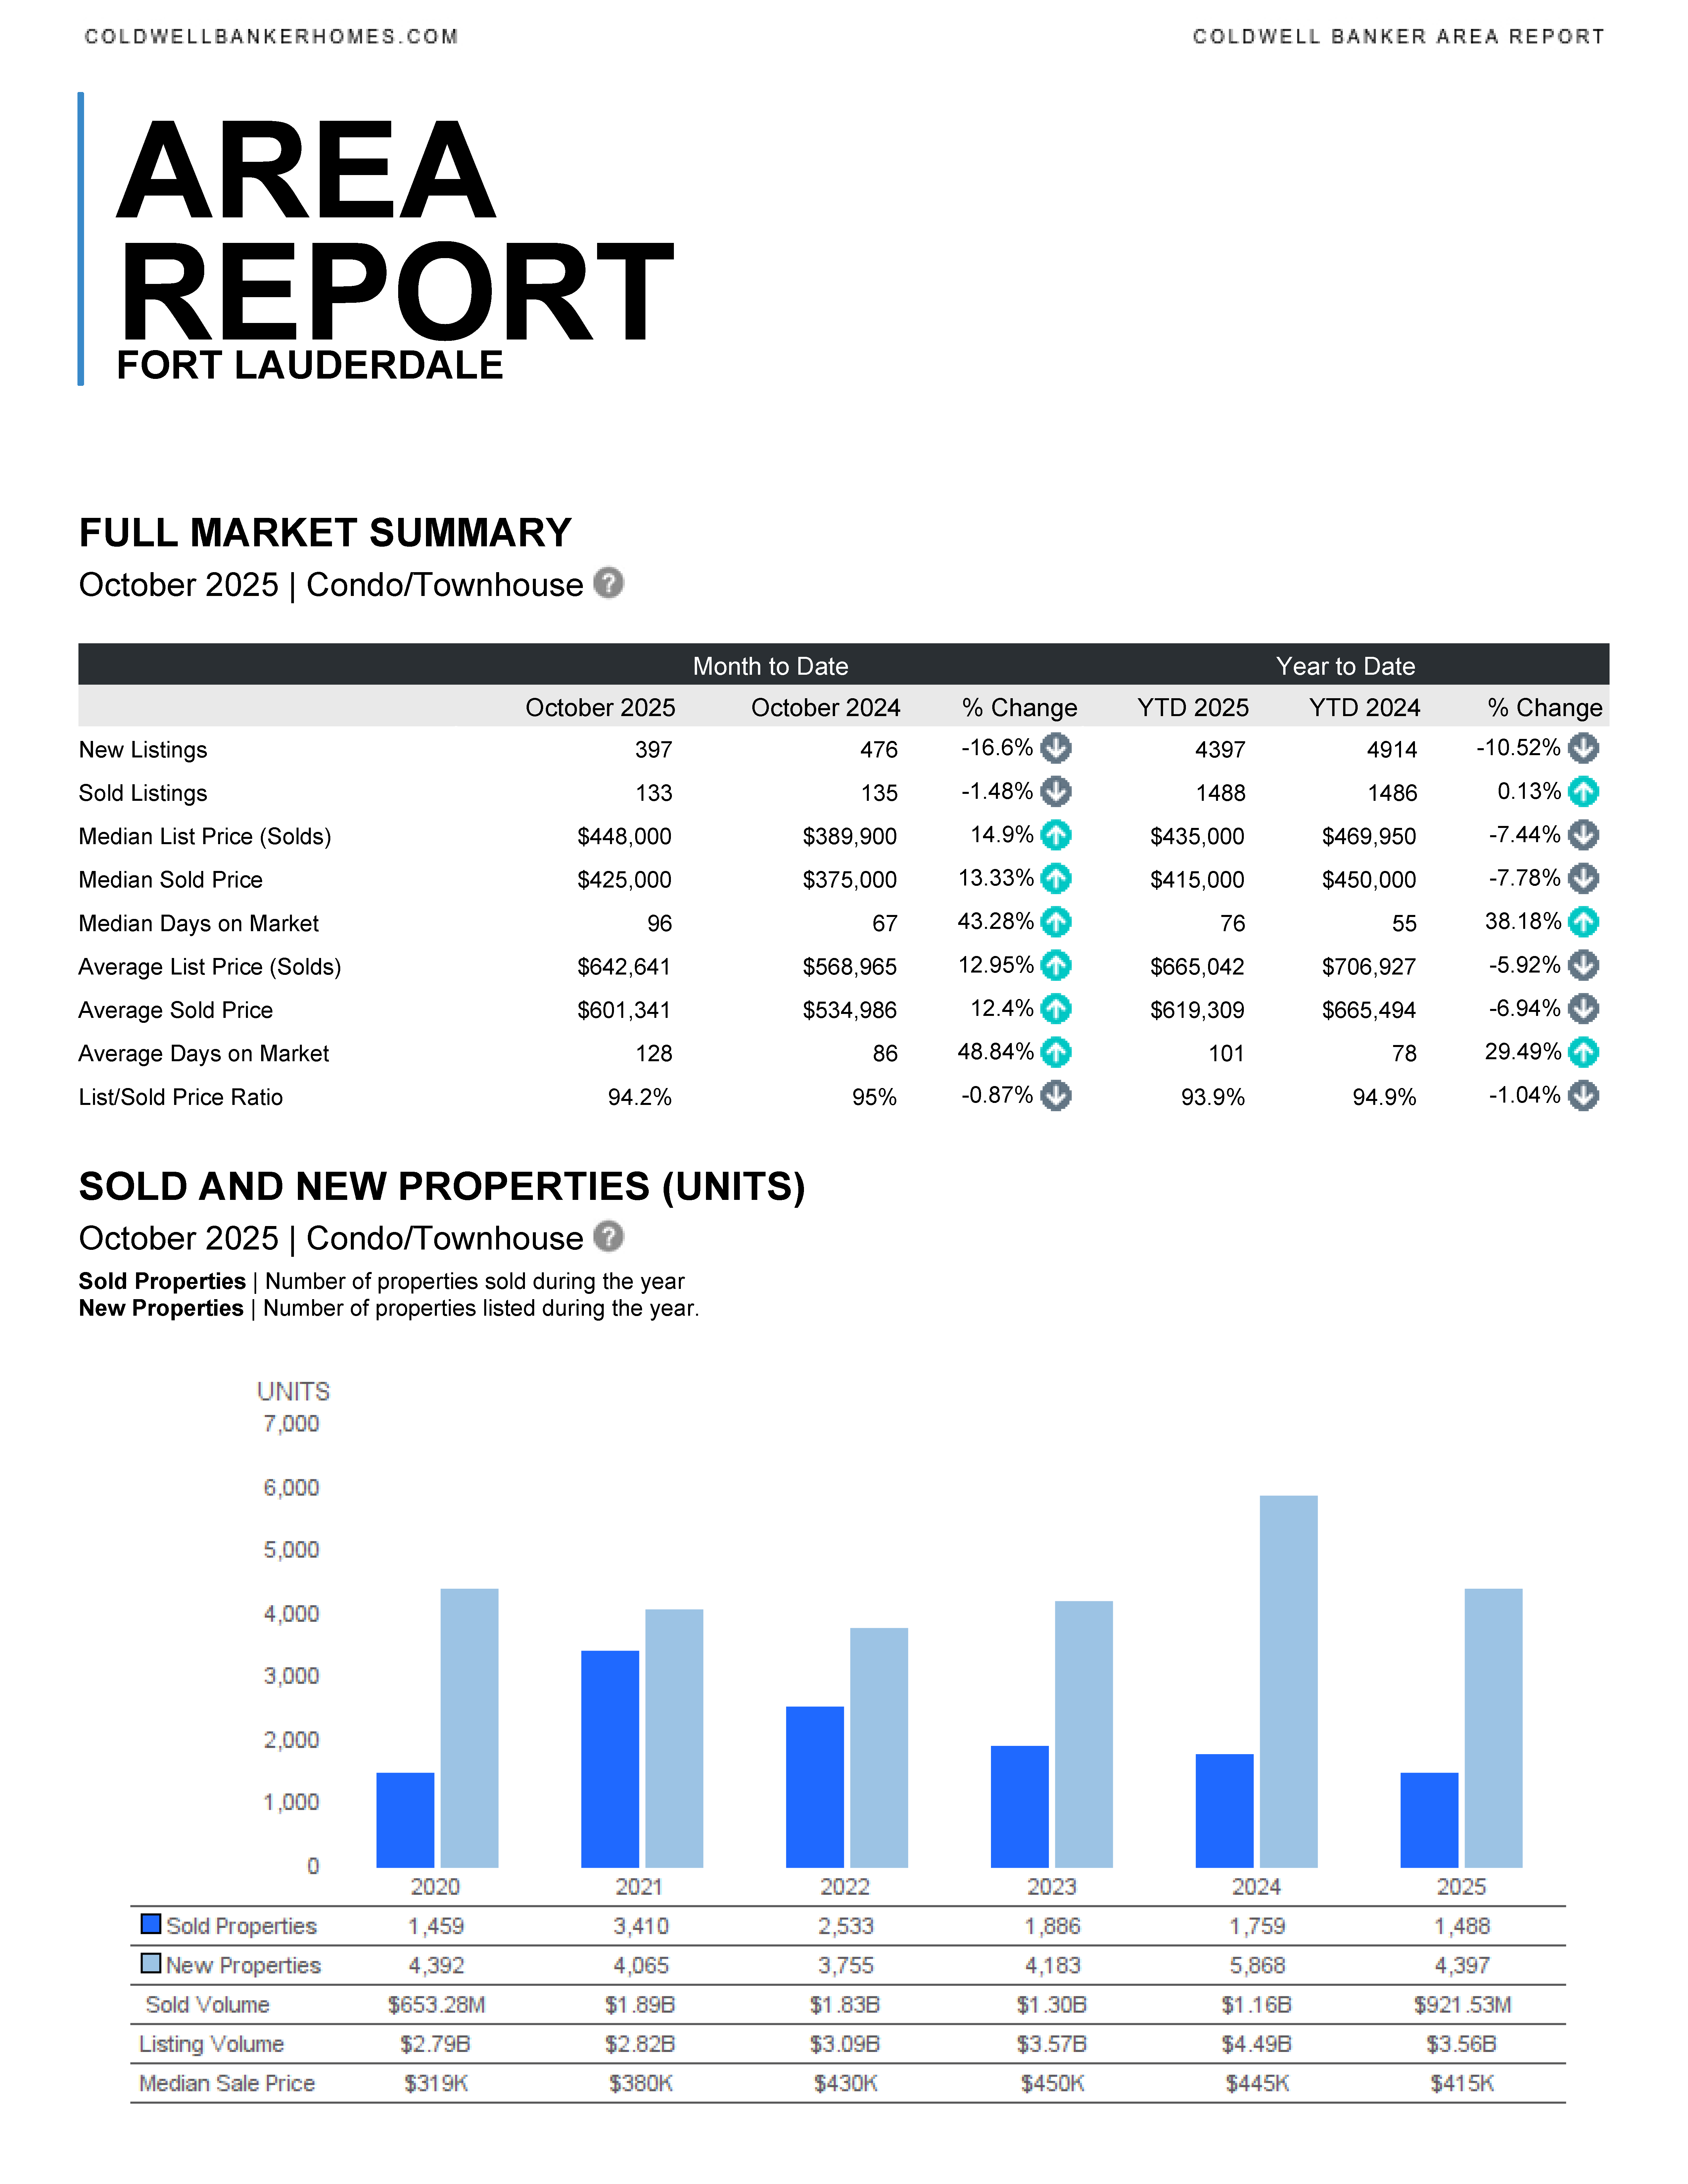
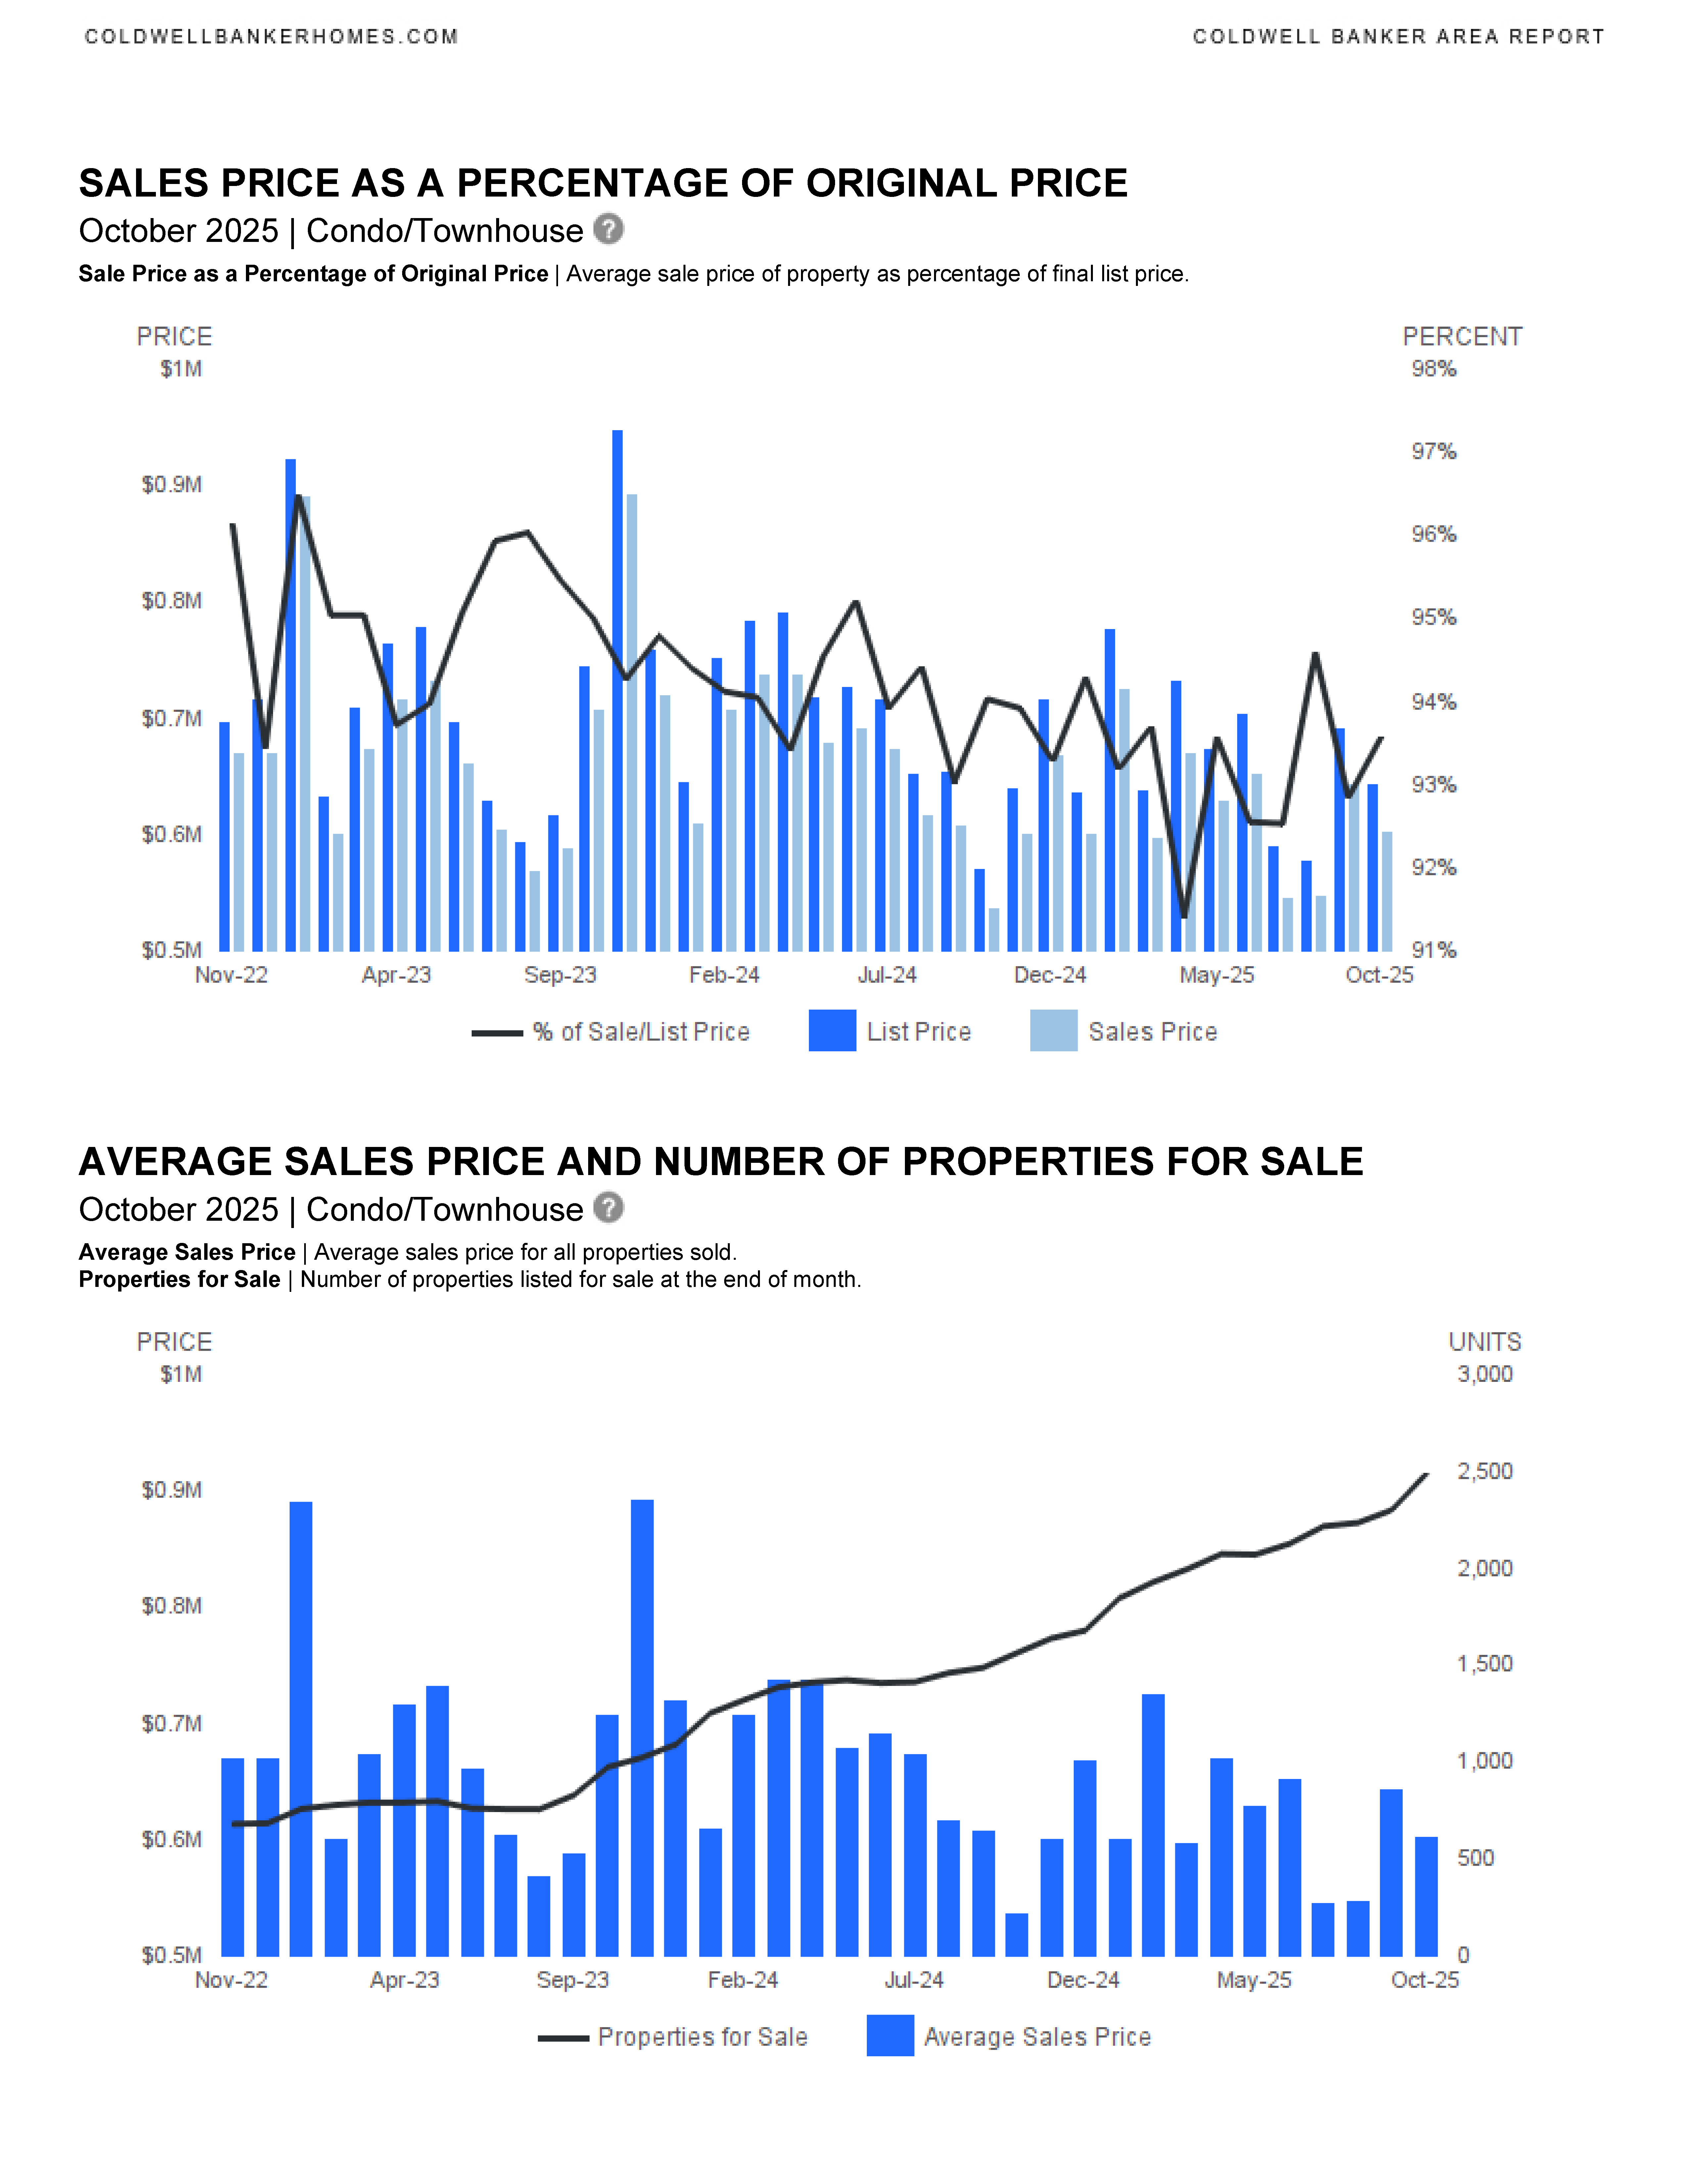
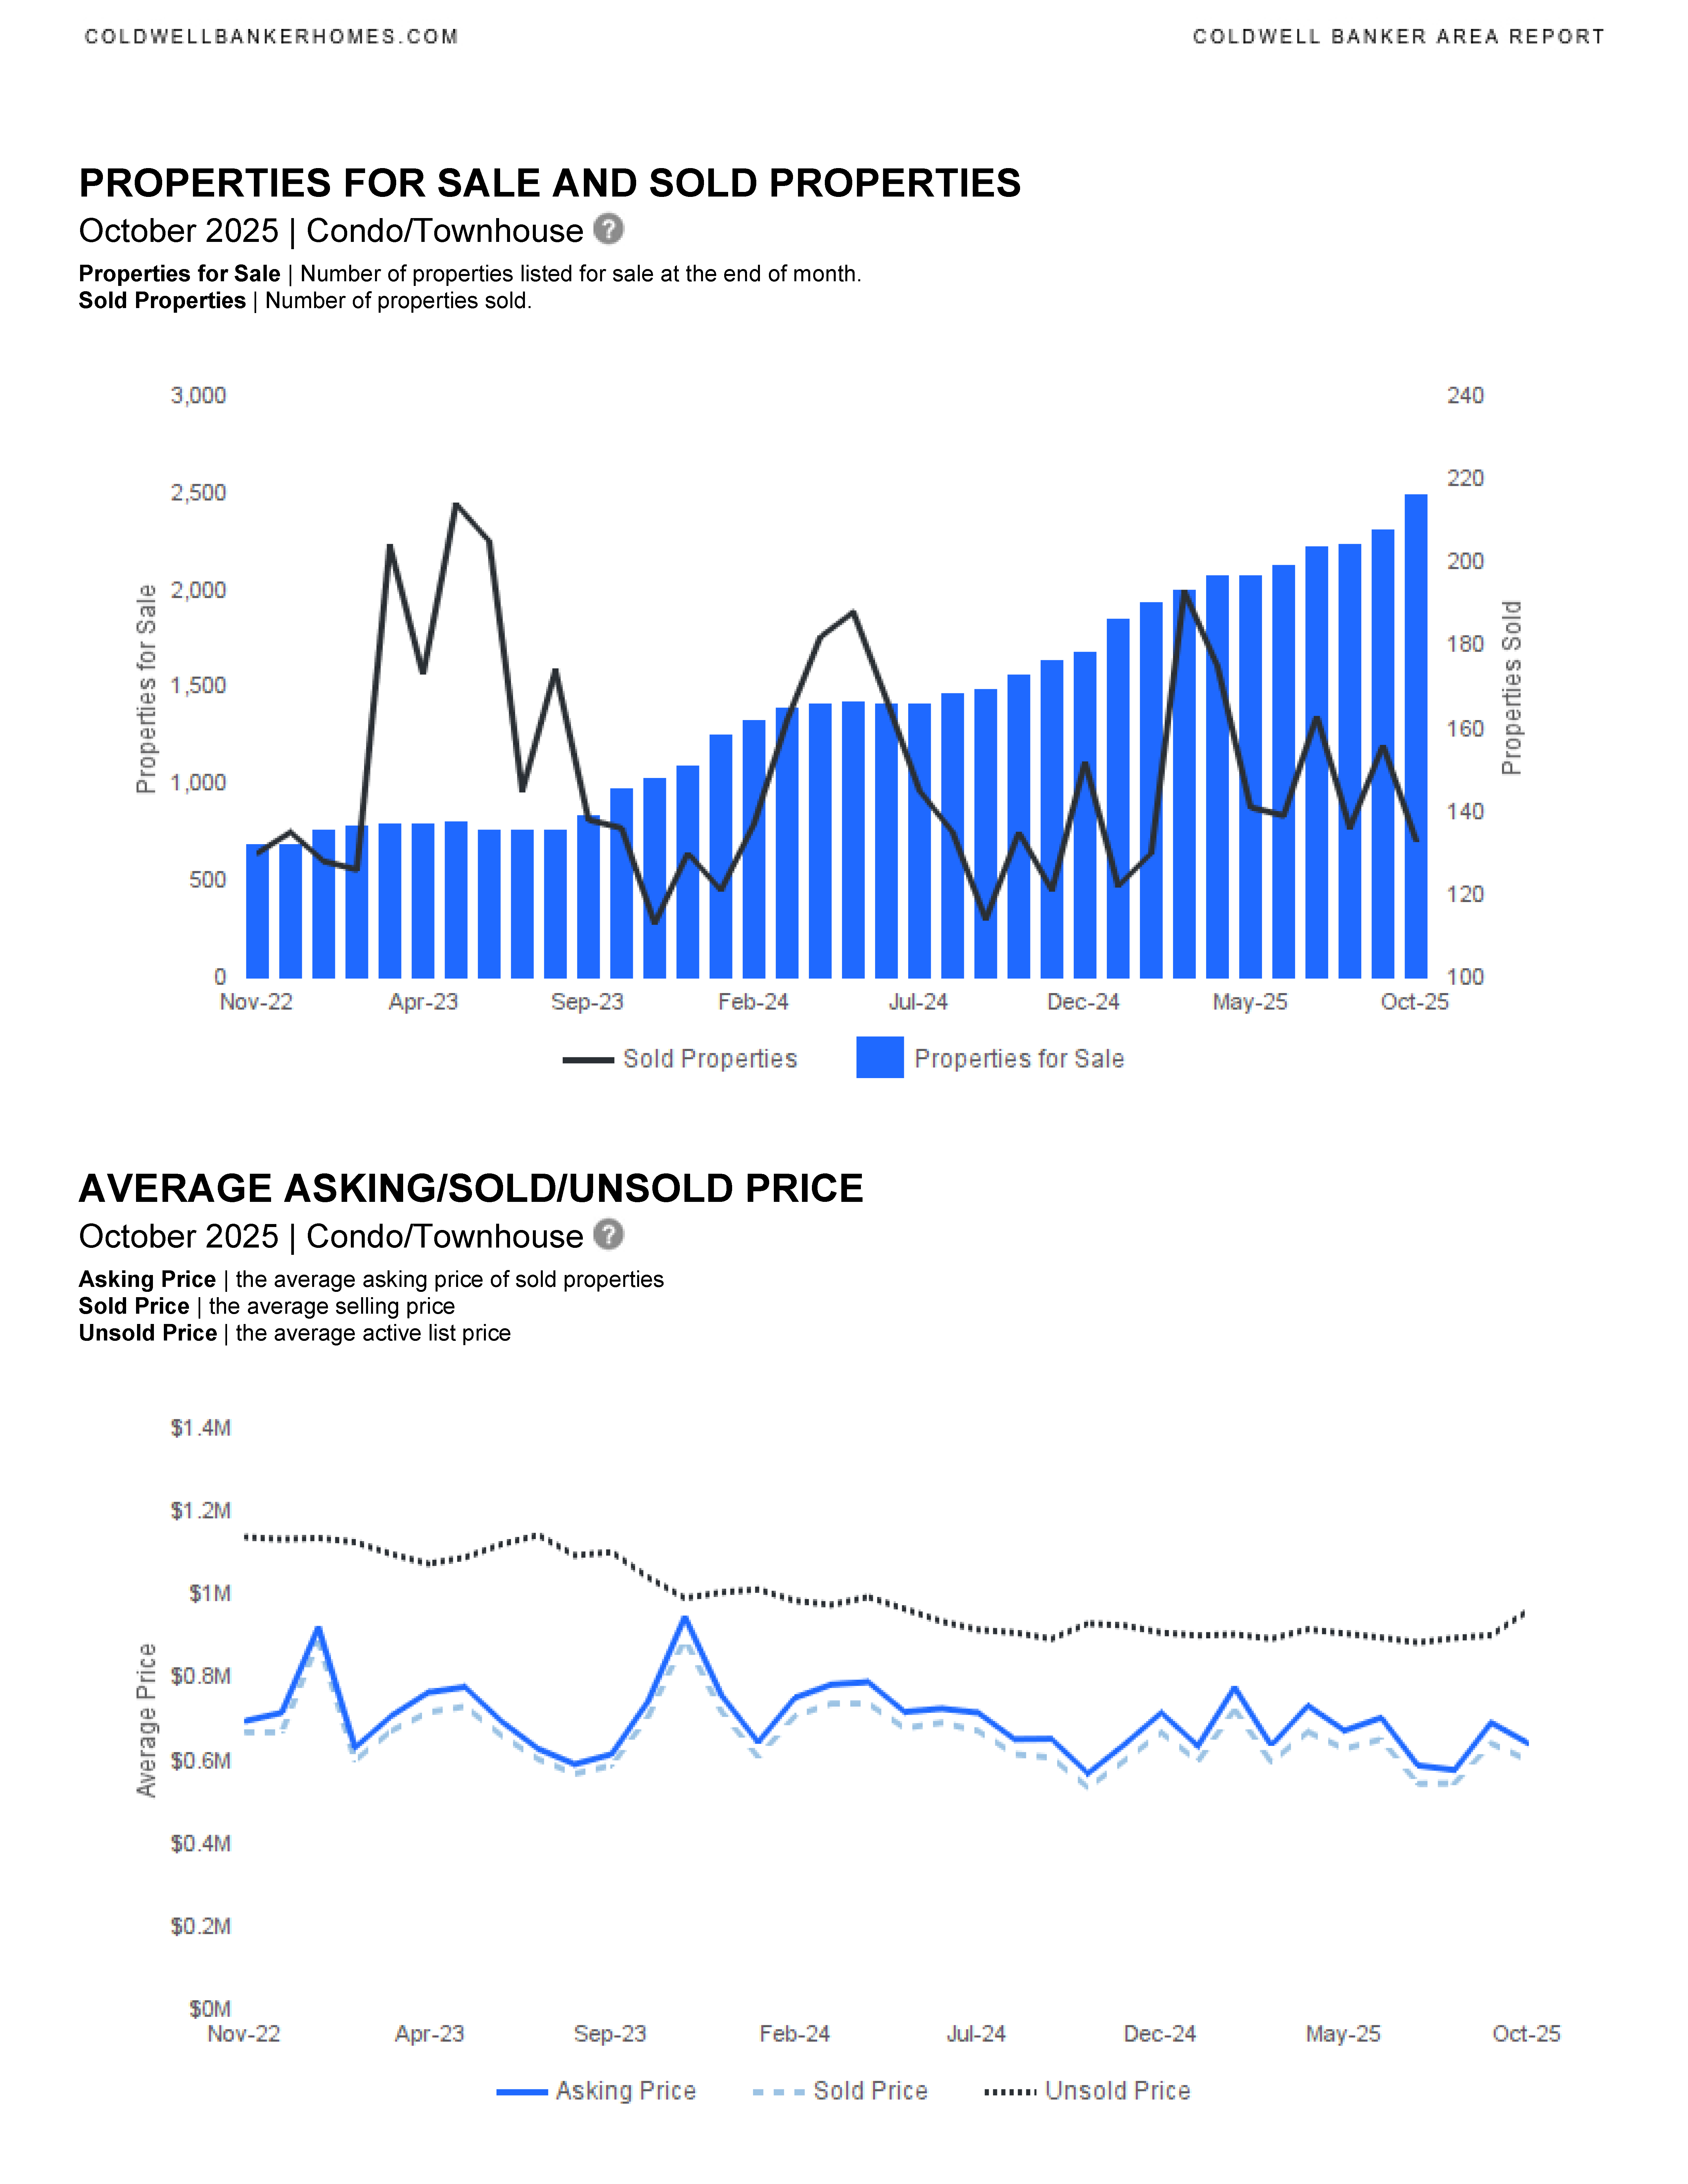
🏢 Condos & Townhomes – October 2025 Highlights
Monthly Changes (vs. October 2024):
- New Listings: 397 (⬇️ 16.6%)
- Sold Listings: 133 (⬇️ 1.5%)
- Median List Price (Solds): $448,000 (⬆️ 14.9%)
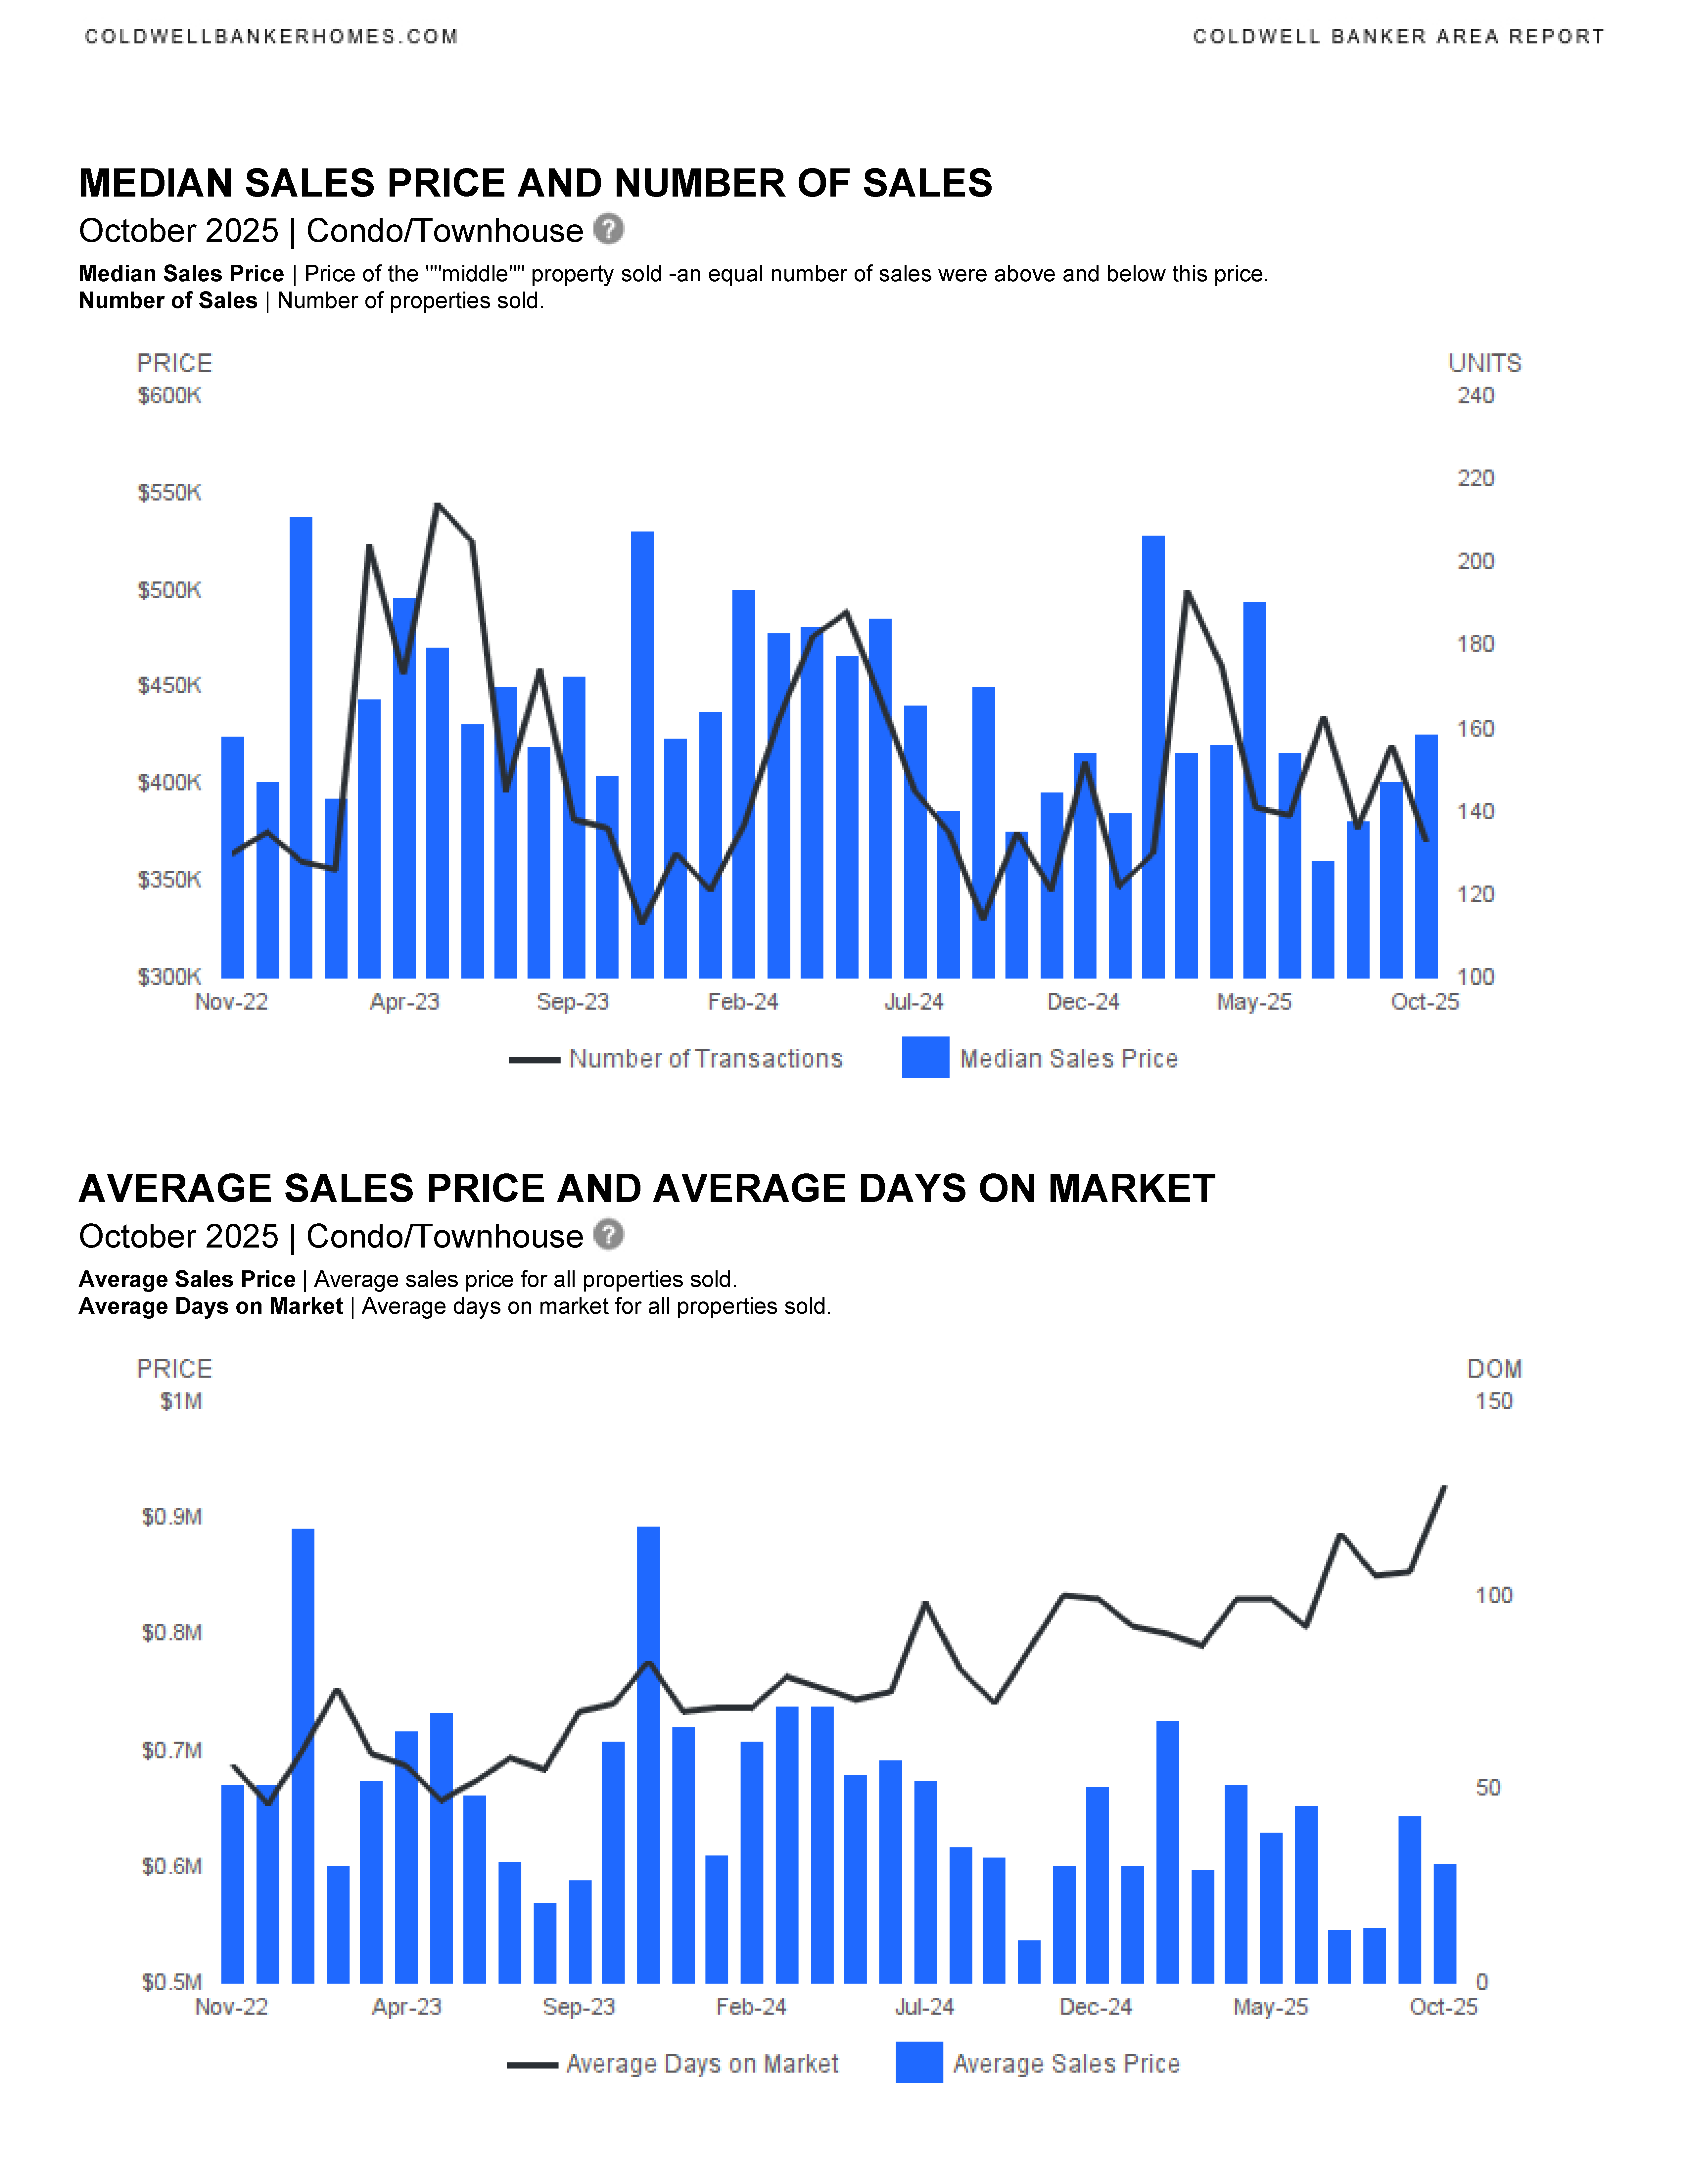
- Median Sold Price: $425,000 (⬆️ 13.3%)
- Average Sold Price: $601,341 (⬆️ 12.4%)
- Average Days on Market: 128 days (⬆️ 48.8%)
- List-to-Sale Price Ratio: 94.2% (⬇️ slightly)
Year-to-Date (YTD) Changes:
- New Listings: 4,397 (⬇️ 10.5%)
- Sold Listings: 1,488 (⬆️ 0.1%)
- Median Sold Price: $415,000 (⬇️ 7.8%)
- Average Sold Price: $619,309 (⬇️ 6.9%)
- Average Days on Market: 101 days (⬆️ 29.5%)
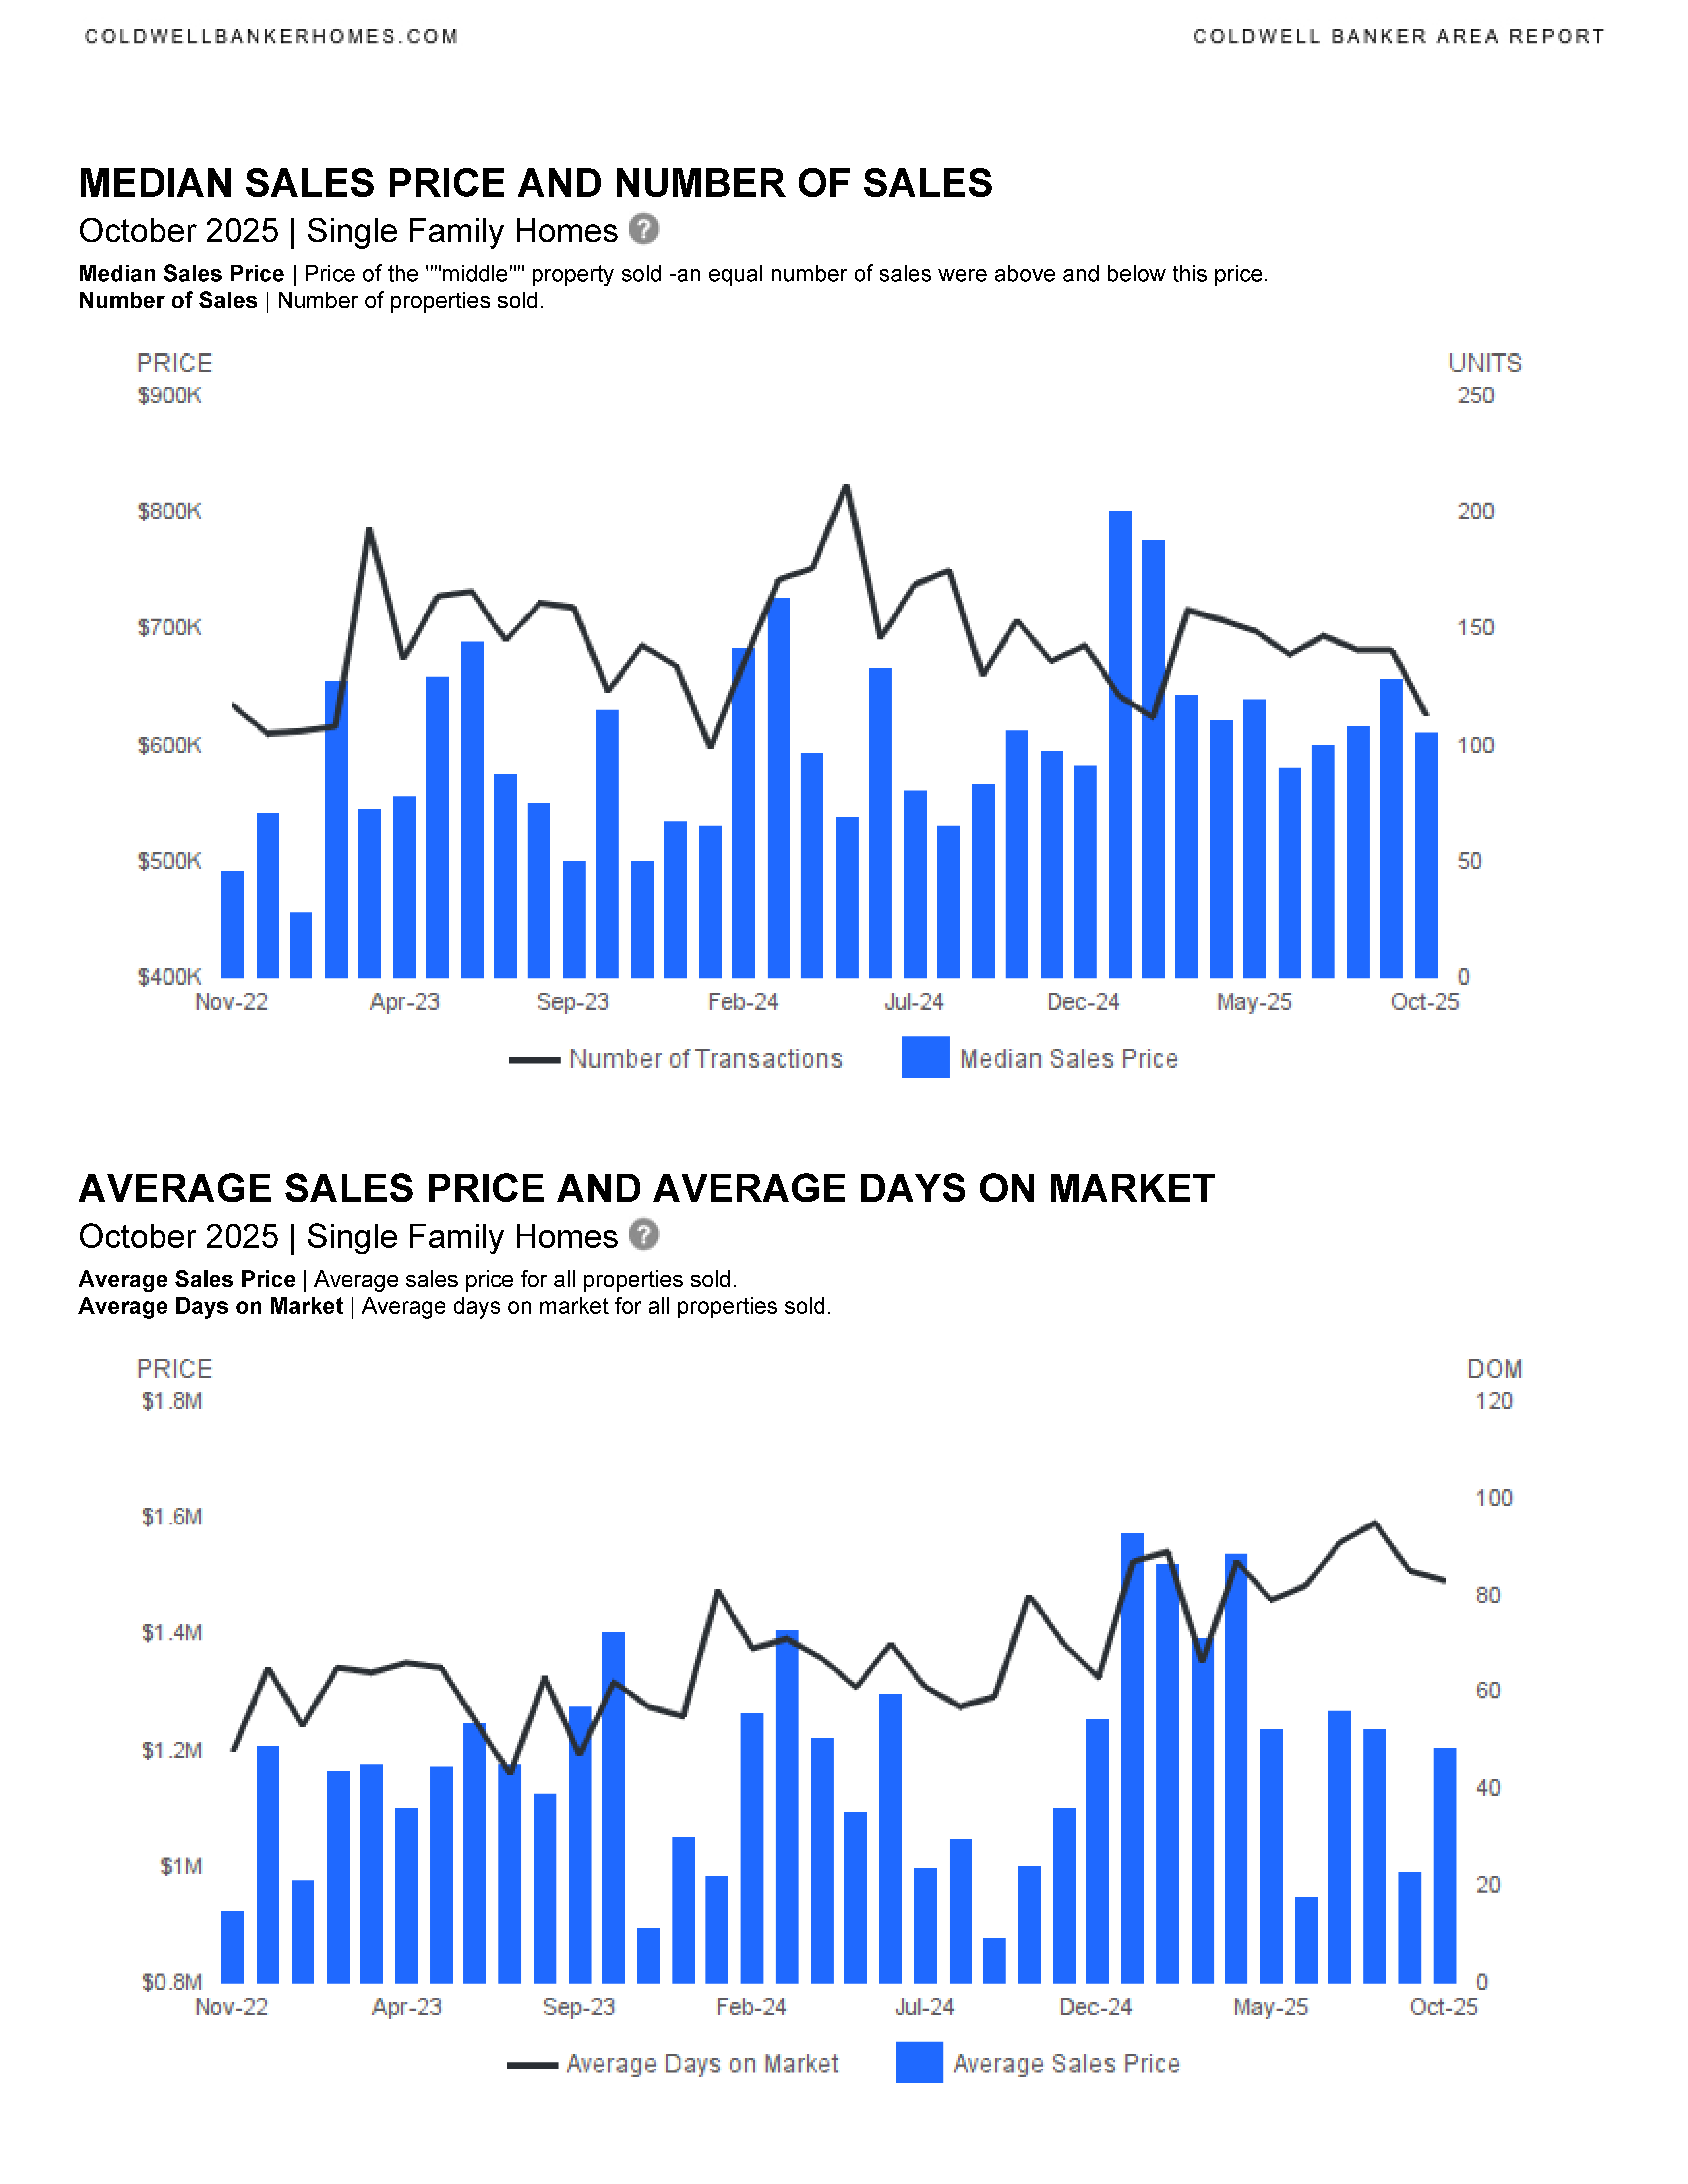
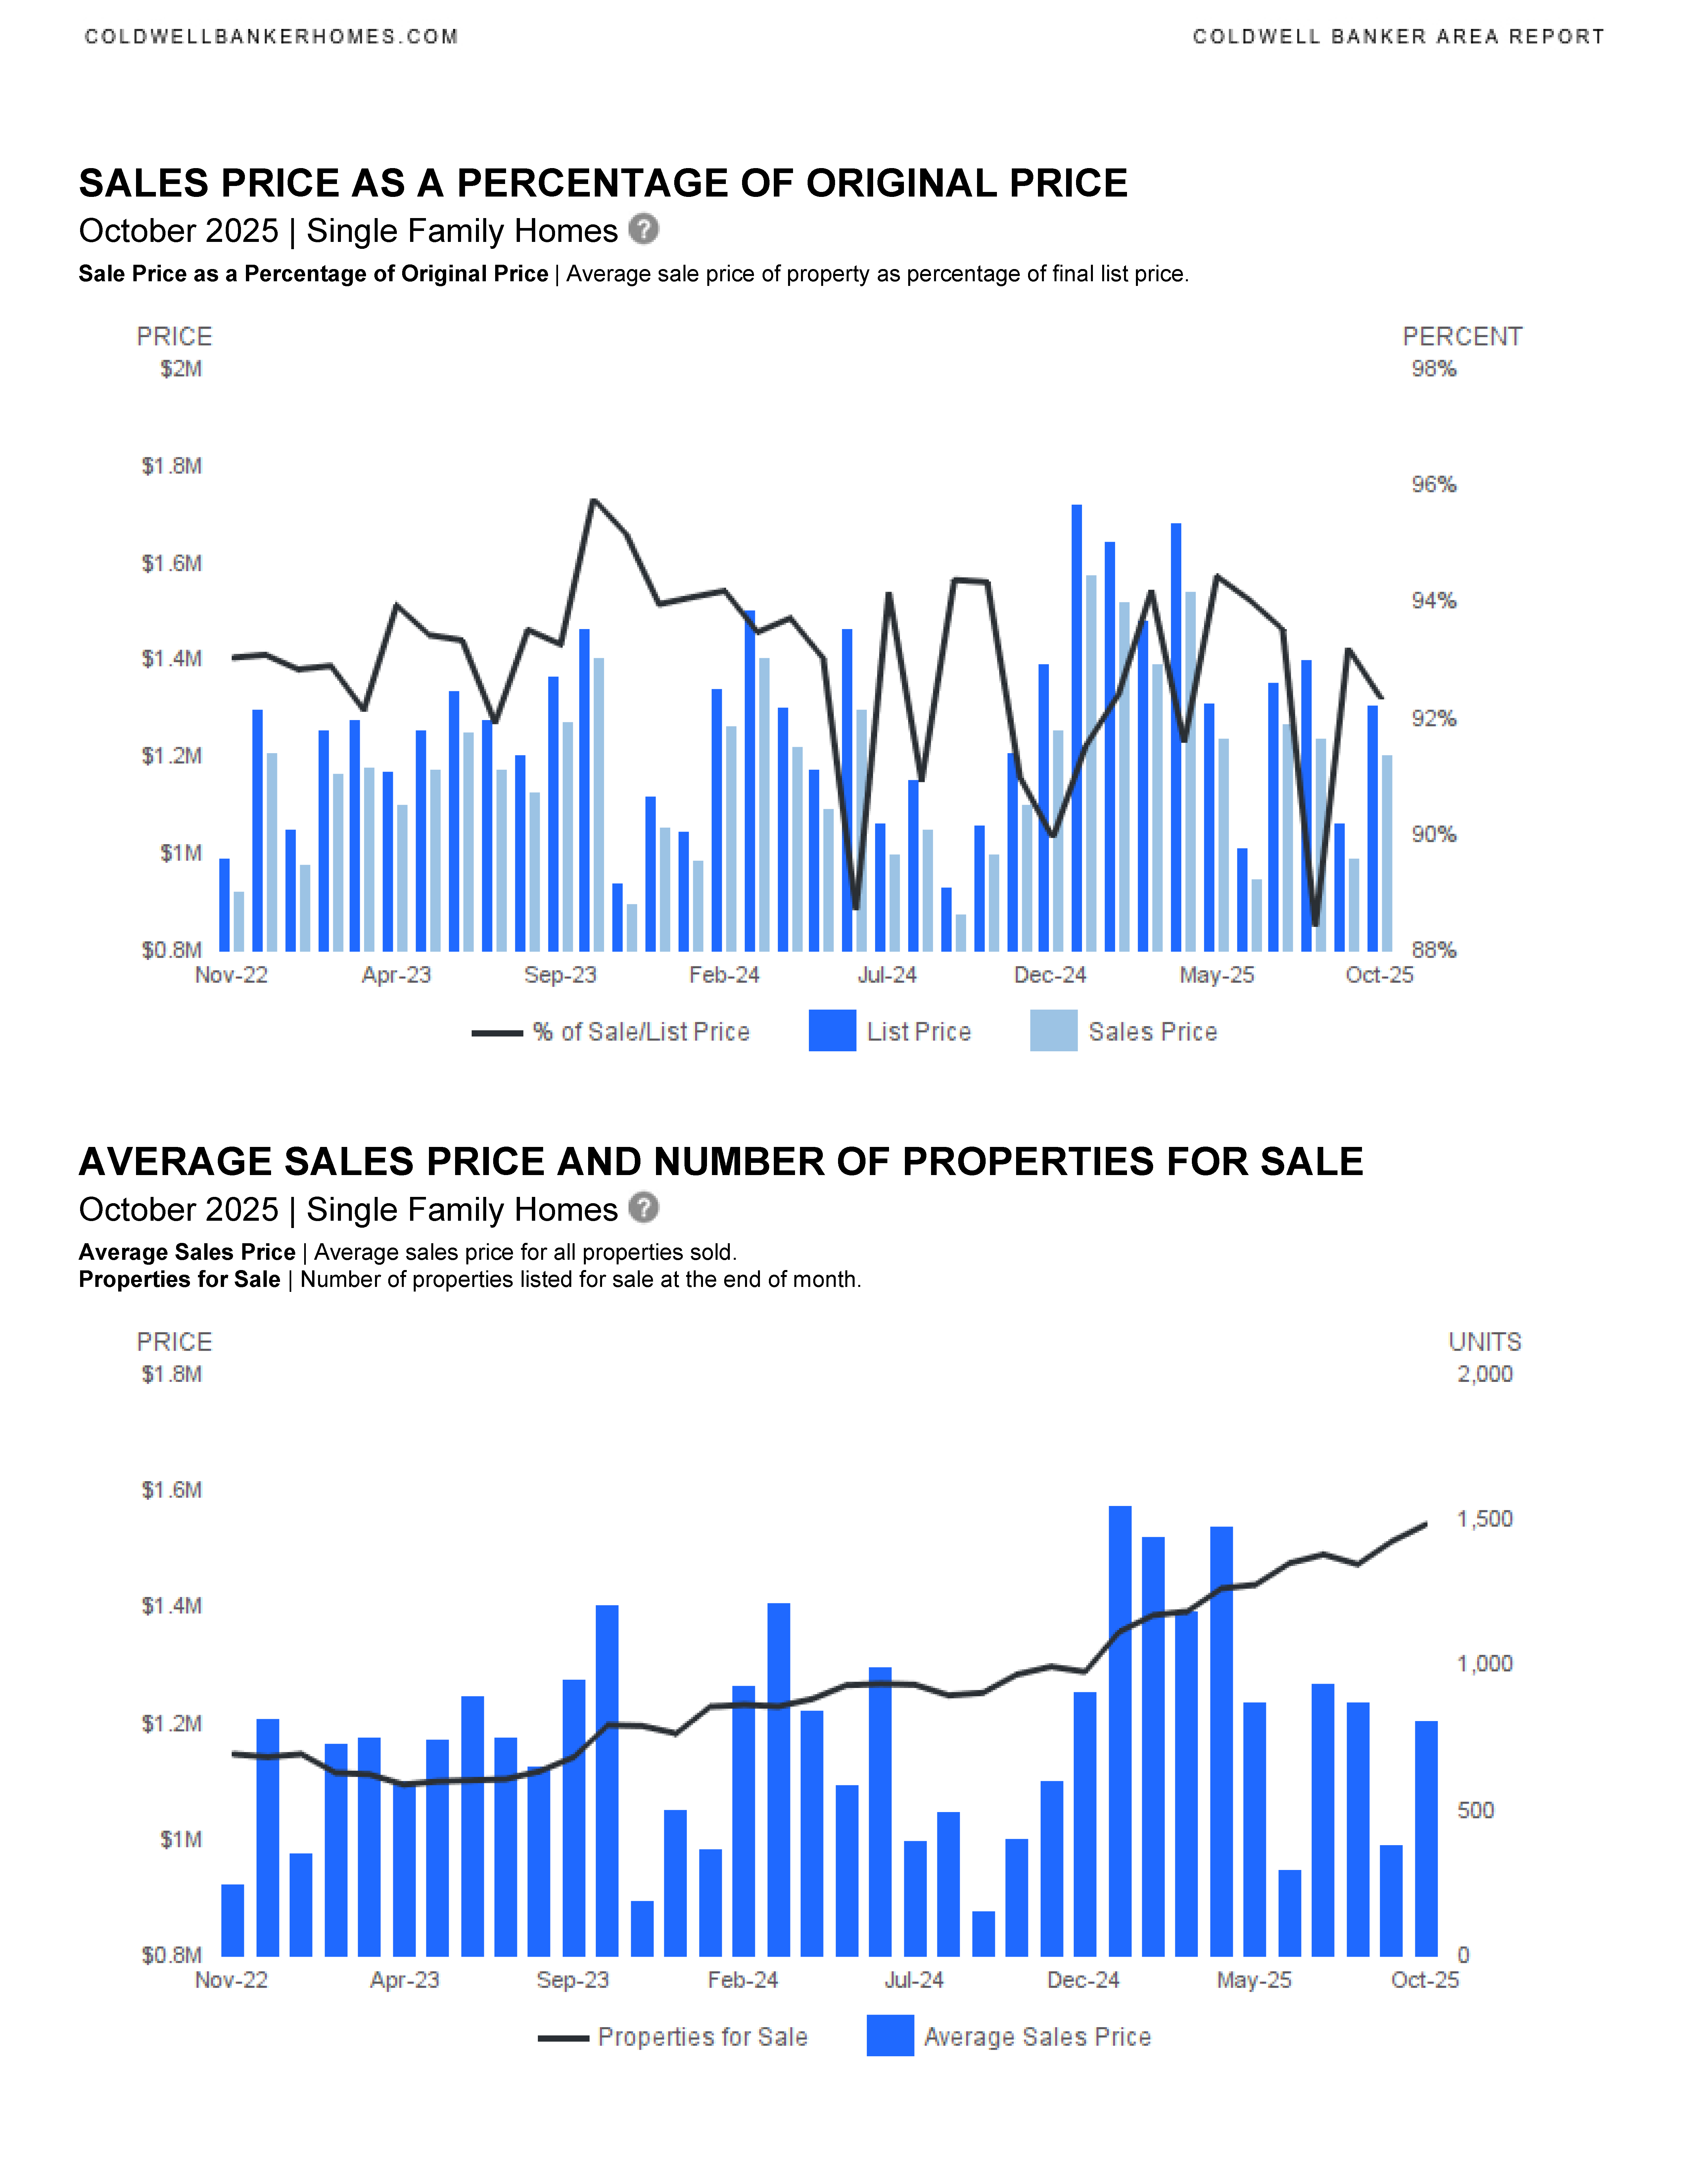
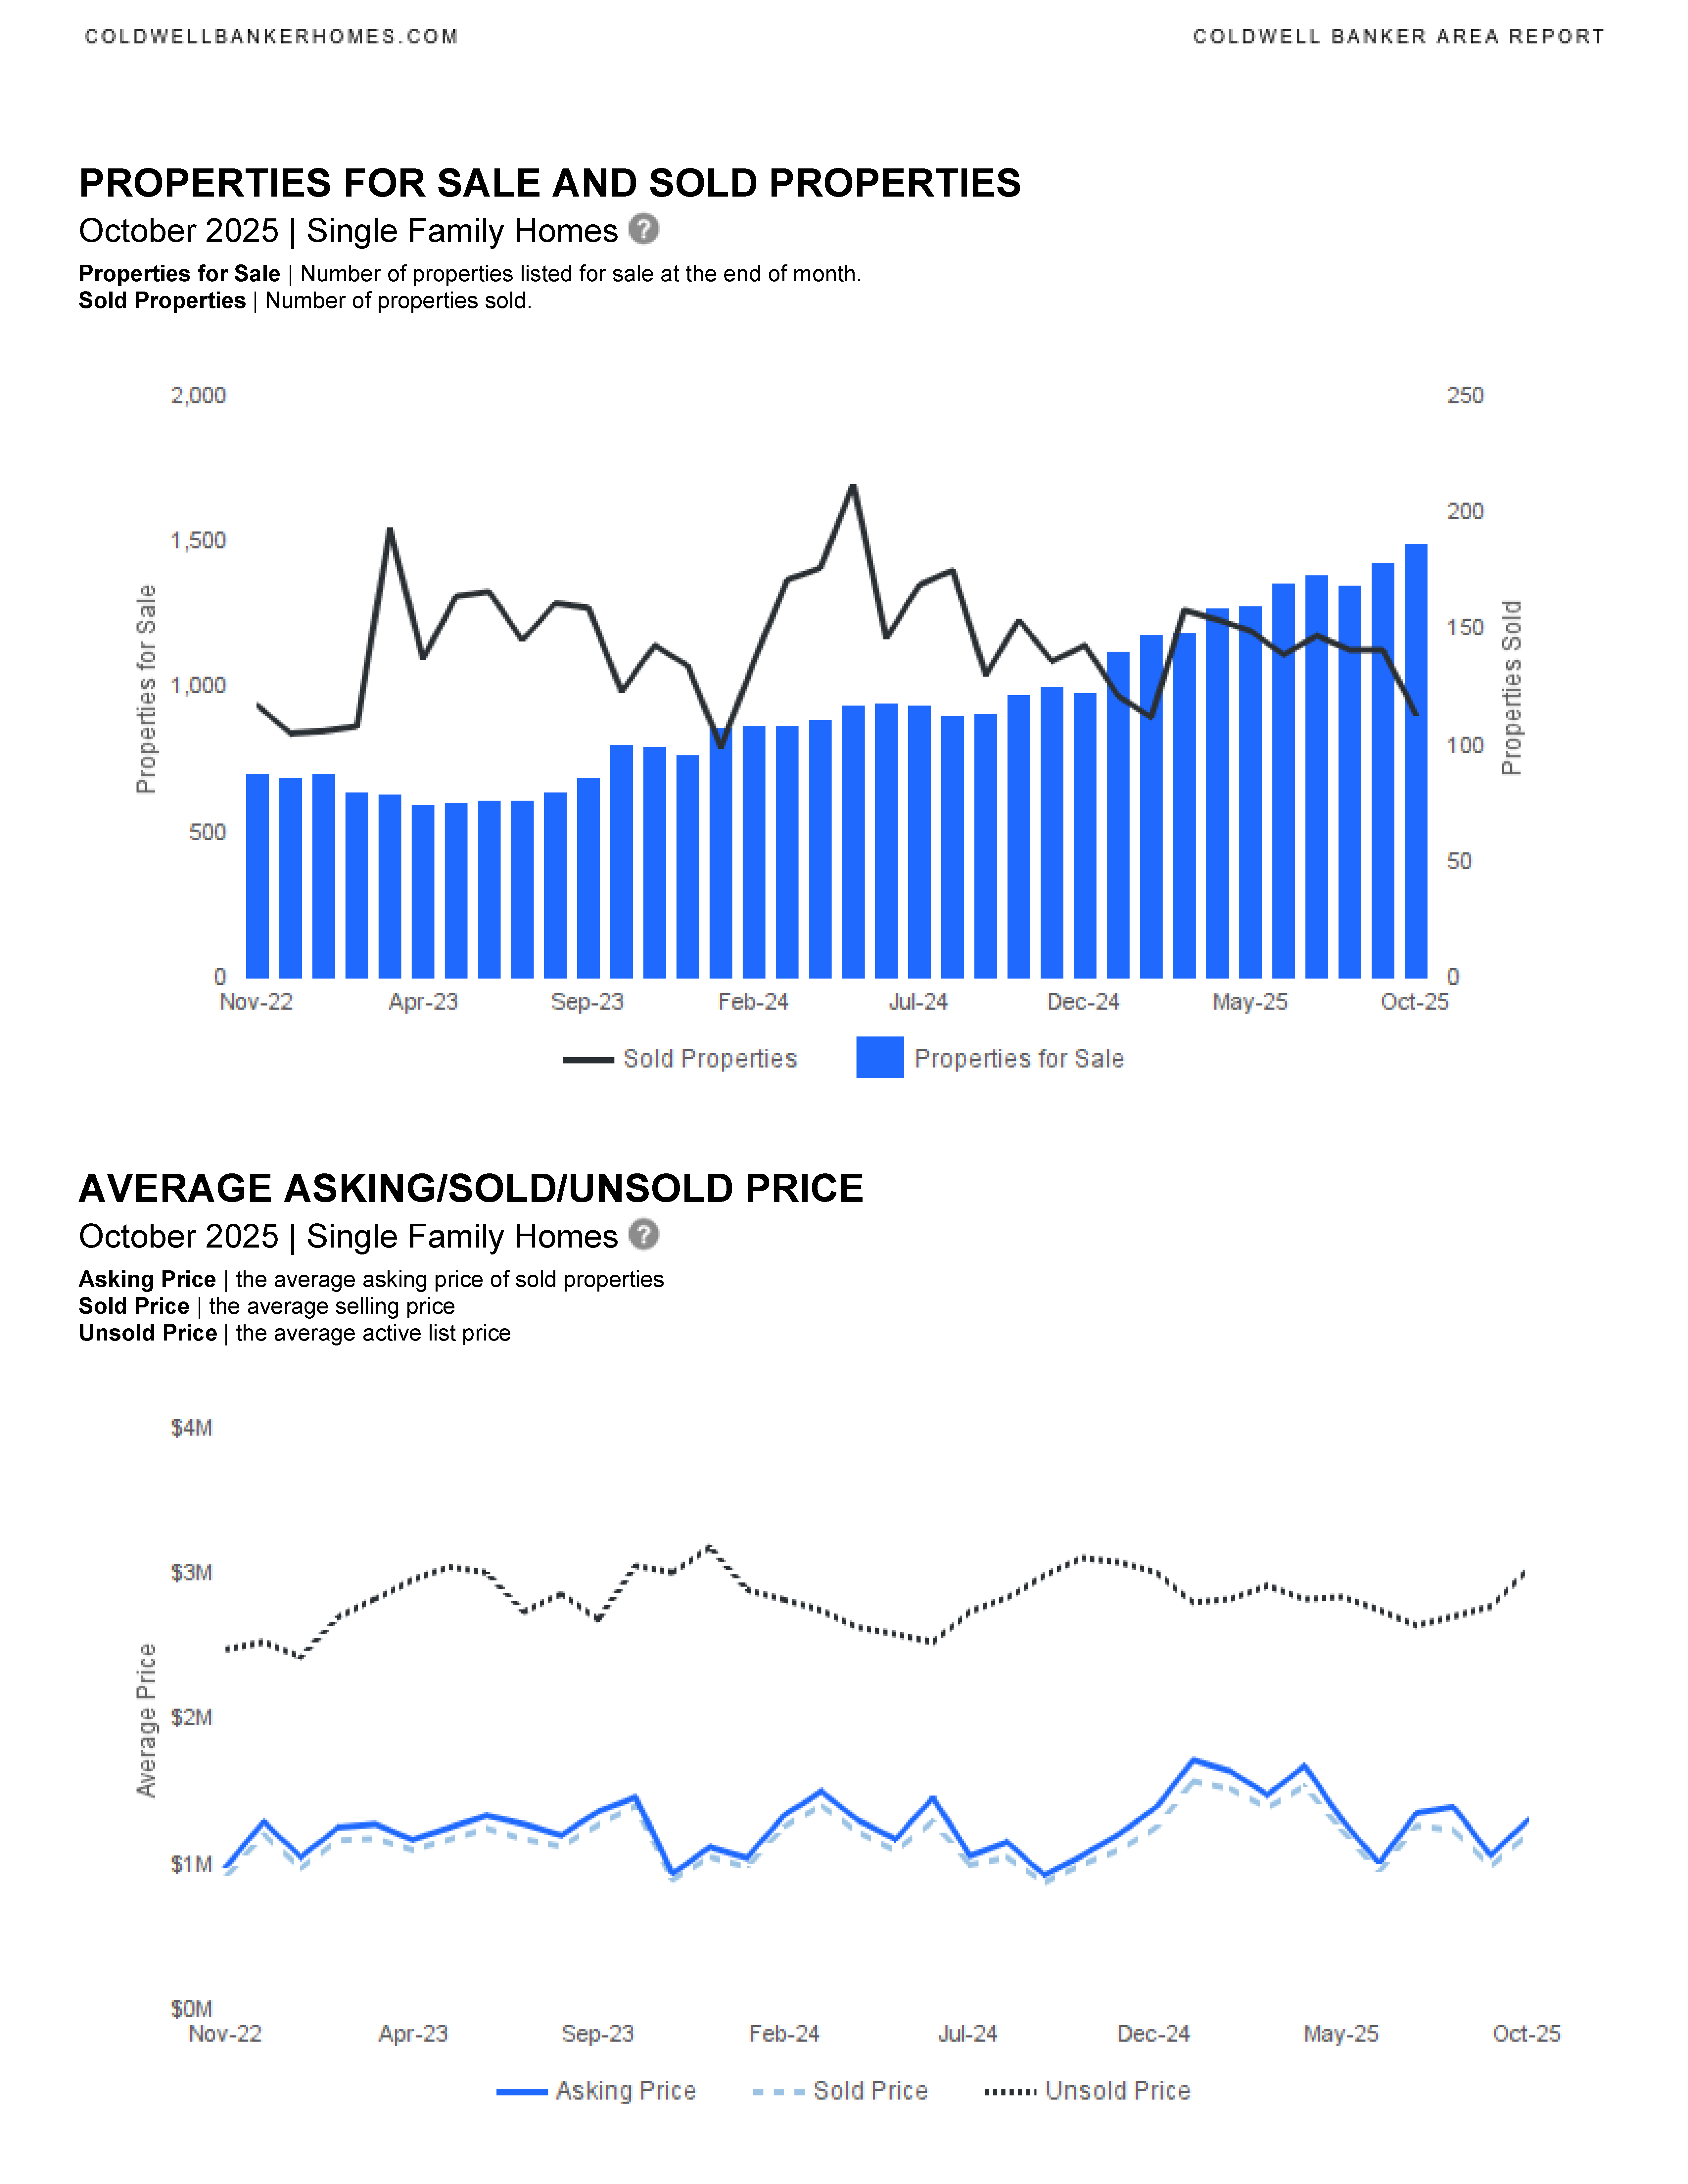
📊 Market Trends Summary
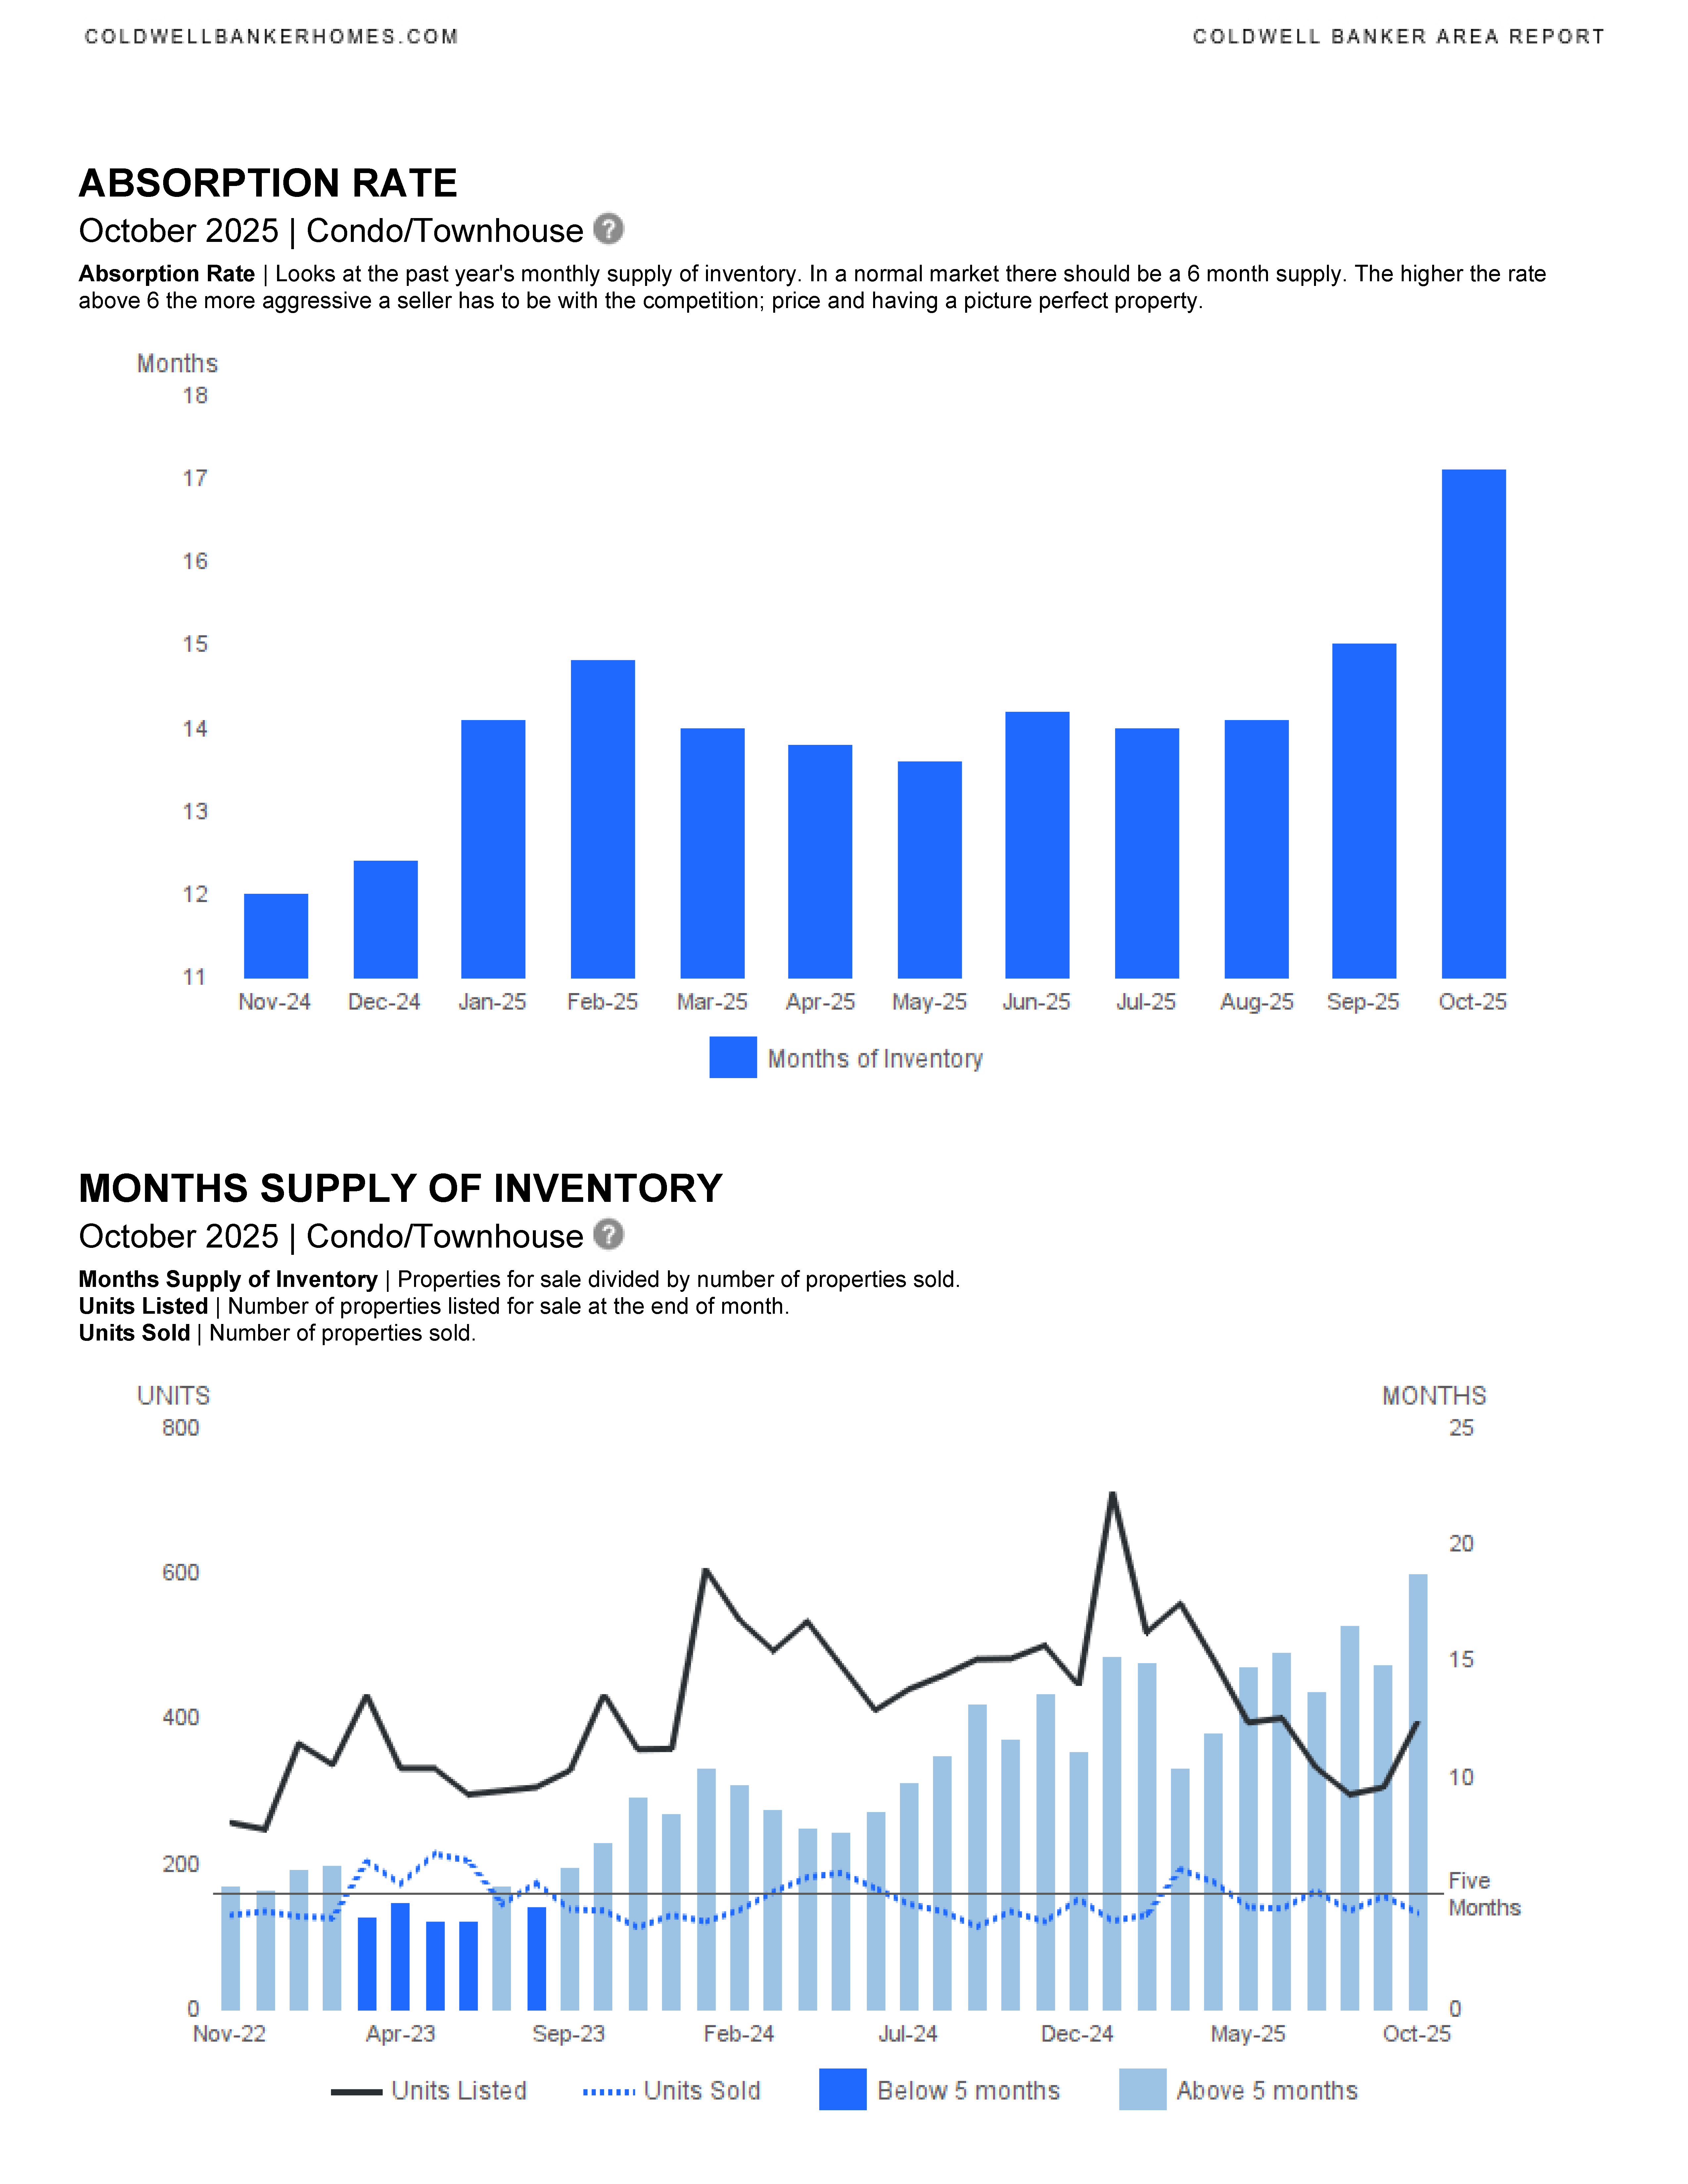
- Inventory is tightening: Fewer new listings and longer days on market suggest a slower-moving market.
- Prices are mixed: Single family homes are seeing price increases, while condos show mixed results (monthly up, YTD down).
- Buyers have more time: Properties are staying on the market longer, especially condos.
- Sellers need to be competitive: Slight drops in list-to-sale price ratios and higher absorption rates indicate more negotiation and competition.

We are in a new housing market in SE Florida. This is the time to work with an experienced and knowledgeable real estate professional. Please contact me if you would like to be sent updated market reports for YOUR specific neighborhood, Fort Lauderdale, or another SE Florida city. We can discuss the market, current trends and how we can work together to accomplish your real estate goals. I am here to help.
CONTACT ANNETTE
Let’s start working together!
Annette Dammeyer, REALTOR®, ABR®, AHWD®
Coldwell Banker Realty
901 E Las Olas Blvd STE 101, Fort Lauderdale, FL 33301
808.747.3686
SL 3535792
Selling & Buying a Home at the Same Time in SE Florida
🏡 Selling & Buying a Home at the Same Time in SE Florida: Your Guide
In South East Florida, where waterfront dreams meet fast-moving markets, many homeowners find themselves asking: Can I sell my current home and buy a new one—without losing my mind or my momentum? The answer is yes—with the right strategy, timing, and support.
Whether you’re upsizing, downsizing, or simply craving a lifestyle shift, here’s your step-by-step guide to making this transition smooth, smart, and stress-free.
🌴 Step 1: Know Your Local Market
South Florida’s real estate rhythm is unique—seasonal surges, cash-heavy buyers, and lifestyle-driven decisions.
- Seller’s Market? You may sell quickly but face competition when buying.
- Buyer’s Market? You’ll have more choices but may wait longer to sell.
👉 Tip: Work with a local expert who understands Fort Lauderdale and surrounding cities along with the waterfront dynamics. Timing is everything and there are “markets within markets”!
💰 Step 2: Get Financially Prepared
Before listing your home, understand your buying power.
- Get Pre-Approved: Know your budget for the next home.
- Estimate Equity: Use your current home’s value to plan your down payment. The first move is understanding your current home’s value. In areas like Broward, Miami-Dade, and Palm Beach Counties, property values can vary dramatically street by street. A comparative market analysis (CMA) reveals what your home could realistically sell for — not just a guess based on online calculators. Knowing your equity helps determine your next home’s budget and what kind of financing options we should explore. Pro tip: Request a pre-listing home evaluation early. Even small updates like fresh paint, decluttering, or professional staging can increase your selling power.
- Bridge Loans: Consider short-term financing to “bridge” the gap between transactions.
- HELOCs or Home Equity Loans: Tap into your equity before selling.
👉 Tip: Talk to a lender who specializes in simultaneous transactions—they’ll help you avoid surprises. I have excellent lender resources for you.
🔁 Step 3: Decide Whether to Sell or Buy First
This depends on your risk tolerance, financial flexibility, and market conditions.
| Option | Pros | Cons |
| Sell First | Know your budget, avoid double mortgages | May need temporary housing |
| Buy First | Secure your dream home | Risk of owning two homes |
| Same-Day Closings | Seamless transition | Requires tight coordination |
| Rent-Back Agreements | Stay in your home after selling | Must negotiate with buyer |
👉 Tip: In SE Florida, rent-back agreements and extended closings are common—use them to your advantage.
📝 Step 4: Use Contingencies Strategically
- Sale Contingency: Your purchase depends on selling your current home.
- Purchase Contingency: Your sale depends on securing your next home.
👉 Tip: These clauses protect you—but may weaken your offer. Lean on your agent to negotiate wisely.
📦 Step 5: Plan Your Move Like a Pro
Logistics matter. Avoid the chaos with a clear plan.
- Hire Movers Early: Especially during peak seasons.
- Use Storage Solutions: If timing doesn’t align perfectly.
- Pack Smart: Label by room and priority.
👉 Tip: Consider staging your current home with minimal furniture while storing the rest—this boosts appeal and simplifies your move.
🤝 Step 6: Choose the Right Team
This is not a DIY moment. You need:
- A savvy real estate agent who knows both sides of the transaction
- A responsive lender
- A detail-oriented title company
👉 Tip: Look for professionals who communicate clearly and understand the emotional weight of this transition.
📞 Step 7: Stay Flexible and Communicative
Even with perfect planning, timing both transactions can feel like catching the tide at just the right moment.
That’s why consistent communication with your agent (and your lender) is key. I’ll coordinate both sides — from listing to closing — ensuring deadlines align and your move feels seamless.
🌅 Final Thoughts: Embrace the Journey
Selling and buying at the same time is a bold move—but it’s also a beautiful one. You’re not just changing homes; you’re evolving your lifestyle. In South East Florida, that might mean trading a canal-front cottage for a high-rise ocean view—or vice versa.
With the right plan, the right people, and a little patience, you can make this move with confidence and clarity.
Ready to Begin?
Let’s create a plan that reflects your goals, your lifestyle, and your timeline. Whether you’re upsizing, downsizing, or simply shifting gears, I’ll help you move with confidence—and maybe even a little joy. Let’s make your next move your best one yet.
CONTACT ANNETTE
Let’s start working together!
Annette Dammeyer, REALTOR®, ABR®, AHWD®
Coldwell Banker Realty
901 E Las Olas Blvd STE 101, Fort Lauderdale, FL 33301
808.747.3686
SL 3535792
SE Florida Market Snapshot – September 2025
Market Trends in SE Florida
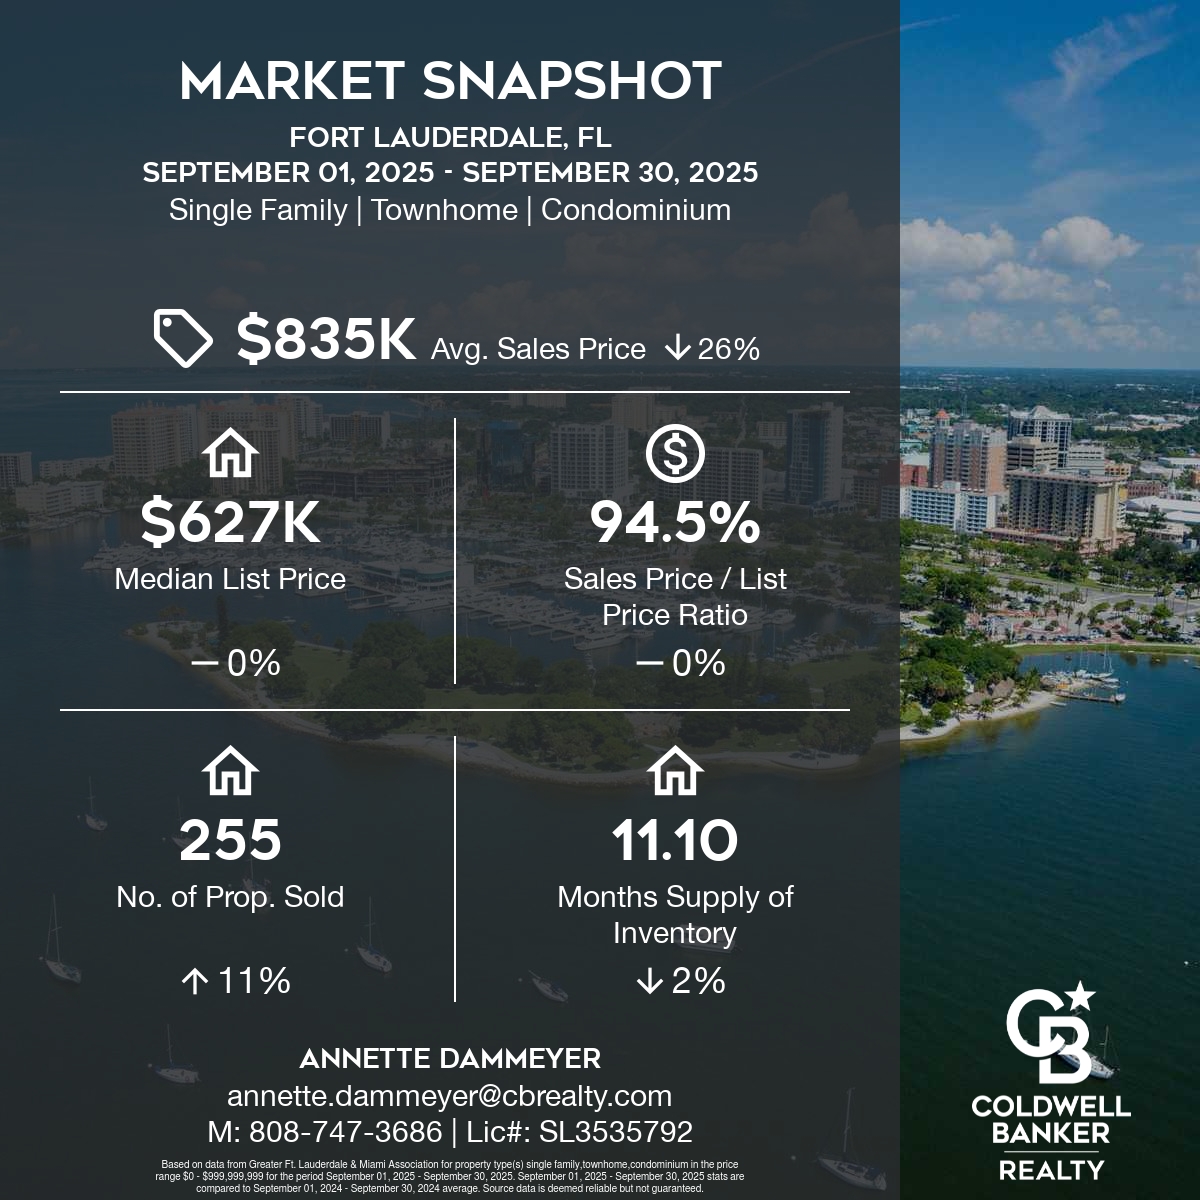
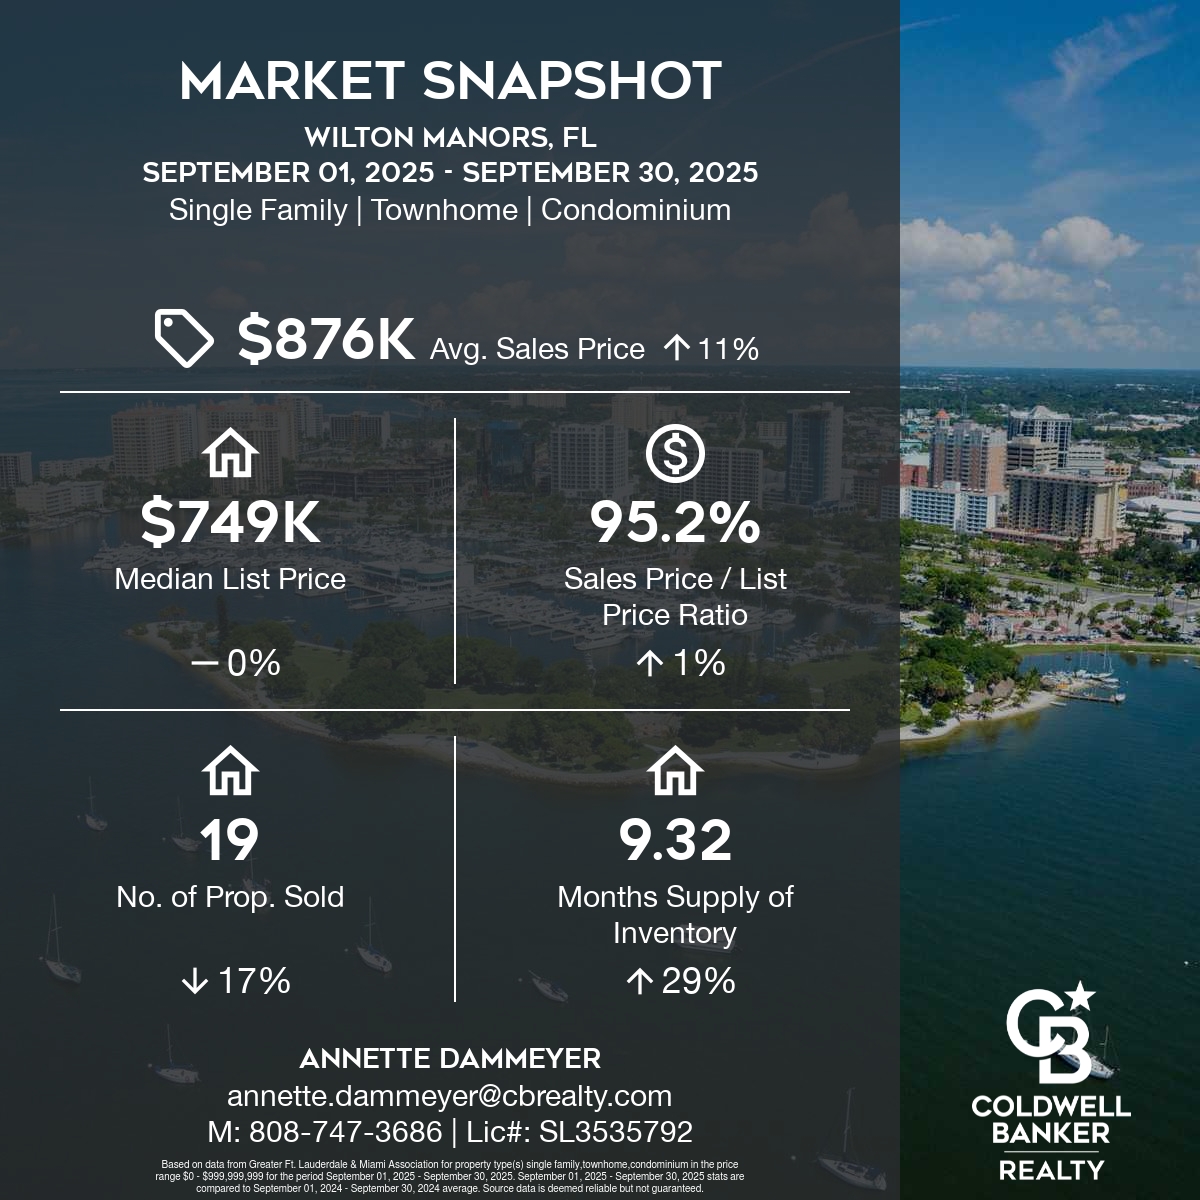
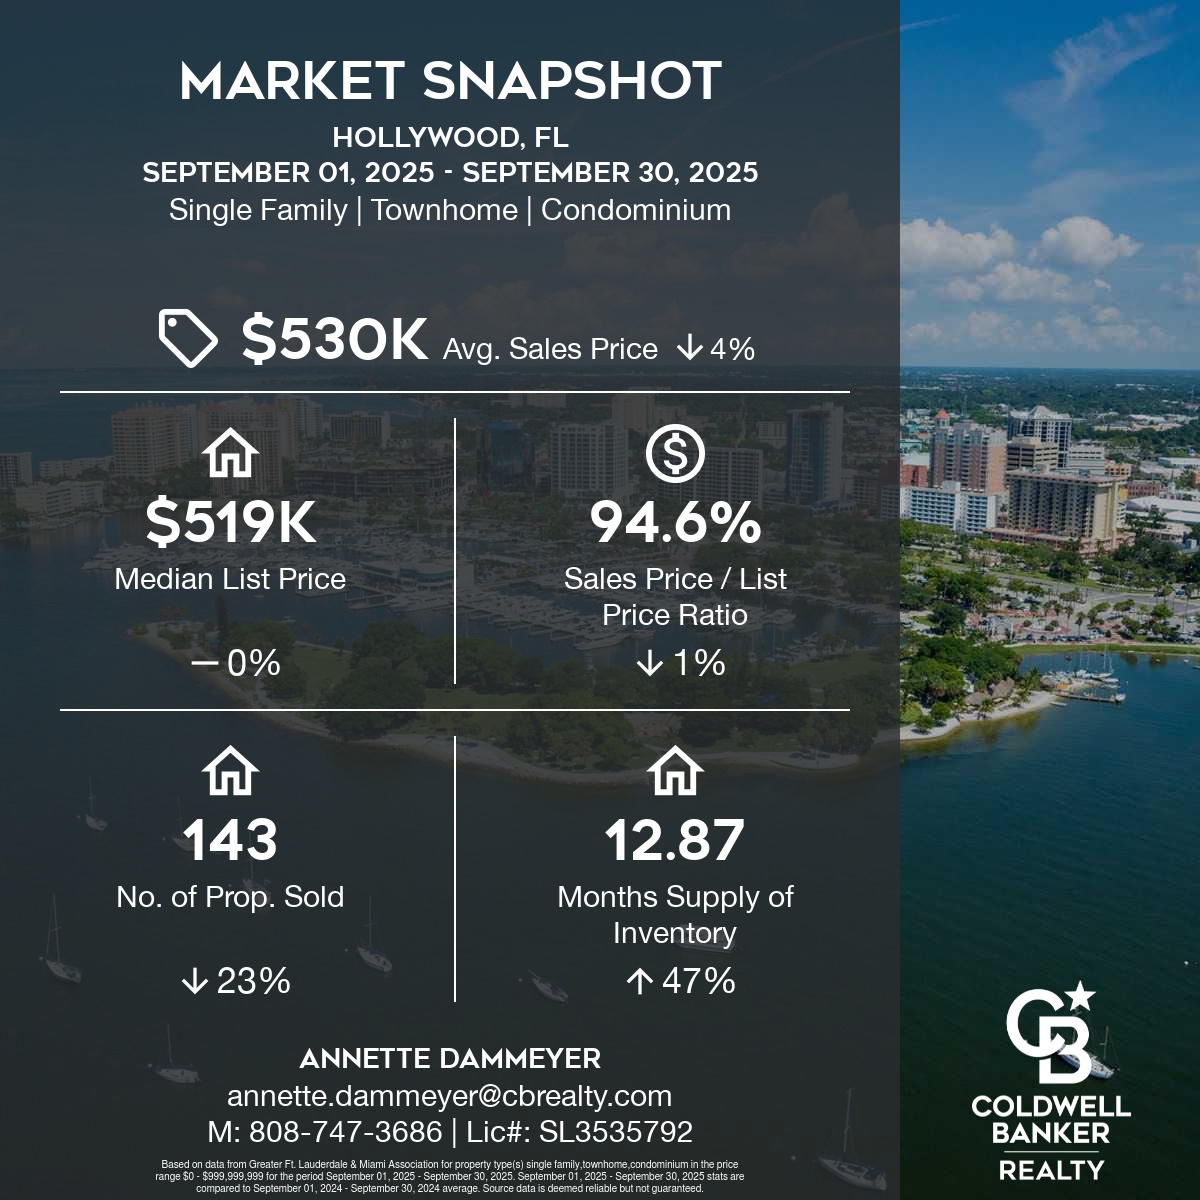
The real estate market is adjusting. With the fluctuation in property inventory, SE Florida is leaning towards a “buyer’s market”. Seller’s are now reassessing their asking price on their properties for sale. It is crucial to examine other similar homes on the market to establish an aggressive original listing price, generating multiple buyer’s attention to your property. This is also an important time to consider a decrease in asking price if the property has been on the market without active offers. I welcome any discussions you may want to have regarding your neighborhood trends. Please reach out to chat, even if you are not ready to buy or sell, but just would like to discuss current real estate updates. Here are the Market Snapshots reflecting the last month (compared to the same month last year) for the following areas:
- Fort Lauderdale
- Wilton Manors
- Hollywood
- Dania Beach
- Hallandale Beach
These take into account all property types (Single Family Homes/Condos/Townhomes).
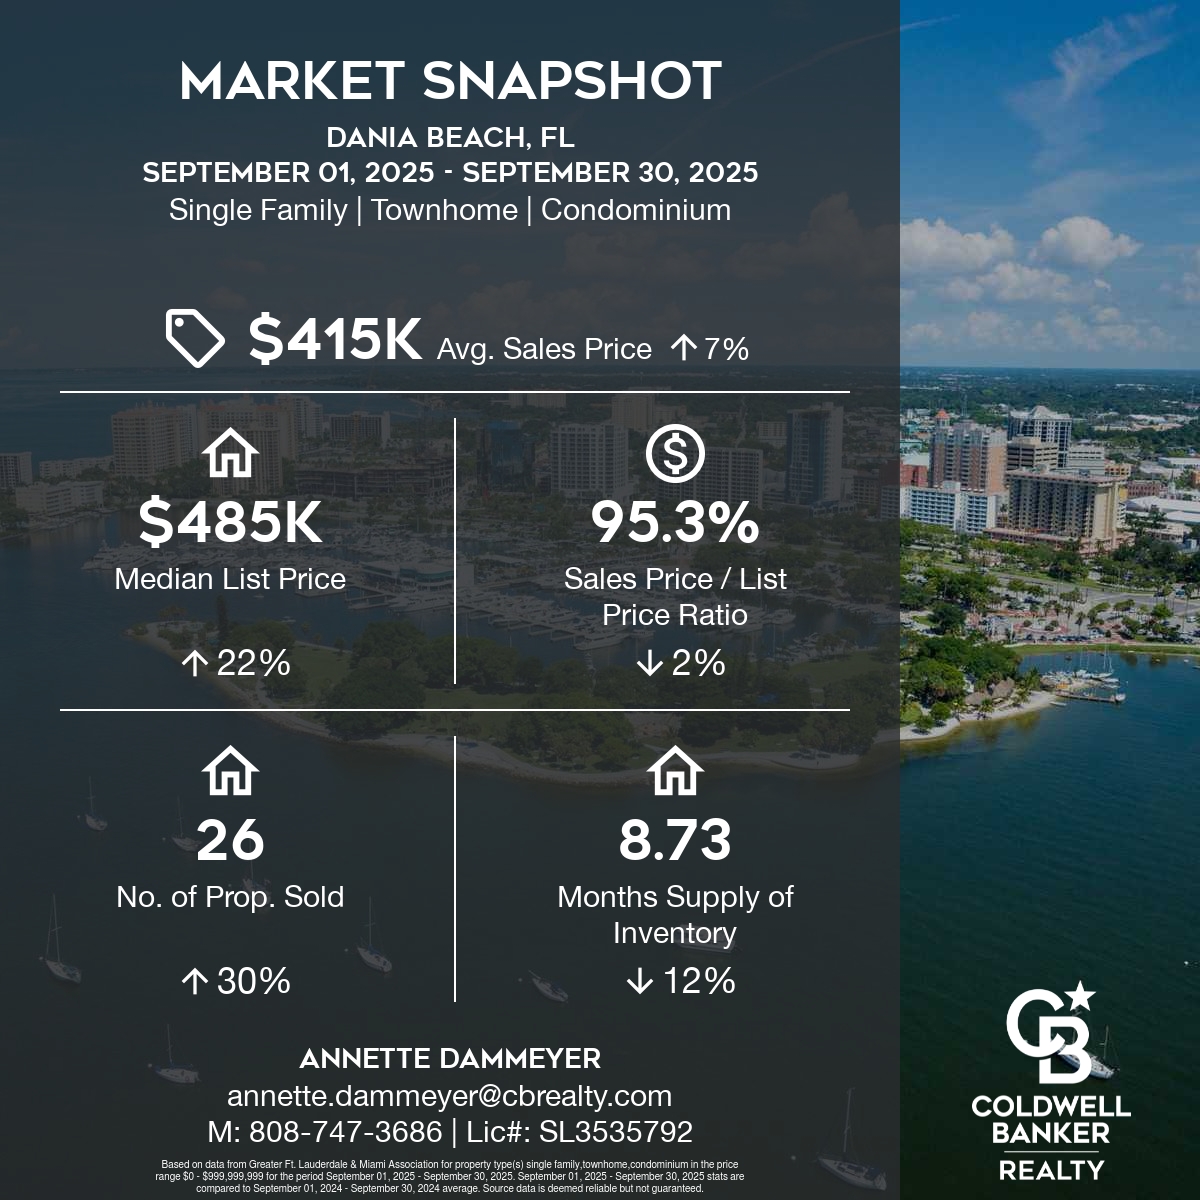
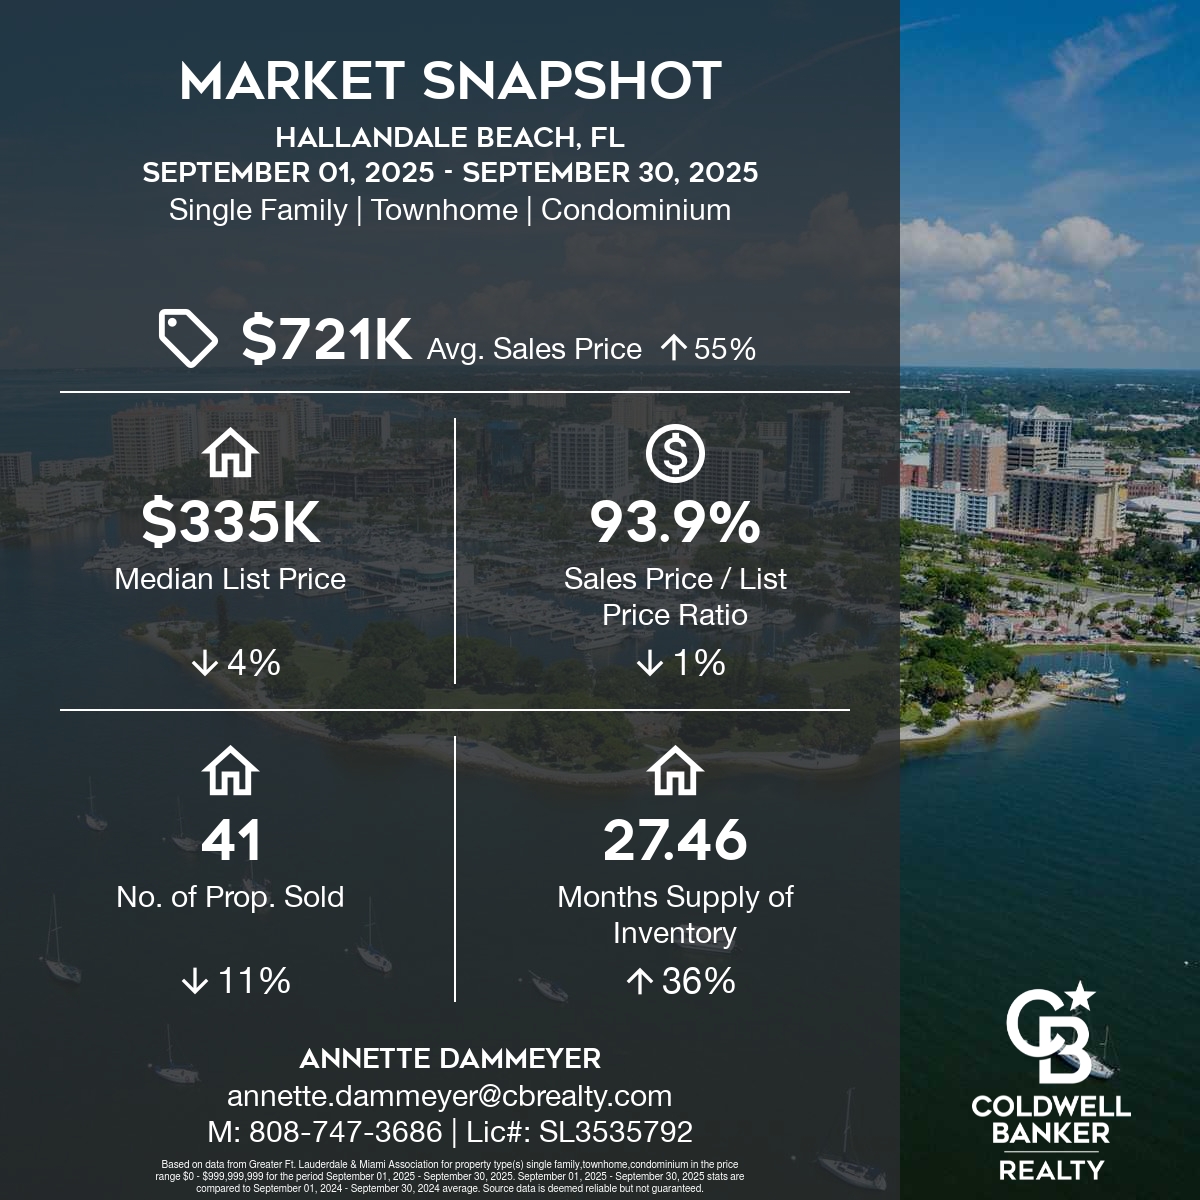
The real estate landscape in South Florida is evolving quickly—and making smart, timely decisions has never been more important. Whether you’re considering selling, buying, or simply staying informed, I’m here to be your local guide and resource.
Let’s talk about current market trends and how we can align your goals with today’s opportunities. I’d be happy to provide customized market reports for Fort Lauderdale, any SE Florida city, or even your specific neighborhood—all automatically delivered to your inbox.
Call or email me anytime. I’m here to help you move forward with clarity and confidence
CONTACT ANNETTE
Let’s start working together!
Annette Dammeyer, REALTOR®, ABR®, AHWD®
Coldwell Banker Realty
901 E Las Olas Blvd STE 101, Fort Lauderdale, FL 33301
808.747.3686
SL 3535792
Navigating Home Insurance in Southeast Florida
🏡 Navigating Home Insurance in Southeast Florida: What Every Homeowner Needs to Know
As a local real estate professional in South Florida’s waterfront and lifestyle-driven communities, I know firsthand how confusing—and crucial—home insurance can be. With recent shifts in the market, including rate reductions from select private insurers (excluding Citizens), now is the time to get informed and empowered.
Let’s break down the essentials so you can protect your investment with confidence.
📉 Positive Trends: Some Insurers Are Lowering Rates
After years of skyrocketing premiums, private insurers are beginning to file for rate decreases in 2025. This is a welcome shift, especially for homeowners in Fort Lauderdale, Hollywood, and surrounding areas who’ve been navigating a volatile insurance market.
Note: Citizens Insurance is not included in these reductions, but its policy count is dropping as private carriers re-enter the market.
🆕 New Home Insurance Providers Entering the SE Florida Market
Thanks to recent legislative reforms aimed at curbing litigation abuse and stabilizing the insurance market, several new private insurers have entered Florida in the past year. These companies are offering competitive rates and broader coverage options, especially in areas like Hollywood, Fort Lauderdale, and Dania Beach.
✨ Notable New Entrants (2024–2025)
Here are some of the most promising new providers now serving SE Florida:
- Viceroy Preferred Insurance
Focused on personalized property coverage with competitive premiums.- Vision Insurance Exchange
Offers flexible policy structures and is gaining traction for its customer-first approach.- Tailrow Insurance Company
Specializes in homeowners insurance with a niche focus on Florida’s unique risks.- Mainsail Insurance Company
Provides bundled options (home, auto, commercial) for convenience and savings.- Orange Insurance Exchange
A Florida-based startup offering innovative, locally tailored solutions.- Trident Reciprocal Exchange
One of the newer carriers authorized to operate statewide.- Ovation Home Insurance Exchange
Known for tech-forward underwriting and streamlined claims processing.These companies are helping to restore competition and lower premiums—a welcome shift for homeowners who’ve faced steep rate hikes in recent years.
🛡️ What Is Citizens Insurance—and Why Are They Depopulating?
Citizens Property Insurance Corporation is Florida’s state-backed insurer of last resort. It was created to provide coverage when private insurers won’t, especially in high-risk areas.
Why It Matters:
- Citizens grew rapidly during the insurance crisis, becoming the largest insurer in Florida.
- However, it’s not designed to be a long-term solution—its rates are often capped and don’t reflect actual market risk.
- If Citizens faces massive claims (e.g., after a hurricane), all Florida policyholders may be assessed fees to cover shortfalls.
🚪 Depopulation Explained:
- As private insurers return to the market, Citizens is encouraging policyholders to switch to private carriers.
- This reduces Citizens’ exposure and helps stabilize the overall insurance ecosystem.
- Homeowners may receive offers from private insurers to take over their Citizens policy—often with better coverage or pricing.
🧮 Understanding Replacement Cost vs. Purchase Price
Insurance premiums are based on replacement cost, not market value.
- Replacement Cost: What it would cost to rebuild your home today using current labor and materials.
- Purchase Price: Influenced by location, demand, and market trends.
💡 Example: A home purchased for $500K may cost $600K to rebuild—your insurance is based on the latter.
🌤️ Best Time to Shop for Insurance: Avoid Hurricane Season
Timing matters.
- Ideal Window: Late fall through early spring (November–April)
- Why: During hurricane season (June–November), insurers often restrict new policies or raise rates due to increased risk.
📍 Zip Code Eligibility Can Change Fast—Act Quickly
Insurance companies frequently open and close zip codes based on risk models.
- If you find a favorable quote, bind it immediately.
- If your home purchase falls through, you can cancel the policy—no harm done.
🏠 Home Age Matters—Even If It’s Renovated
Insurance rates are heavily influenced by the year the home was built, not when it was renovated.
- A renovated 1950s home is still considered a 1950s home.
- To be considered “new construction,” the property must be:
- Completely torn down (no walls left)
- Rebuilt with permits
- Issued a new Certificate of Occupancy
🛠️ Lower Your Premium with a 4-Point Inspection
A 4-point inspection evaluates key systems in older homes and can help reduce your premium if deficiencies are corrected.
What’s Included:
1. 🏚️ Roof
- Inspectors look for:
- Age, condition, leaks, and remaining life
- Typical lifespans:
- Flat: 10–20 years
- Shingle: 15–30 years
- Tile: 25–50 years
- Insurers require at least 5 years of life left (5 years beyond the closing date).
🚫 The Problem with Roof Coatings in SE Florida Insurance
While roof coatings (like acrylic, silicone, or elastomeric sealants) can help protect and extend the life of a roof by sealing cracks and improving water resistance, insurance providers in Southeast Florida typically do not recognize coatings as valid roof replacements.
Why It Matters:
- Coating ≠ Replacement: Insurers view coatings as cosmetic or temporary fixes—not structural upgrades.
- Coverage Denial Risk: If a roof is coated instead of replaced, it may be deemed ineligible for coverage, especially by Citizens Insurance and many private carriers.
- Age Still Counts: Even with a fresh coating, the roof’s original age remains unchanged in the eyes of insurers.
Citizens Insurance explicitly states that using coatings in place of full replacement makes the property ineligible for coverage.
🔍 Bottom Line for Homeowners:
If you’re trying to insure or sell a home with a coated roof, be prepared for:
- Higher premiums
- Limited carrier options
- Possible denial of coverage
For insurance purposes, a roof must be structurally replaced—not just cosmetically refreshed—to be considered compliant.
2. ⚡ Electrical
- Inspectors check:
- Panel type, wiring, grounding, and safety
- Panels often rejected:
- Federal Pacific (FPE)
- Zinsco
- Challenger
- Sylvania (certain models)
- Stab Lok
3. ❄️ HVAC & Water Heater
- Life expectancies:
- AC/HVAC: 10–15 years
- Water Heater: 8–12 years
- Tip: Water-related claims are the #1 source of insurance payouts—keep these systems updated.
4. 🚰 Plumbing
- Inspectors assess:
- Pipe material, leaks, water pressure
- Preferred pipes:
- Copper, CPVC, PEX
- Problem pipes:
- Polybutylene (gray plastic, often stamped “PB2110”)
- These must be replaced to avoid coverage denial.
🌬️ Wind Mitigation Inspection: Save Big with Impact Protection
A wind mitigation inspection can significantly reduce your premium.
- What it checks:
- Roof shape and attachment
- Impact-rated windows and doors
- Shutters and garage door reinforcement
- All windows and doors must be impact
- 🪟 Partial Impact Protection: How It Affects Insurance Premiums in SE Florida
In Southeast Florida, insurance companies reward homes with full impact protection—meaning all exterior openings (windows, doors, skylights, and garage doors) must be impact-rated or have approved shutters.
🔍 What Happens If Only Some Are Impact?
- No Full Credit: If only some windows or doors are impact-rated, the home typically does not qualify for the highest wind mitigation discounts.
- Tiered Discounts: Florida law allows insurers to offer tiered credits, but partial protection often falls into a lower category—sometimes resulting in minimal or no premium reduction.
- Uniform Mitigation Verification Form: Inspectors must document each opening. If any are unprotected, the form reflects that, and insurers adjust the discount accordingly.
Example: A home with 80% impact windows but a non-impact front door and garage door may still be considered unprotected under wind mitigation standards.
🏷️ Why Full Impact Matters
- Windstorm coverage is a major portion of Florida premiums—often 60–70% of the total.
- Homes with full impact protection can save 10–45% on that portion of the premium.
- Partial protection may only qualify for basic credits, or none at all, depending on the carrier.
⚠️ Pro Tip: Never Remove Impact Labels
To qualify for discounts, insurers require:
- Visible labels with product approval codes (e.g., Miami-Dade= NOA or ASTM standards, Broward= TAS/Product Approval #)
- Documentation from the manufacturer or installer
Removing labels can make it impossible to verify compliance—even if the product is impact-rated.
🌊 Flood Insurance: Always a Smart Move in SE Florida
Flooding isn’t just a coastal issue—it can happen anywhere.
- Covers:
- Water damage from rising water, storm surge, and seepage
- Flood insurance rates are not decreasing and remain essential.
- Flood zones:
- Zone A & V: Mandatory insurance if you have a mortgage
- Zone X: Optional but recommended (not optional for Citizens)
💡 Even if you’re in Zone X, a low-cost policy can protect you from unexpected events.
💬 Final Thoughts from Your Local Real Estate Ally
I hope this guide helps you feel more confident navigating home insurance in Southeast Florida. Whether you’re buying, selling, or simply reviewing your current policy, knowledge is power—and protection.
If you’d like trusted referrals to local insurance providers or want to review your own policy, I’m happy to connect you with professionals who understand our unique market.
Let’s keep your home—and peace of mind—secure.
Your SE Florida Real Estate Guide & Advocate
CONTACT ANNETTE
Let’s start working together!
Annette Dammeyer, REALTOR®, ABR®, AHWD®
Coldwell Banker Realty
901 E Las Olas Blvd STE 101, Fort Lauderdale, FL 33301
808.747.3686
SL 3535792


